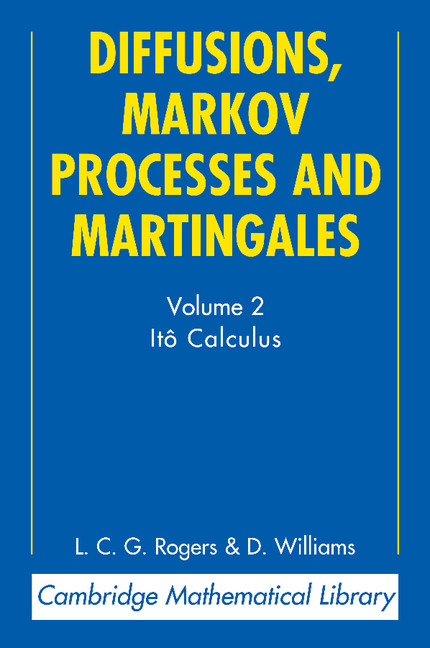
Diffusions, Markov Processes and Martingales

-
Select format
-
- Publisher:
- Cambridge University Press
- Publication date:
- 05 August 2014
- 07 September 2000
- ISBN:
- 9780511805141
- 9780521775939
- Dimensions:
- Weight & Pages:
- Dimensions:
- (228 x 152 mm)
- Weight & Pages:
- 0.808kg, 496 Pages
You may already have access via personal or institutional login
Volume 2: Itô Calculus, 2nd edition
Show more authors 
You may already have access via personal or institutional login
Book description
This celebrated book has been prepared with readers' needs in mind, remaining a systematic treatment of the subject whilst retaining its vitality. The second volume follows on from the first, concentrating on stochastic integrals, stochastic differential equations, excursion theory and the general theory of processes. Much effort has gone into making these subjects as accessible as possible by providing many concrete examples that illustrate techniques of calculation, and by treating all topics from the ground up, starting from simple cases. Many of the examples and proofs are new; some important calculational techniques appeared for the first time in this book. Together with its companion volume, this book helps equip graduate students for research into a subject of great intrinsic interest and wide application in physics, biology, engineering, finance and computer science.
Reviews
‘I welcome the paperback edition version of this masterfully written text.’
Paul Embrechts Source: JASA
‘The monograph as a whole is warmly recommended to post-PhD students of probability and will be welcomed as a good and reliable reference.’
Source: EMS
‘… will be read with pleasure and advantage by experts in the field and its applications, as well as by those probabilists and others who wish to learn the subject … an exciting and enjoyable introduction to the rich ideas of the Itô calculus … there is nothing dry about this book, for its authors have already breathed life into a vibrant subject.’
Mathematics Today
Contents
Contents
Metrics
Altmetric attention score
Full text views
Full text views helpTotal number of HTML views: 0
Total number of PDF views: 0 *
 Loading metrics...
* Views captured on Cambridge Core between #date#. This data will be updated every 24 hours.
Usage data cannot currently be displayed.
Accessibility standard: Unknown
Why this information is here
This section outlines the accessibility features of this content - including support for screen readers, full keyboard navigation and high-contrast display options. This may not be relevant for you.
Accessibility Information
Accessibility compliance for the PDF of this book is currently unknown and may be updated in the future.