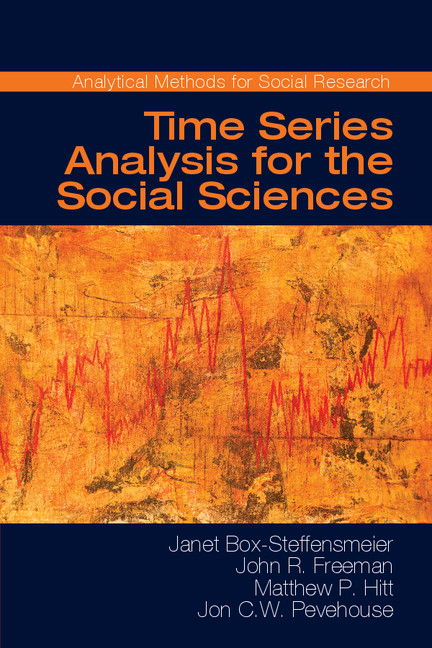
Time Series Analysis for the Social Sciences

-
Select format
-
- Publisher:
- Cambridge University Press
- Publication date:
- 05 December 2014
- 22 December 2014
- ISBN:
- 9781139025287
- 9780521871167
- 9780521691550
- Dimensions:
- (228 x 152 mm)
- Weight & Pages:
- 0.52kg, 292 Pages
- Dimensions:
- (228 x 152 mm)
- Weight & Pages:
- 0.39kg, 298 Pages
You may already have access via personal or institutional login
Show more authors 
You may already have access via personal or institutional login
Book description
Time series, or longitudinal, data are ubiquitous in the social sciences. Unfortunately, analysts often treat the time series properties of their data as a nuisance rather than a substantively meaningful dynamic process to be modeled and interpreted. Time Series Analysis for the Social Sciences provides accessible, up-to-date instruction and examples of the core methods in time series econometrics. Janet M. Box-Steffensmeier, John R. Freeman, Jon C. Pevehouse and Matthew P. Hitt cover a wide range of topics including ARIMA models, time series regression, unit-root diagnosis, vector autoregressive models, error-correction models, intervention models, fractional integration, ARCH models, structural breaks, and forecasting. This book is aimed at researchers and graduate students who have taken at least one course in multivariate regression. Examples are drawn from several areas of social science, including political behavior, elections, international conflict, criminology, and comparative political economy.
Contents
Contents
Metrics
Altmetric attention score
Full text views
Full text views helpTotal number of HTML views: 0
Total number of PDF views: 0 *
 Loading metrics...
* Views captured on Cambridge Core between #date#. This data will be updated every 24 hours.
Usage data cannot currently be displayed.
Accessibility standard: Unknown
Why this information is here
This section outlines the accessibility features of this content - including support for screen readers, full keyboard navigation and high-contrast display options. This may not be relevant for you.
Accessibility Information
Accessibility compliance for the PDF of this book is currently unknown and may be updated in the future.