




No CrossRef data available.
Article contents
Aggregated Markov processes with negative exponential time interval omission
Published online by Cambridge University Press: 01 July 2016
Abstract
We consider a time reversible, continuous time Markov chain on a finite state space. The state space is partitioned into two sets, termed open and closed, and it is only possible to observe whether the process is in an open or a closed state. Further, short sojourns in either the open or closed states fail to be detected. We consider the situation when the length of minimal detectable sojourns follows a negative exponential distribution with mean μ–1. We show that the probability density function of observed open sojourns takes the form 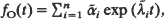 , where n is the size of the state space. We present a thorough asymptotic analysis of f O(t) as μ tends to infinity. We discuss the relevance of our results to the modelling of single channel records. We illustrate the theory with a numerical example.
Keywords
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Applied Probability Trust 1990
References
Ball, F. G. and Sansom, M. S. P. (1988a) Single-channel autocorrelation functions: the effects of time interval omission.
Biophys. J.
53, 819–832.CrossRefGoogle ScholarPubMed
Ball, F. G. and Sansom, M. S. P. (1988b) Aggregated Markov processes incorporating time interval omission.
Adv. Appl. Prob.
20, 546–572.CrossRefGoogle Scholar
Colquhoun, D. and Hawkes, A. G. (1977) Relaxation and fluctuations of membrane currents that flow through drug-operated channels.
Proc. R. Soc. Lond.
B 199, 231–262.Google ScholarPubMed
Colquhoun, D. and Hawkes, A. G. (1981) On the stochastic properties of single ion channels.
Proc. Roy. Soc. Lond.
B 211, 205–235.Google ScholarPubMed
Colquhoun, D. and Hawkes, A. G. (1987) A note on correlations in single ion channel records.
Proc. R. Soc. Lond.
B 230, 15–52.Google ScholarPubMed
Colquhoun, D. and Sigworth, F. (1983) Fitting and statistical analysis of single-channel records. In
Single-channel Recording
, ed. Sakmann, B. and Neher, E., Plenum Press, New York, 135–175.CrossRefGoogle Scholar
Dabrowski, A. R., Mcdonald, D. and Rösler, U. (1989) Renewal properties of ion channels. To appear.CrossRefGoogle Scholar
Forsyth, A. R. (1918)
Theory of Functions of a Complex Variable
, 3rd edn. Cambridge University Press.Google Scholar
Fredkin, D. R. and Rice, J. A. (1986) On aggregated Markov processes.
J. Appl. Prob.
23, 208–214.CrossRefGoogle Scholar
Fredkin, D. R., Montal, M. and Rice, J. A. (1985) Identification of aggregated Markovian models: application to the nicotinic acetylcholine receptor.
Proc. Berkeley Conf. in Honor of Jerzy Neyman and Jack Kiefer
1, ed. Le Cam, L. and Ohlsen, R., Wadworth, Belmont, CA, 269–290.Google Scholar
Kerry, C. J., Kits, K. S., Ramsey, R. L., Sansom, M. S. P. and Usherwood, P. N. R. (1987a) Single channel kinetics of a glutamate receptor.
Biophys. J.
51, 137–144.CrossRefGoogle ScholarPubMed
Kerry, C. J., Ramsey, R. L., Sansom, M. S. P. and Usherwood, P. N. R. (1987b) Glutamate receptor-channel kinetics: the effect of glutamate concentration.
Biophys. J.
53, 39–52.CrossRefGoogle Scholar
Kijima, S. and Kijima, H. (1987a) Statistical analysis of channel current from a membrane patch. I. Some stochastic properties of ion channels or molecular systems in equilibrium.
J. Theor. Biol.
128, 423–434.CrossRefGoogle ScholarPubMed
Kijima, S. and Kijima, H. (1987b) Statistical analysis of channel current from a membrane patch. II. A stochastic theory of the multi-channel system in the steady state.
J. Theor. Biol.
128, 435–455.CrossRefGoogle Scholar
Roux, B. and Sauve, R. (1985) A general solution to the time interval omission problem applied to single channel analysis.
Biophys. J.
48, 149–158.CrossRefGoogle Scholar
Yeo, G. F., Milne, R. K., Edeson, R. O. and Madsen, B. W. (1988) Statistical inference from single channel records: two-state Markov model with limited time resolution.
Proc. Roy. Soc. Lond.
B 235, 63–94.Google ScholarPubMed
Yeo, G. F., Milne, R. K., Edeson, R. O. and Madsen, B. W. (1989) Superposition properties of independent ion channels.
Proc. R. Soc. London
B 238, 155–170.Google ScholarPubMed
- 7
- Cited by