


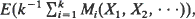 , where M
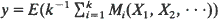 for some independent random variables X
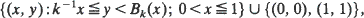 , where B
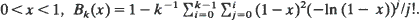 The result yields sharp, universal inequalities for independent random variables comparing two choice mechanisms, the mortal&s value of the game V(X
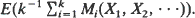 . Techniques of proof include probability- and convexity-based reductions; calculus-based, multivariate, extremal problem analysis; and limit theorems of Poisson-approximation type. Precise results are also given for finite sequences of independent random variables.

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Hill, Theodore P.
1987.
Expectation inequalities associated with prophet problems1.
Stochastic Analysis and Applications,
Vol. 5,
Issue. 3,
p.
299.
Kennedy, D.P.
1987.
Prophet-type inequalities for multi-choice optimal stopping.
Stochastic Processes and their Applications,
Vol. 24,
Issue. 1,
p.
77.
Kleinberg, Robert
and
Weinberg, Seth Matthew
2012.
Matroid prophet inequalities.
p.
123.
Osȩkowski, Adam
2015.
A prophet inequality for $$L^p$$ L p -bounded dependent random variables.
Positivity,
Vol. 19,
Issue. 2,
p.
289.
2019.
Kleinberg, Robert
and
Weinberg, S. Matthew
2019.
Matroid prophet inequalities and applications to multi-dimensional mechanism design.
Games and Economic Behavior,
Vol. 113,
Issue. ,
p.
97.
Gravin, Nikolai
and
Wang, Hongao
2019.
Prophet Inequality for Bipartite Matching.
p.
93.
Ezra, Tomer
Feldman, Michal
Gravin, Nick
and
Tang, Zhihao Gavin
2022.
Prophet Matching with General Arrivals.
Mathematics of Operations Research,
Vol. 47,
Issue. 2,
p.
878.
Gravin, Nick
and
Wang, Hongao
2023.
Prophet Inequality for Bipartite Matching: Merits of Being Simple and Nonadaptive.
Mathematics of Operations Research,
Vol. 48,
Issue. 1,
p.
38.
Ezra, Tomer
and
Garbuz, Tamar
2024.
Web and Internet Economics.
Vol. 14413,
Issue. ,
p.
256.
Ehsani, Soheil
Hajiaghayi, Mohammadtaghi
Kesselheim, Thomas
and
Singla, Sahil
2024.
Prophet Secretary for Combinatorial Auctions and Matroids.
SIAM Journal on Computing,
Vol. 53,
Issue. 6,
p.
1641.
Chen, Liyan
Ezra, Tomer
Feldman, Michal
Gravin, Nick
Sun, Nuozhou
and
Tang, Zhihao Gavin
2026.
Order-Competitive Ratio.
SIAM Journal on Computing,
Vol. 55,
Issue. 2,
p.
332.