


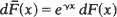 is a proper distribution with finite mean
 Various limit theorems for functionals of X
 For example, the deviation of the empirical distribution function from
 properly normalised, is shown to have a limit in D, and an approximation for
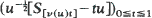 by means of Brownian bridge is derived. Similar results hold for risk reserve processes in the time up to ruin and the GI/G/1 queue considered either within a busy cycle or in the steady state. The methods produce an alternate approach to known asymptotic formulae for ruin probabilities as well as related waiting-time approximations for the GI/G/1 queue. For example
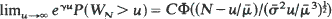 uniformly in N, with W

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Asmussen, S�ren
1981.
Equilibrium properties of the M/G/1 queue.
Zeitschrift f�r Wahrscheinlichkeitstheorie und Verwandte Gebiete,
Vol. 58,
Issue. 2,
p.
267.
Asmussen, Søren
1984.
Approximations for the probability of ruin within finite time.
Scandinavian Actuarial Journal,
Vol. 1984,
Issue. 1,
p.
31.
Asmussen, S⊘ren
1985.
Conjugate processes and the silumation of ruin problems.
Stochastic Processes and their Applications,
Vol. 20,
Issue. 2,
p.
213.
Asmussen, S⊘ren
and
Thorisson, Hermann
1988.
Large deviation results for time-dependent queue length distributions.
Communications in Statistics. Stochastic Models,
Vol. 4,
Issue. 1,
p.
99.
Anantharam, V.
1989.
How large delays build up in a GI/G/1 queue.
Queueing Systems,
Vol. 5,
Issue. 4,
p.
345.
Barndorff-Nielsen, O. E.
and
Cox, D. R.
1989.
Asymptotic Techniques for Use in Statistics.
p.
169.
Sadowsky, J.S.
1991.
Large deviations theory and efficient simulation of excessive backlogs in a GI/GI/m queue.
IEEE Transactions on Automatic Control,
Vol. 36,
Issue. 12,
p.
1383.
Karlin, Samuel
and
Brendel, Volker
1992.
Chance and Statistical Significance in Protein and DNA Sequence Analysis.
Science,
Vol. 257,
Issue. 5066,
p.
39.
Heidelberger, Philip
1993.
Performance Evaluation of Computer and Communication Systems.
Vol. 729,
Issue. ,
p.
165.
Fendick, Kerry W.
1993.
An asymptotically exact decomposition of coupled Brownian systems.
Journal of Applied Probability,
Vol. 30,
Issue. 4,
p.
819.
Dembo, Amir
and
Karlin, Samuel
1993.
Central limit theorems of partial sums for large segmental values.
Stochastic Processes and their Applications,
Vol. 45,
Issue. 2,
p.
259.
Stadje, Wolfgang
1994.
On the behavior of the batch arrival queueMx/M/1 during a busy period.
Naval Research Logistics,
Vol. 41,
Issue. 2,
p.
153.
Asmussen, Søren
Rubinstein, Reuven Y.
and
Wang, Chia-Li
1994.
Regenerative rare events simulation via likelihood ratios.
Journal of Applied Probability,
Vol. 31,
Issue. 3,
p.
797.
Malinovskii, Vsevolod K.
1994.
Corrected normal approximation for the probability of ruin within finite time.
Scandinavian Actuarial Journal,
Vol. 1994,
Issue. 2,
p.
161.
Heidelberger, Philip
1995.
Fast simulation of rare events in queueing and reliability models.
ACM Transactions on Modeling and Computer Simulation,
Vol. 5,
Issue. 1,
p.
43.
Glasserman, Paul
and
Kou, Shing-Gang
1995.
Analysis of an importance sampling estimator for tandem queues.
ACM Transactions on Modeling and Computer Simulation,
Vol. 5,
Issue. 1,
p.
22.
Puhalskii, A.
1995.
Large deviation analysis of the single server queue.
Queueing Systems,
Vol. 21,
Issue. 1-2,
p.
5.
Asmussen, Søren
and
Nielsen, Hanne Mandrup
1995.
Ruin probabilities via local adjustment coefficients.
Journal of Applied Probability,
Vol. 32,
Issue. 3,
p.
736.
Asmussen, Søren
and
Klüppelberg, Claudia
1996.
Large deviations results for subexponential tails, with applications to insurance risk.
Stochastic Processes and their Applications,
Vol. 64,
Issue. 1,
p.
103.
Asmussen, Søren
1996.
Stochastic Networks.
Vol. 117,
Issue. ,
p.
197.