




No CrossRef data available.
Article contents
Perpetuities with thin tails
Published online by Cambridge University Press: 01 July 2016
Abstract
We investigate the behaviour of P(R ≧ r) and P(R ≦ −r) as r → ∞for the random variable 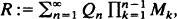 where
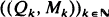 is an independent, identically distributed sequence with P(− 1 ≦ M ≦ 1) = 1. Random variables of this type appear in insurance mathematics, as solutions of stochastic difference equations, in the analysis of probabilistic algorithms and elsewhere. Exponential and Poissonian tail behaviour can arise.
Keywords
MSC classification
Information
- Type
- General Applied Probability
- Information
- Copyright
- Copyright © Applied Probability Trust 1996
Footnotes
∗
Present address: School of Mathematical Sciences, University of Sussex, Brighton, BN1 9QH, UK.
References
Bhattacharya, R. N. and Waymire, E. C. (1990) Stochastic Processes with Applications
Wiley-Interscience, New York.Google Scholar
De Bruijn, N. G. (1951) The asymptotic behaviour of a function occurring in the theory of primes. J. Indian Math. Soc.
15, 25–32.Google Scholar
Embrechts, P. and Goldie, C. M. (1994) Perpetuities and random equations. In Asymptotic Statistics: Proc. Fifth Prague Symp., September 1993. pp. 75–86. ed. Mandl, P. and Hušková, M.
Physica, Heidelberg.CrossRefGoogle Scholar
Goldie, C. M. (1991) Implicit renewal theory and tails of solutions of random equations. Ann. Appl. Prob.
1, 126–66.CrossRefGoogle Scholar
Grey, D. R. (1994) Regular variation in the tail behaviour of solutions of random difference equations. Ann. Appl. Prob.
4, 169–183.CrossRefGoogle Scholar
Grincevicius, A. K. (1975) One limit distribution for a random walk on the line. Lithuanian Math. J.
15, 580–589. (Engl. transl. of (1975) Litovsk. Mat. Sb. 15, 79-91.)
CrossRefGoogle Scholar
Grübel, R. and Rösler, U. (1996) Asymptotic distribution theory for Hoare's selection algorithm. Adv. Appl. Prob.
28, 252–269.CrossRefGoogle Scholar
Karlsen, H. A. (1990) Existence of moments in a stationary stochastic difference equation. Adv. Appl. Prob.
22, 129–146.CrossRefGoogle Scholar
Kesten, H. (1973) Random difference equations and renewal theory for products of random matrices. Acta Math.
131, 207–248.CrossRefGoogle Scholar
Ohkubo, H. (1979) On the asymptotic tail behaviors of infinitely divisible distributions. Yokohama Math. J.
27, 77–89.Google Scholar
Pötzelberger, K. (1990) A characterisation of random-coefficient AR(1) models. Stoch. Proc. Appl.
34, 171–180.Google Scholar
Sato, K. (1973) A note on infinitely divisible distributions and their Lévy measures. Sci. Rep. Tokyo Kyoiku Daigaku
A 12, 101–109.Google Scholar
Vervaat, W. (1977) Success Epochs in Bernoulli Trials (with Applications to Number Theory)
2nd edn.
Mathematisch Centrum, Amsterdam.Google Scholar
Vervaat, W. (1979) On a stochastic difference equation and a representation of non-negative infinitely divisible random variables. Adv. Appl. Prob.
11, 750–783.Google Scholar
- 73
- Cited by