




No CrossRef data available.
Article contents
Sojourns and extremes of a diffusion process on a fixed interval
Published online by Cambridge University Press: 01 July 2016
Abstract
Let X(t),  , be an Ito diffusion process on the real line. For u > 0 and t > 0, let Lt (u) be the Lebesgue measure of the set
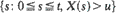 . Limit theorems are obtained for (i) the distribution of Lt (u) for u → ∞and fixed t, and (ii) the tail of the distribution of the random variable max[0, t]X(s). The conditions on the process are stated in terms of the drift and diffusion coefficients. These conditions imply the existence of a stationary distribution for the process.
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Applied Probability Trust 1982
References
[1]
Berman, S. M. (1970) Excursions above high levels for stationary Gaussian processes. Pacific J. Math.
36, 63–79.CrossRefGoogle Scholar
[2]
Berman, S. M. (1971) Maxima and high level excursions of stationary Gaussian processes. Trans. Amer. Math. Soc.
160, 65–85.CrossRefGoogle Scholar
[3]
Berman, S. M. (1972) A class of limiting distributions of high level excursions of Gaussian processes. Z. Wahrscheinlichkeitsth.
21, 121–134.CrossRefGoogle Scholar
[4]
Berman, S. M. (1972) Maximum and high level excursion of a Gaussian process with stationary increments. Ann. Math. Statist.
43, 1247–1266.CrossRefGoogle Scholar
[5]
Berman, S. M. (1973) Excursions of stationary Gaussian processes above high moving barriers. Ann. Prob.
1, 365–387.CrossRefGoogle Scholar
[6]
Berman, S. M. (1974) Sojourns and extremes of Gaussian processes. Ann. Prob.
2, 999–1026; Correction 8 (1980), 999.CrossRefGoogle Scholar
[7]
Berman, S. M. (1982) Sojourns and extremes of stationary processes. Ann. Prob.
10, 1–46.CrossRefGoogle Scholar
[8]
Doob, J. L. (1955) Martingales and one-dimensional diffusion. Trans. Amer. Math. Soc.
78, 168–208.CrossRefGoogle Scholar
[9]
De Haan, L. (1970) On Regular Variation and its Application to the Weak Convergence of Sample Extremes.
Mathematisch Centrum, Amsterdam.Google Scholar
[10]
Ito, K. and McKean, H. P. (1965) Diffusion Processes and their Sample Paths.
Springer-Verlag, New York.Google Scholar
[11]
Malmquist, S. (1954) On certain confidence contours for distribution functions. Ann. Math. Statist.
25, 523–533.CrossRefGoogle Scholar
[12]
Pickands, J. (1969) Upcrossing probabilities for stationary Gaussian processes. Trans. Amer. Math. Soc.
145, 75–86.Google Scholar
[13]
Skorokhod, A. V. (1965) Studies in the Theory of Random Processes.
Addison-Wesley, Reading, Ma.Google Scholar
[14]
Stroock, D. W. and Varadhan, S. R. S. (1979) Multidimensional Diffusion Processes.
Springer-Verlag, New York.Google Scholar
- 23
- Cited by