


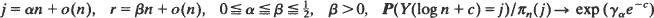 as n →∞, where π

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Voit, Michael
1996.
Asymptotic distributions for the Ehrenfest urn and related random walks.
Journal of Applied Probability,
Vol. 33,
Issue. 2,
p.
340.
Lloyd, Peter
Sudbury, Aidan
and
Donnelly, Peter
1996.
Quantum operators in classical probability theory: I. “Quantum spin” techniques and the exclusion model of diffusion.
Stochastic Processes and their Applications,
Vol. 61,
Issue. 2,
p.
205.
Donnelly, Peter
and
Rodrigues, Eliane R.
2000.
Convergence to stationarity in the Moran model.
Journal of Applied Probability,
Vol. 37,
Issue. 03,
p.
705.
Donnelly, Peter
and
Rodrigues, Eliane R.
2000.
Convergence to stationarity in the Moran model.
Journal of Applied Probability,
Vol. 37,
Issue. 3,
p.
705.
Seneta, E.
2001.
Characterization by orthogonal polynomial systems of finite Markov chains.
Journal of Applied Probability,
Vol. 38,
Issue. A,
p.
42.
HORA, Akihito
2004.
Asymptotic Spectral Analysis on the Johnson Graphs in Infinite Degree and Zero Temperature Limit.
Interdisciplinary Information Sciences,
Vol. 10,
Issue. 1,
p.
1.
Khare, Kshitij
and
Zhou, Hua
2009.
Rates of convergence of some multivariate Markov chains with polynomial eigenfunctions.
The Annals of Applied Probability,
Vol. 19,
Issue. 2,
Galligo, André
and
Miclo, Laurent
2012.
On the cut‐off phenomenon for the transitivity of randomly generated subgroups.
Random Structures & Algorithms,
Vol. 40,
Issue. 2,
p.
182.
Makmal, Adi
Tiersch, Markus
Ganahl, Clemens
and
Briegel, Hans J.
2016.
Quantum walks on embedded hypercubes: Nonsymmetric and nonlocal cases.
Physical Review A,
Vol. 93,
Issue. 2,
Eskenazis, Alexandros
and
Nestoridi, Evita
2020.
Cutoff for the Bernoulli–Laplace urn model with $o(n)$ swaps.
Annales de l'Institut Henri Poincaré, Probabilités et Statistiques,
Vol. 56,
Issue. 4,
Barbour, A.D.
Brightwell, Graham
and
Luczak, Malwina
2022.
Long-term concentration of measure and cut-off.
Stochastic Processes and their Applications,
Vol. 152,
Issue. ,
p.
378.
Alameda, Joseph S.
Bang, Caroline
Brennan, Zachary
Herzog, David P.
Kritschgau, Jürgen
and
Sprangel, Elizabeth
2024.
Cutoff in the Bernoulli-Laplace urn model with swaps of order n.
Electronic Communications in Probability,
Vol. 29,
Issue. none,
Olesker-Taylor, Sam
and
Schmid, Dominik
2026.
Limit profile for the Bernoulli–Laplace urn via diffusions.
The Annals of Applied Probability,
Vol. 36,
Issue. 3,