




No CrossRef data available.
Article contents
Arret optimal avec contrainte
Published online by Cambridge University Press: 01 July 2016
Abstract
Given two optional positive bounded processes Y and Y′, defined on a probability space  , and a non-negative real a, the problem is to maximize the average reward E(YT ) among all the stopping times T verifying the following constraint:
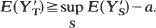 The problem is solved by Lagrangian saddlepoint techniques in the set of randomized stopping times including the set of stopping times.
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Applied Probability Trust 1983
References
Bibliographie
[1]
Bensoussan, A.
Et Lions, J. L. (1978) Applications des inéquations variationnelles en contrôle stochastique.
Dunod, Paris.Google Scholar
[2]
Bismut, J. M. (1974) An example of optimal control with constraints. SIAM J. Control
12, 401–418.Google Scholar
[3]
Bismut, J. M. (1978) Régularité et continuité des processus. Z. Wahrscheinlichkeitsth.
44, 261–268.Google Scholar
[4]
Bismut, J. M. (1979) Temps d'arrêt optimal, quasi-temps d'arrêt et retournement du temps. Ann. Prob.
7, 933–964.Google Scholar
[5]
Bismut, J. M. and Skalli, B. (1977) Temps d'arrêt optimal, théorie générale des processus et processus de Markov. Z. Wahrscheinlichkeitsth.
47, 301–313.Google Scholar
[6]
Christopeit, N. (1978) A stochastic control model with chance constraints. SIAM J. Control Optimization
16, 702–714.Google Scholar
[7]
Dellacherie, C. (1972) Capacités et processus stochastiques.
Springer-Verlag, Berlin.Google Scholar
[8]
Dellacherie, C.
Et Meyer, P. A. (1975), (1980)
Probabilités et potentiels, Tomes 1 et 2. Hermann, Paris.Google Scholar
[9]
Ekeland, I.
Et Teman, R. (1976) Convex Analysis and Variational Problems.
North-Holland, Amsterdam.Google Scholar
[10]
El Karoui, N. (1981) Les aspects probabilistes du contrôle stochastique. Ecole d'été de St-Flour IX, 1979, Lecture Notes in Mathematics 876, Springer-Verlag, Berlin.Google Scholar
[11]
Frid, E. B. (1972) On optimal strategies in control problems with constraints. Theory Prob. Appl.
17, 188–192.Google Scholar
[12]
Haussmann, U. G. (1981) Some examples of optimal stochastic controls or: the stochastic maximum principle at work. SIAM Rev.
23, 292–307.Google Scholar
[13]
Kennedy, D. P. (1982) On a constrained optimal stopping problem. J. Appl. Prob.
19, 631–642.Google Scholar
[14]
KusHner, H. J. (1965) On the stochastic maximum principle with average constraints. J. Math. Anal. Appl.
12, 13–26.Google Scholar
[15]
Mertens, J. F. (1972) Théorie des processus stochastiques généraux. Applications aux surmartingales. Z. Wahrscheinlichkeitsth.
22, 45–68.Google Scholar
[17]
Ozgoren, M. K., Longman, R. W.
Et Cooper, C. A. (1978) Probabilistic inequality constraints in stochastic optimal control theory. J. Math. Anal. Appl.
66, 237–259.Google Scholar
[18]
Quadrat, J. P. (1980) Existence de solution et algorithme de résolution numérique de problème de contrôle optimal de diffusion stochastique dégénérée ou non. SIAM J. Control Optimization
18, 199–266.Google Scholar
[19]
Robin, ?. (1978) Contrôle impulsionnel de processus de Markov. Thèse, Université Paris IX.Google Scholar
[20]
Robin, M. (1979) On optimal stochastic control problems with constraints. In Game Theory and Related Topics, North-Holland, Amsterdam, 187–202.Google Scholar
[21]
Rockafellar, R. T. (1970) Convex Analysis.
Princeton University Press, Princeton, NJ.Google Scholar
[22]
Shiryayev, A. N. (1977) Optimal Stopping Rules.
Applications of Mathematics 8, Springer-Verlag, Berlin.Google Scholar
- 5
- Cited by