
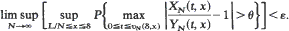

Hostname: page-component-7b7567c8c-z4zkx Total loading time: 0 Render date: 2026-11-17T00:55:31.971Z Has data issue: false hasContentIssue false

The behavior of the ratio of a small-noise Markov chain to its deterministic approximation

Published online by Cambridge University Press:  01 July 2016

Norman Kaplan*
Affiliation:
National Institute of Environmental Health Sciences
Thomas Darden*
Affiliation:
National Institute of Environmental Health Sciences
*
∗Postal address: Biometry and Risk Assessment Program, National Institute of Environmental Health Sciences, Research Triangle Park, NC 27709, USA.

Abstract

For each N≧1, let {XN(t, x), t≧0} be a discrete-time stochastic process with XN (0) = x. Let FN (y) = E(XN (t + 1) | XN (t) = y), and define YN (t, x) = FN(YN(t – 1, x)), t≧1 and YN (0, x) = x. Assume that in a neighborhood of the origin FN (y) = mNy(l + O(y)) where mN > 1, and define for δ> 0 and x> 0, υN (δ, x) = inf{t:xmtN >δ}. Conditions are given under which, for θ> 0 and ε> 0, there exist constants δ > 0 and L <∞, depending on εand 0, such that This result together with a result of Kurtz (1970), (1971) shows that, under appropriate conditions, the time needed for the stochastic process {XN (t, 1/N), t≧0} to escape a δ -neighborhood of the origin is of order log Νδ /log mN . To illustrate the results the Wright-Fisher model with selection is considered.

Information

Type
Research Article
Copyright
Copyright © Applied Probability Trust 1985 

Access options

Get access to the full version of this content by using one of the access options below. (Log in options will check for institutional or personal access. Content may require purchase if you do not have access.)

Article purchase

Temporarily unavailable