


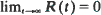 and R″ cannot be chosen monotone. Contrary to a finding by Beneš [1] it is proven that
 if and only if the service-times have a finite fourth moment.

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Ott, Teunis J.
1977.
The stable M/G/1 queue in heavy traffic and its covariance function.
Advances in Applied Probability,
Vol. 9,
Issue. 1,
p.
169.
Ott, Teunis J.
1977.
The stable M/G/1 queue in heavy traffic and its covariance function.
Advances in Applied Probability,
Vol. 9,
Issue. 1,
p.
169.
Ott, Teunis J.
1979.
Some more results for the stable M/G/1 queue in heavy traffic.
Journal of Applied Probability,
Vol. 16,
Issue. 1,
p.
187.
Heffes, H.
1980.
A Class of Data Traffic Processes-Covariance Function Characterization and Related Queuing Results.
Bell System Technical Journal,
Vol. 59,
Issue. 6,
p.
897.
Matsuda, Jun
1984.
An approximation for the auto‐covariance function of the virtual waiting time in an M/G/1 and its applications.
Electronics and Communications in Japan (Part I: Communications),
Vol. 67,
Issue. 6,
p.
72.
Ott, Teunis J.
1984.
On the M/G/1 queue by additional inputs.
Journal of Applied Probability,
Vol. 21,
Issue. 1,
p.
129.
Cox, D. R.
and
Isham, Valerie
1986.
The virtual waiting-time and related processes.
Advances in Applied Probability,
Vol. 18,
Issue. 2,
p.
558.
Abate, Joseph
and
Whitt, Ward
1988.
Transient behavior of theM/M/1 queue via Laplace transforms.
Advances in Applied Probability,
Vol. 20,
Issue. 1,
p.
145.
Abate, Joseph
and
Whitt, Ward
1988.
The correlation functions of rbm and m/m/1.
Communications in Statistics. Stochastic Models,
Vol. 4,
Issue. 2,
p.
315.
Abate, Joseph
and
Whitt, Ward
1988.
Transient behavior of theM/M/1 queue via Laplace transforms.
Advances in Applied Probability,
Vol. 20,
Issue. 1,
p.
145.
Stanford, D. A.
and
Pagurek, B.
1992.
On the serial correlation for number in system in the stationary GI/M/1 bulk arrival and GI/Em
/1 queues.
Journal of Applied Probability,
Vol. 29,
Issue. 02,
p.
404.
Toyoizumi, Hiroshi
1992.
Evaluating mean sojourn time estimates for the M/M/1 queue.
Computers & Mathematics with Applications,
Vol. 24,
Issue. 1-2,
p.
7.
Abate, Joseph
and
Whitt, Ward
1992.
Solving probability transform functional equations for numerical inversion.
Operations Research Letters,
Vol. 12,
Issue. 5,
p.
275.
Kella, Offer
1992.
Concavity and reflected Lévy processes.
Journal of Applied Probability,
Vol. 29,
Issue. 1,
p.
209.
Toyoizumi, H.
1993.
A simple method of estimating mean delay by counting arrivals and departures.
p.
829.
Borovkov, A. A.
Boxma, O. J.
and
Palmowski, Z.
2003.
On the integral of the workload process of the single server queue.
Journal of Applied Probability,
Vol. 40,
Issue. 1,
p.
200.
Hansen, M.B.
2005.
Nonparametric Estimation of the Stationary M/G/1 Workload Distribution Function.
p.
869.
Es-Saghouani, Abdelghafour
and
Mandjes, Michel
2008.
On the Correlation Structure of a Lévy-Driven Queue.
Journal of Applied Probability,
Vol. 45,
Issue. 4,
p.
940.
Andersen, Lars Nørvang
and
Mandjes, Michel
2009.
Structural properties of reflected Lévy processes.
Queueing Systems,
Vol. 63,
Issue. 1-4,
p.
301.
Glynn, Peter W.
and
Mandjes, Michel
2009.
Simulation-based computation of the workload correlation function in a levy-driven queue.
p.
1155.