




No CrossRef data available.
Article contents
Multivariate hazard rates and stochastic ordering
Published online by Cambridge University Press: 01 July 2016
Abstract
Properties of the conditional hazard rates of X 1, · ··, Xn and Y 1, · ··, Yn, which imply (X 1, · ··, Xn ) 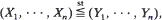 (Y 1, · ··, Yn ), are found. These are used to find conditions on the hazard rates of T = (T 1, · ··, Tn ) which ensure that T has the MIHR |
 property of Arjas (1981a) and the ‘weakened by failure’ property of Arjas and Norros (1984). Applications for load-sharing model and multivariate imperfect repair are given.
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Applied Probability Trust 1987
Footnotes
Supported by the Air Force Office of Scientific Research, USAF, under Grant AFOSR-84-0205. Reproduction in whole or in part is permitted for any purpose of the United States government.
References
Arjas, E. (1981a) A stochastic process approach to multivariate reliability: notions based on conditional stochastic order.
Math. Operat. Res.
6, 263–276.Google Scholar
Arjas, E. (1981b) The failure and hazard processes in multivariate reliability systems.
Math. Operat. Res.
6, 551–562.CrossRefGoogle Scholar
Arjas, E. and Norros, I. (1984) Life lengths and association: a dynamic approach.
Math. Operat. Res.
9, 151–158.CrossRefGoogle Scholar
Block, H. W., Borges, W. S. and Savits, T. H. (1985) Age dependent minimal repair.
J. Appl. Prob.
22, 370–385.CrossRefGoogle Scholar
Brown, M. and Proschan, F. (1983) Imperfect repair.
J. Appl. Prob.
20, 851–859.CrossRefGoogle Scholar
Cox, D. R. (1972) Regression models and life tables (with discussion).
J. R. Statist. Soc.
B 34, 187–220.Google Scholar
Cox, D. R. and Lewis, P. A. W. (1972) Multivariate point processes.
Proc. 6th Berkeley Symp. Math. Statist. Prob.
3, 401–488.Google Scholar
Esary, J. D. and Marshall, A. W. (1970) Coherent life functions.
SIAM J. Appl. Math.
18, 810–814.CrossRefGoogle Scholar
Esary, J. D., Proschan, F. and Walkup, D. W. (1967) Association of random variables, with applications.
Ann. Math. Statist.
38, 1466–1474.CrossRefGoogle Scholar
Freund, J. E. (1961) A bivariate extension of the exponential distribution.
J. Amer. Statist. Assoc.
56, 971–977.CrossRefGoogle Scholar
Kopocinska, I. and Kopocinski, B. (1980) On system reliability under random load of elements. Zastos Mat.
XVII, 5–13.Google Scholar
Marshall, A. W. and Shaked, M. (1986) Multivariate new better than used distributions.
Math. Oper. Res.
11, 110–116.CrossRefGoogle Scholar
Norros, I. (1984) A compensator representation of multivariate lifelengths distributions, with applications. Scand. J. Statist.
To appear.Google Scholar
Ross, S. M. (1984) a model in which component failure rates depend on the working set.
Naval Res. Log. Quart.
31, 297–301.CrossRefGoogle Scholar
Schechner, Z. (1984) A load-sharing model: the linear breakdown rule.
Naval Res. Log. Quart.
31, 137–144.Google Scholar
Shaked, M. and Shanthikumar, J. G. (1984) Multivariate hazard rates and stochastic ordering. Technical report, Department of Mathematics, University of Arizona.Google Scholar
Shaked, M. and Shanthikumar, J. G. (1986) Multivariate imperfect repair. Operat. Res.
To appear.CrossRefGoogle Scholar
- 31
- Cited by