


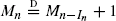 for n = 2, 3, …, where I


Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Gnedin, Alexander
Iksanov, Alex
and
Möhle, Martin
2008.
On Asymptotics of Exchangeable Coalescents with Multiple Collisions.
Journal of Applied Probability,
Vol. 45,
Issue. 4,
p.
1186.
Freund, F.
and
Möhle, M.
2009.
On the number of allelic types for samples taken from exchangeable coalescents with mutation.
Advances in Applied Probability,
Vol. 41,
Issue. 4,
p.
1082.
Gnedin, Alexander V.
Iksanov, Alexander M.
Negadajlov, Pavlo
and
Rösler, Uwe
2009.
The Bernoulli sieve revisited.
The Annals of Applied Probability,
Vol. 19,
Issue. 4,
p.
1634.
Iksanov, Alex
Marynych, Alex
and
Möhle, Martin
2009.
On the number of collisions in beta $(2, b)$-coalescents.
Bernoulli,
Vol. 15,
Issue. 3,
p.
829.
Gnedin, Alexander
Iksanov, Alexander
and
Marynych, Alexander
2011.
On Λ-Coalescents with Dust Component.
Journal of Applied Probability,
Vol. 48,
Issue. 4,
p.
1133.
Haas, Bénédicte
and
Miermont, Grégory
2011.
Self-similar scaling limits of non-increasing Markov chains.
Bernoulli,
Vol. 17,
Issue. 4,
p.
1217.
Iksanov, Alexander
2013.
On the number of empty boxes in the Bernoulli sieve I.
Stochastics,
Vol. 85,
Issue. 6,
p.
946.
Abraham, Romain
and
Delmas, Jean-François
2013.
A Construction of a β-Coalescent via the Pruning of Binary Trees.
Journal of Applied Probability,
Vol. 50,
Issue. 3,
p.
772.
Huillet, Thierry
and
Möhle, Martin
2013.
On the extended Moran model and its relation to coalescents with multiple collisions.
Theoretical Population Biology,
Vol. 87,
Issue. ,
p.
5.
Kersting, Götz
Schweinsberg, Jason
and
Wakolbinger, Anton
2014.
The evolving beta coalescent.
Electronic Journal of Probability,
Vol. 19,
Issue. none,
p.
1.
Marynych, Alexander
and
Verovkin, Glib
2014.
Weak convergence of the number of zero increments in the random walk with barrier.
Electronic Communications in Probability,
Vol. 19,
Issue. none,
p.
1.
Gnedin, Alexander
Iksanov, Alexander
Marynych, Alexander
and
Möhle, Martin
2014.
On Asymptotics of the Beta Coalescents.
Advances in Applied Probability,
Vol. 46,
Issue. 2,
p.
496.
Gnedin, Alexander
Iksanov, Alexander
and
Marynych, Alexander
2014.
Λ-coalescents: a survey.
Journal of Applied Probability,
Vol. 51,
Issue. A,
p.
23.
Gnedin, Alexander
Iksanov, Alexander
and
Marynych, Alexander
2014.
Λ-coalescents: a survey.
Journal of Applied Probability,
Vol. 51,
Issue. A,
p.
23.
Haas, Bénédicte
and
Stephenson, Robin
2018.
Bivariate Markov chains converging to Lamperti transform Markov additive processes.
Stochastic Processes and their Applications,
Vol. 128,
Issue. 10,
p.
3558.
Gnedin, Alexander
Iksanov, Alexander
Marynych, Alexander
and
Möhle, Martin
2018.
The collision spectrum of $\Lambda$-coalescents.
The Annals of Applied Probability,
Vol. 28,
Issue. 6,
p.
3857.
Kołodziejek, Bartosz
2018.
On perpetuities with light tails.
Advances in Applied Probability,
Vol. 50,
Issue. 4,
p.
1119.
2021.
Bohun, V.
and
Marynych, A.
2021.
On the local time of a recurrent random walk on ℤ².
Theory of Probability and Mathematical Statistics,
Vol. 105,
Issue. 0,
p.
69.
Haas, Bénédicte
2025.
Séminaire de Probabilités LII.
Vol. 2363,
Issue. ,
p.
389.