




No CrossRef data available.
Article contents
Optimal selection of stochastic intervals under a sum constraint
Published online by Cambridge University Press: 01 July 2016
Abstract
We model a selection process arising in certain storage problems. A sequence (X 1, · ··, Xn ) of non-negative, independent and identically distributed random variables is given. F(x) denotes the common distribution of the Xi′s. With F(x) given we seek a decision rule for selecting a maximum number of the Xi′s subject to the following constraints: (1) the sum of the elements selected must not exceed a given constant c > 0, and (2) the Xi′s must be inspected in strict sequence with the decision to accept or reject an element being final at the time it is inspected.
We prove first that there exists such a rule of threshold type, i.e. the ith element inspected is accepted if and only if it is no larger than a threshold which depends only on i and the sum of the elements already accepted. Next, we prove that if F(x) ~ Axα as x → 0 for some A, α> 0, then for fixed c the expected number, En (c), selected by an optimal threshold is characterized by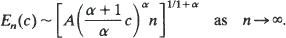 Asymptotics as c → ∞and n → ∞with c/n held fixed are derived, and connections with several closely related, well-known problems are brought out and discussed.
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Applied Probability Trust 1987
References
1. Bennett, G. (1962) Probability inequalities for the sum of independent random variables.
J. Amer. Statist. Assoc.
57, 33–45.Google Scholar
2. Bruno, J. L. and Downey, P. J. (1986) Probabilistic bounds for dual bin-packing.
Acta Informatica.
Google Scholar
3. Campbell, G. and Samuels, S. M. (1981) Choosing the best of the current crop.
Adv. Appl. Prob.
15, 510–532.Google Scholar
4. Chen, R. W., Nair, V. N., Odlyzko, A. M., Shepp, L. A. and Vardi, Y. (1984) Optimal sequential selection of N random variables under a constraint.
J. Appl. Prob.
21, 537–547.Google Scholar
5. Chernoff, H. (1952) A measure of asymptotic efficiency for tests of a hypothesis based on the sum of observations.
Ann. Math. Statist.
23, 493–507.Google Scholar
6. Gilbert, J. and Mosteller, F. (1966) Recognizing the maximum of a sequence.
J. Amer. Statist. Assoc.
61, 35–73.Google Scholar
7. Glick, N. (1978) Breaking records and breaking boards.
Amer. Math. Monthly
85, 2–26.Google Scholar
8. Hoeffding, W. (1963) Probability inequalities for sums of bounded random variables.
J. Amer. Statist. Assoc.
58, (1963), 13–29.Google Scholar
9. Logan, B. F. and Shepp, L. A. (1977) A variational problem for random Young tableaux.
Adv. Math.
26, 206–222.Google Scholar
10. Mallows, C. L., Nair, V. N., Shepp, L. A. and Vardi, Y. (1985) Optimal sequential selection of optical fibers and secretaries.
Math. Operat. Res.
10, 709–715.CrossRefGoogle Scholar
11. Samuels, S. M. and Steele, J. M. (1981) Optimal sequential selection of a monotone sequence from a random sample.
Ann. Prob.
9, 937–947.CrossRefGoogle Scholar
- 24
- Cited by