




No CrossRef data available.
Article contents
Poisson and extreme value limit theorems for Markov random fields
Published online by Cambridge University Press: 01 July 2016
Abstract
Let Xt ,  be a Markov random field assuming values in RM. Let In be a rectangular box in Zm with its center at 0 and corner points with coordinates ±n. Let (An ) be a sequence of measurable subsets of RM such that
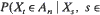 neighborhood of t) → 0, for n → ∞; and let fn (x) be the indicator of An. Under appropriate conditions on the nearest-neighbor distributions of (Xt ), the conditional distribution of
 given the values of Xs , for s on the boundary of In , converges to the Poisson distribution. An immediate application is an extreme value limit theorem for a real-valued Markov random field.
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Applied Probability Trust 1987
Footnotes
This paper represents results obtained at the Courant Institute of Mathematical Sciences, New York University, under the sponsorship of the U.S. Army Research Office, Grant number DAAG-29-85-K-0146, and the National Science Foundation, Grant DMS 85 01512.
References
1. Bartlett, M. S. (1975) The Statistical Analysis of Spatial Pattern. Chapman and Hall, London.Google Scholar
2. Berman, S. M. (1964) Limit theorems for the maximum term in stationary sequences.
Ann. Math. Statist.
35, 502–516.CrossRefGoogle Scholar
3. Berman, S. M. (1984) Limiting distribution of sums of non-negative stationary random variables.
Ann. Inst. Statist. Math.
36, 301–321.Google Scholar
4. Besag, J. (1974) Spatial interaction and the statistical analysis of lattice systems. J. R. Statist. Soc.
B36, 192–236.Google Scholar
5. Chay, S. C. (1972) On quasi-Markov random fields.
J. Multivariate Anal.
2, 14–76.CrossRefGoogle Scholar
6. Dobrushin, R. L. (1968) The description of a random field by means of conditional probabilities and conditions of its regularity.
Theory Prob. Appl.
13, 197–224.CrossRefGoogle Scholar
7. Dobrushin, R. L. (1970) Prescribing a system of random variables by conditional distributions.
Theory Prob. Appl.
15, 458–486.CrossRefGoogle Scholar
8. Dobrushin, R. L. and Sinai, Ya. G., (Ed) (1980) Multicomponent Random Systems. Marcel Dekker, New York.Google Scholar
9. Galambos, J. (1978) The Asymptotic Theory of Extreme Order Statistics. Wiley, New York.Google Scholar
10. Gnedenko, B. V. (1943) Sur la distribution limite du terme maximum d&une série aléatoire.
Ann. Math.
44, 423–453.CrossRefGoogle Scholar
11. Grimmett, G. R. (1973) A theorem about random fields.
Bull. London Math. Soc.
5, 81–84.Google Scholar
12. De Haan, L. (1970) On Regular Variation and its Application to the Weak Convergence of Sample Extremes. Mathematical Centre Tracts 32, Amsterdam.Google Scholar
13. Kindermann, R. and Snell, J. L. (1980) Markov Random Fields and their Applications. Vol. 1 of Contemporary Mathematics, American Math. Soc., Providence
1980.CrossRefGoogle Scholar
14. Leadbetter, M. R., Lindgren, G., and Rootzen, H. (1983) Extremes and Related Properties of Random Sequences and Processes. Springer-Verlag, New York.CrossRefGoogle Scholar
15. Loève, M. (1978) Probability Theory, Fourth Edition
Vol. II, Springer-Verlag, New York.Google Scholar
16. Nahapetian, B. S. (1980) The central limit theorem for random fields with mixing property, In Multicomponent Random Systems, Ed. Dobrushin, R. L. and Sinai, YA. G.
Marcel Dekker, New York. 531–547.Google Scholar
18. Rozanov, Yu. A. (1967) On Gaussian fields with given conditional distributions.
Theory Prob. Appl.
12, 381–391.Google Scholar
19. Scheffé, H. (1947) A useful convergence theorem for probability distributions.
Ann. Math. Statist.
18, 434–438.CrossRefGoogle Scholar
- 3
- Cited by