




No CrossRef data available.
Article contents
Stochastic fm models and non-linear time series analysis
Published online by Cambridge University Press: 01 July 2016
Abstract
An important model in communications is the stochastic FM signal st = A cos 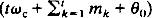 , where the message process {m t} is a stochastic process. In this paper, we investigate the linear models and limit distributions of FM signals. Firstly, we show that this non-linear model in the frequency domain can be converted to an ARMA (2, q + 1) model in the time domain when {mt } is a Gaussian MA (q) sequence. The spectral density of {St } can then be solved easily for MA message processes. Also, an error bound is given for an ARMA approximation for more general message processes. Secondly, we show that {St } is asymptotically strictly stationary if {mt } is a Markov chain satisfying a certain condition on its transition kernel. Also, we find the limit distribution of st for some message processes {mt }. These results show that a joint method of probability theory, linear and non-linear time series analysis can yield fruitful results. They also have significance for FM modulation and demodulation in communications.
Keywords
MSC classification
Information
- Type
- General Applied Probability
- Information
- Copyright
- Copyright © Probability Trust 1997
References
[1]
Chan, K. S. and Tong, H. (1985) On the use of the deterministic Lyapunov function for the ergodicity of stochastic difference equations. Adv. Appl. Prob.
17, 666–678.CrossRefGoogle Scholar
[2]
Doob, J. L. (1944) The elementary Gaussian processes. Ann. Math. Statist.
15, 229–282.CrossRefGoogle Scholar
[3]
Feller, W. (1971) An Introduction to Probability Theory and its Applications.
2nd edn.
Wiley, New York.Google Scholar
[4]
Gardner, W. A. (1987) Introduction to Random Processes with Applications to Signals and Systems.
2nd edn.
McGraw-Hill, New York.Google Scholar
[5]
Gladyshev, E. G. (1961) Periodically correlated random sequences. Sov. Math.
2, 385–388.Google Scholar
[6]
Huang, D. and Spencer, N. M. (1996) On a random vibration model. J. Appl. Prob.
33, 1141–1158.CrossRefGoogle Scholar
[7]
Hurd, H. L. and Leskow, J. (1992) Estimation of the Fourier coefficient functions and their spectral densities for ϕ-mixing almost periodically correlated processes. Statist. Prob. Lett.
14, 299–306.CrossRefGoogle Scholar
[8]
Middleton, D. (1987) An Introduction to Statistical Communication Theory.
McGraw-Hill, New York.Google Scholar
[10]
Tam, P. K. S. and Moore, J. B. (1977) A Gaussian sum approach to phase and frequency estimation. IEEE Trans. Commun.
25, 935–942.CrossRefGoogle Scholar
[11]
Taub, H. and Schilling, D. L. (1986) Principles of Communication Systems.
2nd edn.
McGraw-Hill, New York.Google Scholar
[12]
Tjostheim, D. (1990) Non-linear time series and Markov chains. Adv. Appl. Prob.
22, 587–611.CrossRefGoogle Scholar
[13]
Tweedie, R. L. (1975) Sufficient conditions for ergodicity and recurrence of Markov chains on a general state space. Stoch. Proc. Appl.
3, 385–403.CrossRefGoogle Scholar
[14]
Tweedie, R. L. (1988) Invariant measures for Markov chains with no irreducibility assumptions. J. Appl. Prob.
25A, 275–285.CrossRefGoogle Scholar