


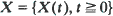 be a process with stationary, independent increments and no negative jumps. Let
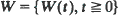 be this same process modified by a reflecting barrier at zero (a storage process). Assuming that –
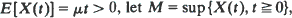 and denote by ψ(s) the exponent function of X. A simple formula is derived for the Laplace transform of
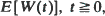 as a function of W(0). Using the fact that the distribution of M is the unique stationary distribution of the Markov process W, this yields an elementary proof that the Laplace transform of M is µs/ψ(s). If
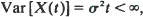 it follows that
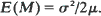 These surprisingly simple formulas were originally obtained by Zolotarev using analytical methods.

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Fendick, K.W.
and
Whitt, W.
1989.
Measurements and approximations to describe the offered traffic and predict the average workload in a single-server queue.
Proceedings of the IEEE,
Vol. 77,
Issue. 1,
p.
171.
Kella, Offer
and
Whitt, Ward
1990.
Diffusion approximations for queues with server vacations.
Advances in Applied Probability,
Vol. 22,
Issue. 3,
p.
706.
Gallot, S. F. L.
1993.
Absorption and first-passage times for a compound Poisson process in a general upper boundary.
Journal of Applied Probability,
Vol. 30,
Issue. 4,
p.
835.
Pakes, Anthony G.
1996.
A hitting time for Lévy processes, with application to dams and branching processes.
Annales de la Faculté des sciences de Toulouse : Mathématiques,
Vol. 5,
Issue. 3,
p.
521.
Harrison, J. Michael
1998.
Heavy traffic analysis of a system with parallel servers: asymptotic optimality of discrete-review policies.
The Annals of Applied Probability,
Vol. 8,
Issue. 3,
Konstantopoulos, Takis
and
Lin, Si-Jian
1998.
Macroscopic models for long-range dependent network traffic.
Queueing Systems,
Vol. 28,
Issue. 1-3,
p.
215.
Chen, H.
1999.
Basic adjoint relation for transient and stationary analysis of some Markovprocesses.
Annals of Operations Research,
Vol. 87,
Issue. 0,
p.
273.
Tsoukatos, Konstantinos P.
and
Makowski, Armand M.
2000.
Heavy traffic limits associated with >M/G/∞ input processes.
Queueing Systems,
Vol. 34,
Issue. 1-4,
p.
101.
Asmussen, Søren
and
Kella, Offer
2001.
On optional stopping of some exponential martingales for Lévy processes with or without reflection.
Stochastic Processes and their Applications,
Vol. 91,
Issue. 1,
p.
47.
Konstantopoulos, Takis
and
Richardson, Gregory S.
2002.
Conditional limit theorems for spectrally positive Lévy processes.
Advances in Applied Probability,
Vol. 34,
Issue. 1,
p.
158.
Konstantopoulos, Takis
Last, Günter
and
Lin, Si-Jian
2004.
On a Class of Lévy Stochastic Networks.
Queueing Systems,
Vol. 46,
Issue. 3-4,
p.
409.
Kella, Offer
2007.
Encyclopedia of Statistics in Quality and Reliability.
2008.
Stochastic Processes for Insurance & Finance.
p.
617.
Lewis, Alan L.
and
Mordecki, Ernesto
2008.
Wiener-Hopf Factorization for Lévy Processes Having Positive Jumps with Rational Transforms.
Journal of Applied Probability,
Vol. 45,
Issue. 1,
p.
118.
Czystołowski, M.
and
Szczotka, W.
2010.
Queueing approximation of suprema of spectrally positive Lévy process.
Queueing Systems,
Vol. 64,
Issue. 4,
p.
305.
Kella, Offer
2012.
The Class of Distributions Associated with the Generalized Pollaczek-Khinchine Formula.
Journal of Applied Probability,
Vol. 49,
Issue. 3,
p.
883.
M. Asghari, Naser
Iseger, Peter
and
Mandjes, Michael
2012.
Numerical Techniques in Lévy Fluctuation Theory.
Methodology and Computing in Applied Probability,
Kella, Offer
2012.
The Class of Distributions Associated with the Generalized Pollaczek-Khinchine Formula.
Journal of Applied Probability,
Vol. 49,
Issue. 3,
p.
883.
Kella, Offer
2014.
Wiley StatsRef: Statistics Reference Online.
Michna, Zbigniew
Palmowski, Zbigniew
and
Pistorius, Martijn
2015.
The distribution of the supremum for spectrally asymmetric Lévy
processes.
Electronic Communications in Probability,
Vol. 20,
Issue. none,