


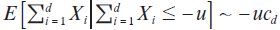 . Moreover we study diversification effects in two dimensions, similar to our Value-at-Risk studies in [2].


Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Alink, Stan
Löwe, Matthias
and
Wüthrich, Mario V.
2007.
Diversification for general copula dependence.
Statistica Neerlandica,
Vol. 61,
Issue. 4,
p.
446.
Asmussen, Søren
and
Rojas-Nandayapa, Leonardo
2008.
Asymptotics of sums of lognormal random variables with Gaussian copula.
Statistics & Probability Letters,
Vol. 78,
Issue. 16,
p.
2709.
Biard, Romain
Lefèvre, Claude
and
Loisel, Stéphane
2008.
Impact of correlation crises in risk theory: Asymptotics of finite-time ruin probabilities for heavy-tailed claim amounts when some independence and stationarity assumptions are relaxed.
Insurance: Mathematics and Economics,
Vol. 43,
Issue. 3,
p.
412.
Charpentier, Arthur
and
Segers, Johan
2009.
Tails of multivariate Archimedean copulas.
Journal of Multivariate Analysis,
Vol. 100,
Issue. 7,
p.
1521.
He, Xubiao
and
Gong, Pu
2009.
Measuring the coupled risks: A copula-based CVaR model.
Journal of Computational and Applied Mathematics,
Vol. 223,
Issue. 2,
p.
1066.
2010.
Furman, Edward
and
Landsman, Zinoviy
2010.
Multivariate Tweedie distributions and some related capital-at-risk analyses.
Insurance: Mathematics and Economics,
Vol. 46,
Issue. 2,
p.
351.
Asimit, Alexandru V.
and
Badescu, Andrei L.
2010.
Extremes on the discounted aggregate claims in a time dependent risk model.
Scandinavian Actuarial Journal,
Vol. 2010,
Issue. 2,
p.
93.
Biard, Romain
Lefèvre, Claude
Loisel, Stéphane
and
Nagaraja, Haikady N.
2011.
Asymptotic finite‐time ruin probabilities for a class of path‐dependent heavy‐tailed claim amounts using Poisson spacings.
Applied Stochastic Models in Business and Industry,
Vol. 27,
Issue. 5,
p.
503.
Hua, Lei
and
Joe, Harry
2011.
Second order regular variation and conditional tail expectation of multiple risks.
Insurance: Mathematics and Economics,
Vol. 49,
Issue. 3,
p.
537.
Asimit, Alexandru V.
Furman, Edward
Tang, Qihe
and
Vernic, Raluca
2011.
Asymptotics for risk capital allocations based on Conditional Tail Expectation.
Insurance: Mathematics and Economics,
Vol. 49,
Issue. 3,
p.
310.
Joe, Harry
and
Li, Haijun
2011.
Tail Risk of Multivariate Regular Variation.
Methodology and Computing in Applied Probability,
Vol. 13,
Issue. 4,
p.
671.
Chen, Die
Mao, Tiantian
Pan, Xiaoqing
and
Hu, Taizhong
2012.
Extreme value behavior of aggregate dependent risks.
Insurance: Mathematics and Economics,
Vol. 50,
Issue. 1,
p.
99.
Mainik, Georg
and
Rüschendorf, Ludger
2012.
Ordering of multivariate risk models with respect to extreme portfolio losses.
Statistics & Risk Modeling,
Vol. 29,
Issue. 1,
p.
73.
Fougeres, Anne-Laure
and
Mercadier, Cecile
2012.
Risk Measures and Multivariate Extensions of Breiman's Theorem.
Journal of Applied Probability,
Vol. 49,
Issue. 2,
p.
364.
Tong, Bin
Wu, Chongfeng
and
Xu, Weidong
2012.
Risk concentration of aggregated dependent risks: The second-order properties.
Insurance: Mathematics and Economics,
Vol. 50,
Issue. 1,
p.
139.
Li, Haijun
and
Wu, Peiling
2013.
Extremal dependence of copulas: A tail density approach.
Journal of Multivariate Analysis,
Vol. 114,
Issue. ,
p.
99.
Rüschendorf, Ludger
2013.
Mathematical Risk Analysis.
p.
353.
2014.
2015.