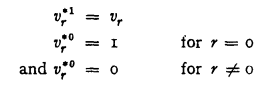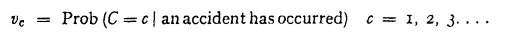
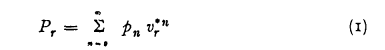
Hostname: page-component-7b7567c8c-w7t8q Total loading time: 0 Render date: 2026-11-18T15:34:29.023Z Has data issue: false hasContentIssue false

Cumulants of Convolution—Mixed Distributions

Published online by Cambridge University Press:  29 August 2014

Rights & Permissions [Opens in a new window]

Extract

Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.

Consider a risk process which is characterised by three stochastic variables

(1) the number of accidents, N,

(2) the number of claims per accident, C, and

(3) the amount of a claim, X.

Let Y be a random variable denoting the total loss in a given period.

Suppose that

and

If Pr represents the probability that exactly r claims occur in the period, then Kupper [4] has shown on certain simplifying assumptions that

where , the probability of exactly r claims in n accidents, is given by
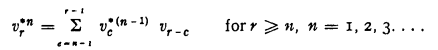
and for γ < n

Further

Information

Type
Research Article
Copyright
Copyright © International Actuarial Association 1977