
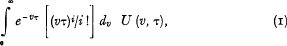
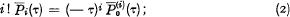
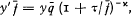
Hostname: page-component-7b7567c8c-w7t8q Total loading time: 0 Render date: 2026-11-18T18:25:25.940Z Has data issue: false hasContentIssue false

On the Numerical Calculation of the Distribution Functions Defining Some Compound Poisson Processes*

Published online by Cambridge University Press:  29 August 2014

Carl Philipson*
Affiliation:
Stockholm, Sweden
Rights & Permissions [Opens in a new window]

Extract

Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.

1. The comfound Poisson process in the wide sense is defined as a process for which the probability distribution of the number i of changes in the random function attached to the process, while the parameter passes from o to a fixed value τ of the parameter measured on a suitable scale, is given by the Laplace-Stieltjes integral

where U(ν, τ) for a fixed value of τ defines the distribution of ν. U(ν, τ) is called the risk distribution and is either τ-independent or, dependent on ν, τ.

2. The compound Poisson process in the narrow sense is defined as a process for which the probability distribution of the number of changes can be written in the form of (I) with a τ-independent risk distribution.

In their general form these processes have been analyzed by Ove Lundberg (1940). For such processes the following relation holds for the probability of i changes in the interval ο to τ, P̅i (τ) say

this relation does not hold for processes with τ-dependent risk distribution. Hofmann (1955) has introduced a sub-set of the processes concerned in this section for which the probability for non-occurrence of a change in the interval o to τ is defined as a solution of the differential equation

and ϰ ≥ o; the solutions may be written in the form where η is independent of and of two alternative forms one for ϰ = I and one for other values of ϰ. The probabilities for i changes in the interval o to τ in the processes defined by the solutions of Hofmann's equation are derived by Leibniz's formula, and are designated by and, in this paper, called Hofmann probabilities.

Information

Type
Papers
Copyright
Copyright © International Actuarial Association 1963
