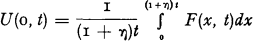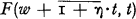
Hostname: page-component-7b7567c8c-7pwfn Total loading time: 0 Render date: 2026-11-17T09:49:18.895Z Has data issue: false hasContentIssue false

Ruin Probability During A Finite Time Interval

Published online by Cambridge University Press:  29 August 2014

R. E. Beard*
Affiliation:
University of Essex
Rights & Permissions [Opens in a new window]

Extract

Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.

This paper was inspired by comments by H. L. Seal in a series of lectures given to the Actuaries Club in New York and by a paper of his recently published in the Swiss Actuarial Journal (Seal, 1972 [6]). In his lectures he showed that the probability U(w, t) that a risk reserve at every epoch τ, where o < τ ≤ t will be non negative when the initial risk reserve is w is related to , the probability that the aggregate claim outgo through epoch t does not exceed by the relationship
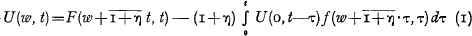
where η is the security loading and f(x, t) = (∂/∂x) F(x, t).

It is assumed that the d.f. F(x, t) is differentiable eith regard to x with a possible exception at the point x = o.

Using an extension of the “ballot theorem” in Chapter III of Feller (1968 [4]) he showed that and observed that if numerical values of F(x, t) were available values of U(w, t) could be computed.

Information

Type
Research Article
Copyright
Copyright © International Actuarial Association 1975