1. Introduction
1.1 Our research into individual asset liability management has been guided by the aspiration to develop a practical solution which supports all kinds of individual decisions in a household's financial planning throughout its life and, particularly, to help with retirement planning. Our initial difficulty in formulating the household consumption investment problem has not been theoretical but behavioural. As many others have noted previously, the major questions we needed to address are the following.
1.2 What is the objective of a life-long financial plan? As Samuel Brittan said “We do not prosper by income or happiness alone” [Financial Times, September 3, 2009].
What is the meaning of wealth for a long-term investor? “Can we measure our wealth as the value of our portfolio? Hardly. Today, $1 million buys much less than it did 25 years ago. Is wealth defined by the real value of our portfolio? Only if we plan to spend it all right away. Is wealth the long-term spending that our portfolio can sustain – the annuity that our assets could procure? This definition is closer to the truth, but like the first, it ignores purchasing power. Is wealth, then, the inflation-indexed real income that our assets could sustain over time?” (Arnott, Reference Arnott2006).
1.3 In framing the life-cycle consumption investment problem we assert two principles:
– individual wealth is measured by sustainable spending over a household's life time
– individual risk attitude at any point in time is a reflection of existing and foreseen liabilities together with a subjective view of desirable personal future consumption.
1.4 Recognition of the enormous complexity of this task – creating an individual life- cycle financial plan under the uncertainties of market and life events – dictates a dynamic solution which is appropriate to changing individual behaviour and circumstances and which permits a ‘what if’ analysis of alternative scenarios. Daniel Kahneman wrote that both utility theory and its behavioural alternatives may be too narrow for the purpose of wealth management. “These theories are exclusively concerned with the moment of decision, not with the moment of truth when consequences are experienced. They tacitly assume that individuals correctly anticipate their reactions to possible outcomes and incorporate valid emotional predictions into their investment decisions. In fact, people are poor forecasters of their future emotions and future tastes – they need help in this task – and I believe that one of the responsibilities of financial advisors should be to provide that help.” (Kahneman, Reference Kahneman2009).
1.5 In this paper we propose a new theory for, and describe a prototype of, a decision support system for financial advisors or individual households. Our implementation has been designed in such a way that its interactive use (similar to playing computer games) allows the user to assess the consequences of optimisation decisions. Therefore, by changing discretionary data and re-solving the problem, an individual household can identify the most appropriate set of their preferences and life goals which match their foreseen income and liabilities at minimal risk.
1.6 Financial planning depends on the national jurisdiction of the household, which dictates taxation, health system, pension provision, mortgages and so on. Although complex, conceptually these particulars are ‘rule based’. We model only the major elements of US and UK taxation and pension regulations. In the mathematical formulation the taxation and pension scheme details are written as constraints in the corresponding sub-model of the overall optimisation problemFootnote 1.
1.7 This paper is organised as follows. In the next section we discuss briefly the ‘divide’ between academics and practitioners in their approach to long-term savings and investment and provide a short review of methods used for wealth management or financial planning. Section 3 describes the principal modules and logical structure of our solution, the individual asset liability management (iALM) meta-model. The essentials of the problem – objective function, constraints, scenario generation and so on are discussed conceptually in this section and more technical details are given in an appendix. Section 4 is devoted to UK household data – the origins of public data and further elaboration on the enrichment of household profiles. iALM concepts and the design structure for household inputs and the corresponding recommended solutions are given there. Sensitivity to changes in market returns data in terms of performance through the 2007–09 crisis, is also discussed. We summarise our findings in the conclusion, where we make some recommendations regarding the use by individuals or financial advisor professionals of systems such as iALM for life-cycle financial planning.
2. Theory vs. Practice
2.1 Paul Samuelson was the first to recognise the importance of personal finance. In 1948, Samuelson (1948) wrote a chapter on this topic in his elementary textbook, Economics: An Introductory Analysis. He was also the first to propose the use of dynamic programming to solve the long-term investment problem in ‘Lifetime Portfolio Selection by Dynamic Stochastic Programming’, Samuelson (Reference Samuelson1969). A review of the academic literature devoted to life-cycle theory would be an enormous taskFootnote 2 since it includes both empirical studies of actual household consumption, saving and investment behaviour and stochastic control type asset allocation models. Campbell & Viceira's (Reference Campbell and Viceira2002) book gives the most insightful exposition of the analytical class of models stemming from Merton (1969). Recent related studies combine the effects of demographics, uncertainty in incomes, specification of preferences and other variables on the problem solution (Carrol, Reference Carrol2000; Attanasio et al., Reference Attanasio, Bank, Meghir and Weber1999).
2.2 Ironically, financial advisors mostly ignore academic solutions and many use rules-of-thumb for investment decisions. One such popular rule links risk attitude to the age of investors: the equity fraction of one's portfolio equals 100 minus one's age Footnote 3. Advances in behavioural finance help to evaluate such rules (see, e.g. Barber & Odean, Reference Barber and Odean2005) but they have not yet delivered a practical solution. So far, attempts to reconcile theory and practice have been a failure to such an extent that Paul Samuelson started his keynote address at a conference on life-cycle investment (see Bodie, Reference Bodie2007, and Bodie et al., Reference Bodie, Treussard and Willen2007a, Reference Bodie, McLeavy and Siegelb) with the question ‘Is personal finance an exact science?’ with the immediate answer ‘flat no’. In his words, “It is a domain full of ordinary common sense. Alas, common sense is not the same thing as good sense. Good sense in these esoteric puzzles is hard to come by.” Samuelson (Reference Samuelson2007).
2.3 Current best practice of leading financial advisors and private wealth managers is to employ static Markowitz mean-variance portfolio allocations based on current market views, while projecting future portfolio returns from the optimal allocation using Monte Carlo analysis to calculate the probabilities of achieving various goals. Similar portfolio allocations are applied to separate portfolios for each investment goal such as retirement, children's private education, etc. A number of software tools utilising this approach are now available for individual household use with PCs or over the internet, but they all require the adoption of an ‘attitude to risk’ which is an obstacle to both individuals and their advisors. More importantly, in spite of investor demand (OECD, 2009), no joined up view of a household's financial requirements in terms of income, asset and liability cash flows is given. Hoevenaars et al. (Reference Hoevenaars, Molenar, Schotman and Steenkamp2009) and Amenc et al. (Reference Amenc, Martinelli, Milhau and Ziemann2009) try to take account of forward household liabilities by applying the best practice approach described above to a funding ratio variable, but even in the institutional pension fund setting from which it comes, this is best handled by explicit cash flow matching (Dempster et al., Reference Dempster, Germano, Medova, Murphy and Sandrini2009). See also Wilcox & Fabozzi (Reference Wilcox and Fabozzi2009) which attempts to account for the present value of individual liabilities in a best practice Markowitz approach.
2.4 The scientific difficulty undermining decision support for life-time financial planning is the necessity of employing a tractable technology for the optimisation of complex stochastic dynamic systems which is capable of coping with a myriad of practical details over very long investment horizons. Broadly speaking, the choice of technologies is three-fold: Monte Carlo simulation (termed dynamic financial analysis or DFA by actuaries), discrete or continuous dynamic programming and dynamic stochastic programming. The major drawback of the dynamic Monte Carlo approach is that models must be optimized ‘by hand’ by stepping through the decision variables of interest, while the dynamic programming approaches suffer from what their inventor, Richard Bellman, termed the ‘curse of dimensionality’. In practice dynamic programming methods over long-term horizons are computationally limited to the consideration of three or four stochastic factors such as asset class returns or cash liabilitiesFootnote 4. Only dynamic stochastic programming (DSP) – a technology built on fifty years of practical experience with mathematical optimisation techniques – has the ability to combine handling the practical details with rapidly optimizing the model sizes necessary for individual life-cycle financial planning.Footnote 5
2.5 The first application of the DSP approach was the Home Account system of Berger & Mulvey (Reference Berger and Mulvey1998) which used an aggregate goal target and approximate solution techniques involving annual decision rules over about 20 year horizons. More recently, Consiglio et al. (2004) and Consigli (Reference Consigli2007) describe personal financial planning systems which maximise utility of terminal wealth over fairly short horizons subject to deviation from a household-specified annual wealth target. Geyer et al. (Reference Geyer, Hanke and Weissensteiner2009) present results for a DSP version of the classical consumption investment model which only involves a two risky and one riskless asset portfolio with annual decisions over a short horizon, together with a long horizon analytical continuation (Richard, Reference Richard1975) which takes account of household mortality risks. None of these models treat household finances at the annual cashflow level, nor the practical details of mortgages, taxes, pensions, insurance, etc., considered in this paper.
3. Dynamic Model for Individual Asset Liability Management
3.1 This paper describes a meta-model based on the principles of dynamic stochastic programming. It is implemented in the form of a decision support tool, which allows interactive use with successive modification of individual preferences and data inputs as required. Therefore, as a solution there is not one financial plan offered to a household for consideration, but rather many contingency plans reflecting their subjective opinions regarding future life events.
3.2 The name of the meta-model and the corresponding system – individual asset liability management (iALM) – indicates that the modelling methodology came from the operations research topic decision making under uncertainty. In the system developed we brought together the principal ideas from behavioural finance, classical finance and stochastic optimisation theory to help individuals with long term financial planning decisions.
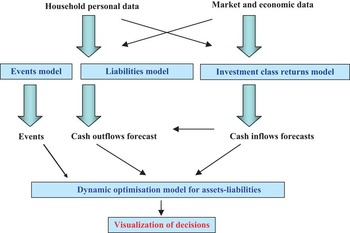
3.3 Formally, our household financial planning problem is a dynamic multistage stochastic optimisation problem in discrete time. A summary of dynamic stochastic optimisation principles, together with the basic mathematical structure of the stochastic optimisation problem, are given in the appendix. The iALM meta-model consists of many individual sub-models with the logical structure shown in figure 1. The process of generation of the problem instance and its solution is comprised of three stages: forward simulation of stochastic data processes, solution of the stochastic optimisation problem and analysis of the optimal decisions. Figure 1 thus illustrates how different models and processes in iALM are linked to form a stochastic optimisation problem.
Basic structure of the iALM meta-model

3.4 The interactive use of the system starts at Stage 3 when a ‘user’ either accepts the current financial plan generated or wants to explore alternatives. The latter is effected by changing his/her preferences expressed in personal data using a graphical user interface (GUI) to obtain modified plans, until suitable recommendations are found (for illustrative examples, see Medova et al. Reference Medova, Murphy, Owen and Rehman2008).
3.5 A new paradigm – a move from the static solution of a single problem to an interactive process for the identification of the solution most suitable to the user – is achieved. This makes use of an innovative scenario generator and DSP modelling language, and an automatic problem generator, respectively the Stochastic Generator (StochGen) and the Generalised Stochastic Programming Language (GSPL) DSP modelling language which are components of STOCHASTICS TM. Therefore the first task is to simulate stochastic asset returns and liabilities to support the full cashflow modelling in iALM. Appropriate to such a dynamic stochastic programming model, scenarios for these entities must be simulated in the form of a scenario tree so that major forward portfolio rebalances face alternative asset/liability scenarios (see figure A.1).
3.1. Scenario generation
We treat asset returns, events and liabilities in turn.
Asset return and inflation simulation
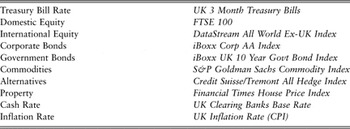
3.1.1 For parsimony, it is necessary to select specific asset classes to represent the risk and return characteristics of the myriad individual securities and funds suitable for household portfolios. The chosen asset classes should cover the range of possible investments and be meaningful to households and their financial advisors in order to allow asset allocation recommendations from iALM to be mapped to actual instruments. The asset classes selected for UK investors are shown in Table 1 together with the indices representing them.
Selected UK asset classes and associated indices

3.1.2 In more detail, UK 3 Month Treasury Bills (Treasury Bills) are low-risk investments used to represent building society accounts, bank deposit accounts, web saver accounts, business deposit accounts and emergency funds. The FTSE 100 (Domestic Equity) is a share index of the 100 most highly capitalised companies listed on the London Stock Exchange which together represent about 80% of total market capitalisation. The domestic equity asset class represents UK equities, company stock options, equity funds, index tracking unit trusts, index funds, exchange traded funds, investment trusts and passive investment funds. The DataStream All World Ex-UK Index (International Equity) is an equity index used to represent equity investment instruments outside the UK which provides exposure to high growth, high risk international markets such as India, China and South America. There are also US and European equities in this index which to some extent moderates its risk/return profile. The iBoxx Corp AA Index (Corporate Bonds) is constructed from AA investment grade UK corporate bonds. As well as representing an investable asset class, the corporate bond index is important for modelling pension growth and annuity rates. The iBoxx UK 10 Year Govt Bond Index (Government Bonds) is an index of bonds issued by the UK government. The S&P Goldmann Sachs Commodity Index (Commodities) is a composite index of commodity sector returns representing unleveraged, long-only investment in commodity futures across a large range of commodities. The Credit Suisse/Tremont All Hedge Index (Alternatives) is an asset-weighted hedge fund index whose constituents are rebalanced semi-annually. The investment instruments represented by this asset class include hedge funds, funds of funds, growth funds, mutual funds, open ended investment trusts and unit trusts. The Financial Times House Price Index (Property) is calculated monthly based on about 120,000 monthly actual residential property transactions, making it an almost complete sample of the market. It is used to represent buy-to-let and residential property funds. The UK Clearing Banks Base Rate (Cash Rate) is the rate set by the Bank of England as a floor for the money markets. The cash rate is used as a base rate for interest on various types of borrowing, for which fixed spreads above this rate can be individually specified.
3.1.3 Ten year time periods of monthly historical data were used to calibrate the simulators of the chosen asset classes for UK iALMFootnote 6. The period June 1998 to May 2008 exhibited relatively stable economic conditions in the UK. Inflation remained between 1% and 4% and the Bank of England base rate stayed between 4% and 6% for much of the period. Hedge fund, commodity and property indices grew over the period. The events of 11th September 2001, in conjunction with the ‘bursting’ of the high-tech equity bubble, saw domestic and international equity returns suffer after a previously long run of impressive growth. All the asset classes affected in 2001 had comfortably recovered by 2006 prior to the sub-prime mortgage induced credit crisis of 2007–09. The crisis effects were generally not significantly felt until after May 2008 and, in particular, after the Lehman's bankruptcy in September 2008.
3.1.4 The indices used for commodity, hedge fund and property indices are total return. Government bond and corporate bond indices are price only, and separate historical data is used for coupon rates for these bonds. Domestic and international equity indices are treated as price only; for this purpose dividends for equity classes are modelled at 3.5% for domestic equity and 3.0% for international equity as estimated by the Financial Times Online (2008). The UK Consumer Prices Index (CPI) is used to generate the basic inflation rate, but different fixed rate adjustments specific to various liability inflation rates, such as private schooling costs, may be specified.
3.1.5 The types of stochastic processes suitable for the simulation of the asset classes used in iALM are geometric Brownian motion, the Ornstein-Uhlenbeck process and the geometric Ornstein-Uhlenbeck process.
3.1.6 Geometric Brownian motion (GBM) satisfies the stochastic differential equation (SDE)Footnote 7

where μ is the drift, σ is the volatility and W is the underlying standard Brownian motion, with Wt having mean 0 and volatility t.
Consider the process log X, where log denotes the natural logarithm. Using Ito's lemma, this process is a Brownian motion which satisfies the SDE given by

where  . In order to model (2) discretely, we assume the time series increment Δ (Δ := 1/12 implies monthly data) and consider the series
 . The resulting discrete time process satisfies

where Wt−Wt −1 is a standard normal random variable independent of those for previous and future time increments.
3.1.7 An Ornstein-Uhlenbeck (OU) process C satisfies the SDE

where β is the rate of mean-reversion,  is the long term mean, σ is the volatility and W is a standard Brownian motion.
The geometric Ornstein-Uhlenbeck (GOU) process satisfies the SDE

where the parameters and W are as for (4).
The logarithm,  , of such a process is an OU process which satisfies the SDE

where  .
The solution of this SDE is given by

which is discretely modelled recursively as

with time series increment Δ and ε2, ε3, …, εT independent identically distributed N(0, σ 2) random variables. The process r will be mean reverting if β > 0.
3.1.8 GBM is widely used in financial modelling of this nature at monthly frequency and was selected to simulate indices for domestic equity, international equity, corporate bonds, government bonds, commodities, alternatives and property. An initial indication of the suitability of GBM for this set of asset classes was provided by graphical inspection of the historical data indices and statistical verification of normality using a Kolmogorov-Smirnov test of empirical return distributions for normality which showed monthly returns acceptably normal at below the 20% significance level. A Jarque-Berra test for normality, based on skewness and kurtosis, confirmed these results.
3.1.9 The mean reversion properties of a GOU process (whose log is an OU process), make it suitable for the simulation of the cash and inflation rates, corporate and government bond coupons and the treasury bill rate. A graphical overview of the historical data for these asset classes provides an indication that they possess mean reverting characteristics. In the case of inflation rate, cash rate and treasury bill rate, these mean reverting characteristics are a direct result of UK government and Bank of England policy. To confirm the suitability of the GOU assignments, statistical verification was performed for these asset classes using the augmented Dickey Fuller unit root test for stationarity of an OU process on logs of the original data. Mean reversion was accepted in all cases at well below the 20% significance level. For this purpose the OU process in log data is discretely modelled as (8).
3.1.10 The indices listed in Table 1 provide monthly historical time series data for ten year periods from June 1997 to May 2009. All data were obtained from Thomson Data Stream. From each of the three sets of ten year data for each asset class the following parameters were estimated to pass to the simulator:
– Drifts μ for GBM processes
– Parameters α, β for OU and GOU processes
– Covariance matrix V between all processes.
Using the historical time series, data algorithms implemented in Octave were employed to obtain the simulator parameters for each asset class from maximum likelihood estimates of the discretized process regression models.
3.1.11 Finally to estimate a contemporary covariance matrix between the returns of each asset class a quasi-maximum likelihood approach was used, i.e., covariances are estimated using the residuals from each process regression. For GBM processes these residuals are from (3)

and for OU/GOU from (8)

Covariances between OU/GOU and GBM processes, respectively process a and b say, so obtained must be corrected by dividing each element by estimates of the factor  , which tends to Δ when both betas tend to zero, i.e. when both a and b processes become GBM in the limit.
3.1.12 These models’ parameter calibrations would benefit from longer time series. In cases, as here, when data history for some asset classes is short, annual recalibration is desirable. In general, more complex models which can cope with extreme market conditions may be used for the forward simulation of asset returns, but again parsimonious parameterization is desirable.
3.1.13 It is important to note that while the GBM, OU and GOU processes are simulated using the Multi GBM simulator of STOCHASTICS™ with a monthly time step, the iALM household financial plan is generated in terms of forward annual cash flows with forward optimal recommendations for annual portfolio rebalances.
Event simulation
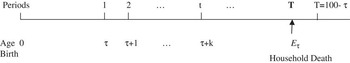
3.1.14 The heads of a household consist of at least one of (H1) and (H2) persons. In their life the major random events are: death (D) and serious illness requiring long-term care (LTC). In the situation where a health service is provided by the state, LTC may not be consideredFootnote 8. Life scenarios and asset return scenarios follow an identical tree structure and use a common seed for simulation. Each individual's life expectancy Eτ at age τ and the probability of dying q(τ) during the year (t, t+1) given survival to age τ can be obtained from life tablesFootnote 9.
To generate events on a single future scenario the probability of dying in year t (i.e. before the end of year t) is given by

where p(s) is the probability of survival to age τ given by p(s): =1−q(s).
3.1.15 The event simulator effectively generates a stream of successive annual binary events: alive-1, dead-0, with probabilities of dying in each sequential year computed recursively by conditioning (independently for both H1 and H2). For persons who have attained age τ the remaining length of life on a scenario is therefore the number of 1's in the event scenario binary string generated. We use T1 and T2 to denote the remaining lifespan of the two independent random death events and define the household's lifespan to be T : = max {T1, T2}, see figure 2. The maximum length of life is achieved at the horizon T which equals 100 years minus the starting age of the youngest head of household.
Event time line

3.1.16 The fact that heads of households can die means that it is possible (and indeed likely, depending on the life tables used by the simulator) that both heads of household will be dead before the end of a particular scenario. In this event there is no longer any optimisation problem to solve on that scenario and thus no need to consider the variables or constraints at points beyond the last death of a household on a given scenario. This is an advantage, since by eliminating these variables and constraints considerable computational effort can be saved and the time taken to produce a solution reduced.
3.1.17 For most institutional DSP problems a horizon that is the same on all scenarios is suitable. However in iALM, since the time of the last death is different on different scenarios, the horizon should ideally vary from one scenario to the next. This is a potentially tricky problem, but an elegant solution to it has been devised. In order to achieve this variable effective horizon (i.e. a problem horizon that can differ from one scenario to another), both sides of all constraints in iALM are multiplied by an indicator that takes the value 1 in all years up until the year immediately after the last death of a head of household; thereafter, it takes the value 0. This has the effect of reducing constraints after the last death to 0 ≤ 0 or 0 = 0, both of which are trivially satisfied. A similar idea is used to ensure that variables at times beyond household lifetime are not included in the objective function.
3.1.18 These trivial constraints and objective function terms contain no variables and impose no conditions on the solution after the last death of a head of household on a particular scenario. This allows the GSPL DSP modelling language preprocessor to remove them during the preparation of the problem for solution. Removal of these variables (of which there may be a very large number) makes the problem to be solved smaller and simpler than would be the case without the variable horizon, allowing it to be computed more quickly. In the case of portfolios, however, when sibling scenarios still have a living household, variables on scenarios from the last rebalance date are maintained to ensure that no spurious arbitrages are possible and the portfolio drawdown risk constraint remains active.
3.1.19 In this model we do not consider employment redundancy, partly due to the difficulties in obtaining statistical data for simulation. In a situation when the risk of redundancy exists, a household needs to reassess all its personal circumstances. In such situations, a specific version of the financial plan without labour income for a specified number of years (judged individually) may be generated for the household's consideration.
Liability simulator
3.1.20 Liabilities run for a certain number of years (tdet) unless a household death event occurs before hand. Therefore all liabilities run up to ten d :=min {tdet, T}.
Although existing loan and mortgage repayment liabilities are fixed in currency value at inception, in general liabilities are indexed for inflation and all forward individual liabilities may have an additional fixed per annum growth rate as

i.e.

3.1.21 In the liability simulator (which again uses the same tree structure and seed as the other simulators), two sets of liabilities are simulated: those indexed by the inflation rate – calculated in the asset return simulator – and those unindexed by inflation but possibly subject to an extra deterministic growth rate. In the simulator all liabilities in each of the two classes in a given year t are added to generate respectively the  (unindexed) sum of liabilities and the
 (inflation indexed) sum of liabilities, so that total liabilities become

where

is the current inflation index at year t in terms of the annual (mean reverting) inflation rate process  (i.e. r1: = 0). This simplification introduces the error of using

for  which may be corrected on average by the map
 , where
 is the average annual inflation rate (e.g. 3%), to give an error term
 of small magnitude with expectation 0.
3.2. Optimisation
3.2.1 As we stated in the introduction, conceptually the formulation of the objective for optimisation presents the most challenging problem for the modeller, which we overcame by adopting some critical ideas from behavioural finance. Recall the Kahneman & Riepe (Reference Kahneman and Riepe1998) notions of framing: “it is always possible to frame the same decision problem in broader terms (such as wealth) or in narrower terms (such as gains and losses); for the same decision problem broad and narrow frames often lead to different preferences. Rationality is best served by adopting broad frames rather than concentrating on changes.” The graph in figure 3 shows the form of the prospect theory value function proposed by Kahneman & Tversky (Reference Kahneman and Tversky1979). The inflection point is the reference point which is often equal to the status quo (e.g. the current state of wealth) or may correspond to an outcome that the individual has reason to expect.
Value function based on empirical results of Kahneman and Tversky

3.2.2 For its optimisation objective our formulation of the iALM problem uses the notion of the value function and combines the two types of framing:
– Narrow framing with respect to the ability to achieve the desired/acceptable spending level on any specific goal, e.g. specified annual living cost in any particular future year. This translates into the objective of maximising the real goal spending within the range of minimum, acceptable and desirable values. We thus introduce three reference points defined as minimum (e.g. the poverty line for living cost), acceptable and desirable amounts which are individually defined by the household.
– Broad framing with respect to the satisfaction gained from accumulating wealth over a life time while providing for all consumption and liabilities at minimal risk. We see wealth as generating ‘sustainable spending’. The primary goal of iALM is thus ‘to increase the real spending that a portfolio can sustain’ (Arnott, Reference Arnott2006, p.11). Formally, this translates into the objective of maximising the real spending on all goals which the financial portfolio(s) can sustain throughout the household's lifetime.
Objective
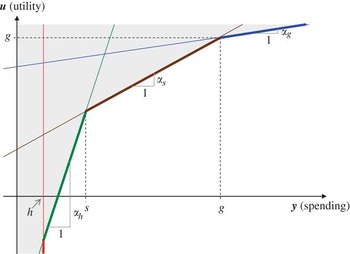
3.2.3 The utility function for each individual goal is a piece-wise linear function (see figure 4), which is constructed for a range of spending between acceptable (s) and desirable (g) values, subject to existing and foreseen liabilities, and a minimum required spending (h). The slope of the (s, g) section can be thought of as the goal's priority. In years when multiple goals are present this has the effect of directing spending to goals with higher marginal utilities of consumptionFootnote 10.
Value/utility function for an individual household goal

3.2.4 It is important to note here that these goal utility functions are constructed using the individual household input data across life scenarios at multiple times. Thus the shape of individual utility functions in each year defines the household's attitude to risk in that year, resulting in a time-varying forward attitude to risk appropriate to goals and life circumstances.
3.2.5 The overall objective of the iALM optimisation (in today's value terms) is to maximise the expected utility of lifetime consumption Footnote 11, taking into account total tax payments and excess borrowing, i.e.

where

Here  is an indicator function to handle random length of life scenarios,
ut is the utility in year t,
yg,t is spending on goal g in year t,
G is the set of all goals with ug,t being the utility for a specific goal g in year t,
 is the inflation index in year t,
 is excess borrowing – an auxiliary variable introduced for dealing with possible bankruptcy (or short-term emergency borrowing),
 is the total tax payable,
with π xs and π τi being the respective penalty coefficients on bankruptcy and tax.
3.2.6 Consumption Ct is defined as spending on chosen goals in year t. Spending will grow with a goal specific inflation rate  and is distributed between equity (preserving) goals, like real estate, and non-capital goalsFootnote 12. Thus

where the subset of goals Gm is the set of real estate goals, which may be mortgaged. Such goals with purchase price  require a down payment
 at
 in the first year of the goal and an annual mortgage payment
 thereafterFootnote 13. Other non-capital goals have no equity value but have spending
 on goal
 at time t.
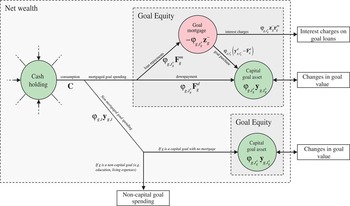
3.2.7 Wealth is generated through optimum portfolio allocation (in addition to other income streams like salaries and other individually specified payments). Net goal wealth consists of cash holdings (liquid wealth) and the value of equity in goals, e.g. equity in real estate, see figure 5. For example, home equity in any year is purchase price scaled up by inflation less the present value of future mortgage payments.
Goal spending cash flow diagram

Constraints
3.2.8 Objectives for investment are dependent on many factors, like personal priorities, aspirations, human capital, family status and so on. In this context, iALM may be interpreted as performing constrained optimum resource allocation over an individual household's life time.
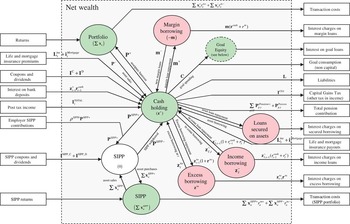
3.2.9 An example of a constraint sub-model for optimal portfolio allocation in terms of various cash flows is given in figure 6. Figure 6 corresponds to the fundamental iALM annual cash balance constraintFootnote 14. This constraint considers all stores of value and the inflows and outflows of wealth that are linked to each store. We can represent the annual change in the value of each store in terms of the other sets of fundamental constraints of iALMFootnote 15. The overall optimisation problem may become infeasible when liabilities and/or required level of consumption exceed the possible returns from the household assets and other sources of income.
Cash balance diagram

3.2.10 Figure 6 illustrates the flow of wealth in iALM. The circles, with the exception of those for the SIPP and ISA (omitted) accounts, are stores of valueFootnote 16. The SIPP and ISA account circles do not store value; their value is stored in their respective portfolio circles (in the diagrams representing their portfolios in other constraint sub-models). Net financial wealth is the sum of all stores of value. Arrows show paths by which wealth can be transferred from one store of value to another. Arrows between value stores (circles) represent flows of wealth that do not change the overall net financial wealth. For example, taking a bank loan transfers wealth from the bank loan store (which becomes more negative) to the cash holding store (which becomes more positive). Arrows that start from boxes on the left outside the dotted box are inflows of wealth to the household. These include such things as regular income (e.g. salaries), interest on bank deposits and earnings from bond coupons and share dividends. On the right hand side are outflows of wealth from the household. These include such things as interest charges on loans, taxation and consumption. The difference between inflows and outflows gives the net increase in a household's financial wealth in a given year.
3.2.11 The risk characteristics of the evolution of optimal portfolios depend on asset return volatilities and their correlations and the risk management constraints of the portfolio models. These constraints impose a tolerable annual drawdown of the portfolio on each scenario over the household's lifetime which is set according to individual household preferences.
Pensions
3.2.12 Pensions are designed to provide a steady household income after retirement. In order to encourage saving for retirement the UK government provides special tax status for pension accounts, see HMRC (2008). Specifically, any money paid into a pension account is exempt from taxation and any income from these investments can accrue in the account free of tax. Withdrawals from pensions are subject to income tax and, in some cases, further tax penalties depending on the pension size. In the UK pensions are of three basic types. First, there is the Self Invested Personal Pension (SIPP) which is an individual investment portfolio to which contributions can only be made up to, and withdrawals only after, retirement. Secondly, there are Defined Benefit (DB) pension plans to which both individuals and employers contribute before retirement and which pay a fixed proportion of an individual's salary each year after retirementFootnote 17. Finally, Defined Contribution (DC) pension plans are similar to a SIPP, except that while individuals and employers usually both contribute before retirement, an individual may have no control over the portfolio allocation in such plans. An ISA is a DC pension plan whose contributions are individual with full individual control of asset allocations. For simplicity, DC pension plan accumulations are modelled with returns at the same rate as corporate AA bonds (consistent with FRS17 Retirement Benefits Rules). All three basic types of pension are subject to both annual contribution limits and lifetime contribution limits. For more details on alternative pension plans and annuities, which pay an annual income from the accrued capital of many pension accounts at or subsequent to retirementFootnote 18, the reader is referred to Blake (Reference Blake2003), Milevsky (Reference Milevsky2006) and Clark et al. (Reference Clark, Munnell and Orszag2006).
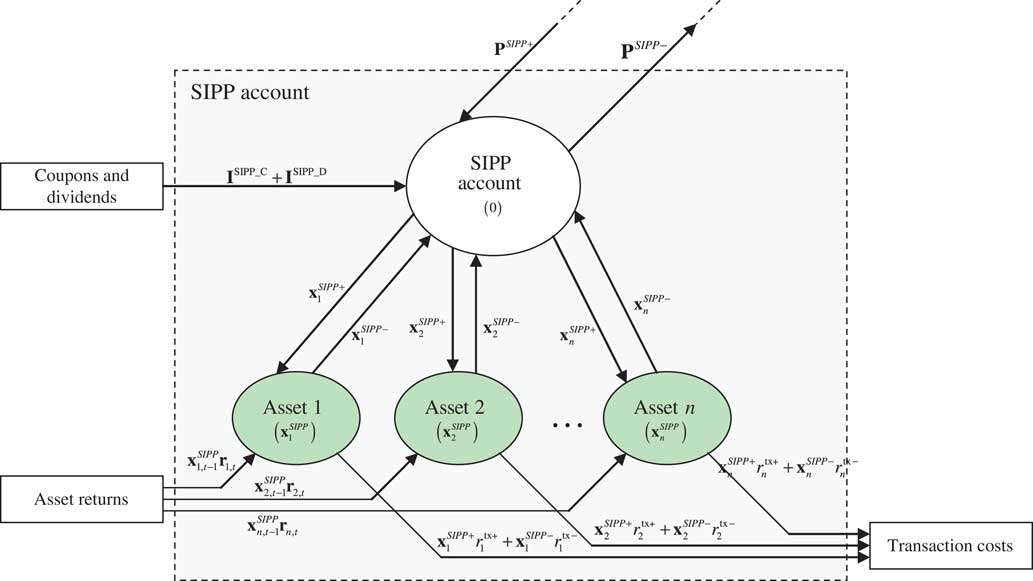
3.2.13 To delve a stage further into the complexity of the UK iALM model we consider the structure of individual (taxable, SIPP, ISA) portfolios. As shown in figure 6 for the SIPP portfolio, each of these portfolios represents the sum of all of the constraints across their constituent assets. We illustrate the detailed structure of the SIPP portfolio by way of example. The SIPP portfolio is shown as a single store of value in figure 6, but it is represented by multiple stores of value in figure 7. The individual asset circles in the latter diagram correspond to the SIPP's individual asset constraints. A similar interpretation applies to the taxable and ISA portfolios. The cash holding circle at the centre of figure 7 leads to the annual cash balance constraint of figure 6 which is at the very heart of iALM.
SIPP portfolio cash flow diagram
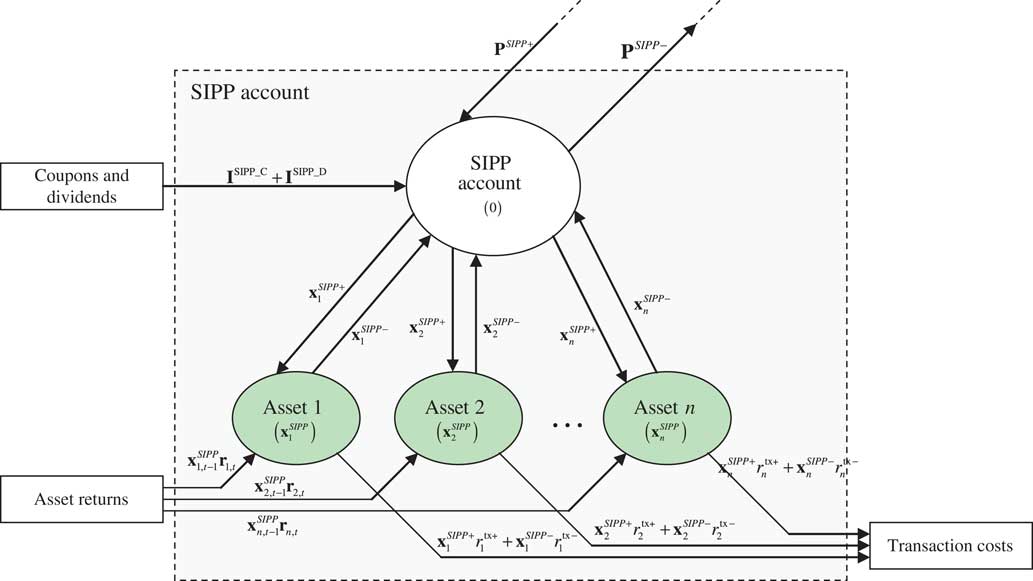
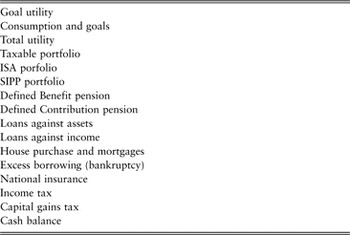
3.2.14 The optimized decision variables of the portfolio sub-models guide the tax efficient annual rebalancing of assets and generate optimum portfolio return. Therefore, together with the stream of labour and other income, the income from after-tax portfolio returns provides optimal spending on goals. In other words, optimum portfolio asset allocation leads to optimum prospective consumption. Many decision variables constitute the optimum solution of iALM. We classify these into separate categories corresponding to the appropriate entities of the meta-model (see Table A1) and the categories of the financial plan such as portfolio, wealth, goals and cashflows. But the main objective of iALM is to provide a household with initial recommendations for active portfolio and cashflow management for the year ahead.
4. An Illustrative UK Household through the Crisis
4.1 In this section we look at portfolio decisions and goals for an example household in more detail. We begin with a household decision problem and the household data we used for our modelFootnote 19. The Financial Times (FT) in its ‘Money’ weekend supplement used to have a ‘Money Makeover’ section in which a family described their financial position and goals and asked experts for their recommendations on investment, savings and appropriate spending. The quantity and quality of the data provided by households varied significantly, but in general household members specified their income and wealth and listed major liabilities. They also stated their major financial goals. We collected data on these household profiles over two years. In addition we created multiple copies of individual profile alternatives by adding liabilities, changing planned retirement age, increasing sets of desired goals in the form of real estate, luxury items or private education for children and so on – to reflect the myriad variations of individual life circumstances.
Household profile
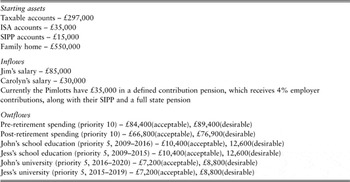
4.2 Let us take as an example a family whose major financial details were given in the FT of 1–2 July 2006. Jim and Carolyn Pimlott have extensive savings, having both worked full time in professional jobs for 20 years. They are 43 and 45 respectively and they hope to work until they are 65. They have already paid off their mortgage. They state that their main aim is to “achieve financial security and freedom”. Table 2 summarises their financial position and goals. In figure 8 we show selective input data for cash outflows as required by iALM. The Pimlott household specify their living expenses at acceptable and desirable levels with chosen priorities. Aside from living expenses prior to a comfortable retirement, their only financial goals are to provide for private school and university education for their two children.
Pimlott household profile

Specification of individual consumption data by the Pimlott household

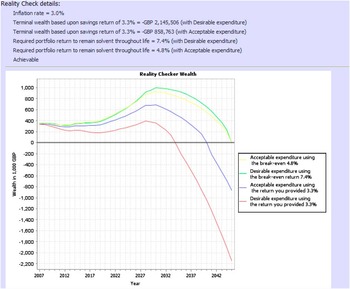
4.3 Recall that in our approach we assume that attitude to risk and return is merely a reflection of current financial status, liabilities and future consumption goals. Our trials with data from many individual (US and UK) households demonstrate that individuals often overestimate their earning and spending prospects which would lead to bankruptcy or very small probabilities of goal achievement.Footnote 20 In this situation some necessary changes to input data are needed such as the postponement of retirement, wife returning to work, reduction in the number of goals or their monetary values, and so on. This stage of financial planning is supported by a preliminary deterministic stage before the full solution of iALM. We call it the ‘reality check’ since it generates a value for a target average portfolio return which would provide the household's ‘sustainable wealth’ over a lifetime.
4.4 For our example household we perform the so called ‘reality check’ (figure 9) which is a calculation, under conditions of constant inflation and constant portfolio return, to evaluate the cashflow and liabilty balance at the time of expected death of the principal of the household. Assuming an inflation rate of 3%, the Pimlott family will sustain their desirable lifestyle up to death of the last surviving head of household if their financial portfolio will return 7.4% on average annually. On the other hand, if they put all their money in a savings account with a return of 3.3% per annum, they will be over £2,000,000 in debt at the end of life. Since, as we shall see, a target average return on investment of 7.4% is achievable under normal market conditions, we move on to solving the stochastic iALM model.
‘Reality check’ of household financial wealth and valuation of the portfolio risk/return characteristics

iALM recommendations
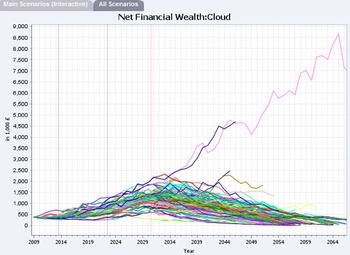
4.5 The first financial plan generated for the Pimlott family is as if it were made in 2007, with recommendations for wealth, portfolio allocations, various cash flows and other decisions over the household's lifetime presented below in figures 10 to 23. In 2007 the forecast of asset returns was optimistic, resulting in portfolio-generated wealth with many high return scenarios as shown in figure 10. Note the differing household lifetimes denoted by the various wealth scenarios and the few ‘jackpot’ scenarios.
Evolution from 2007 of Pimlott family net financial wealth

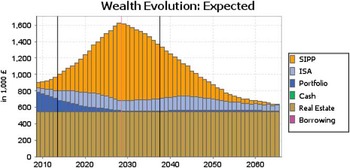
Expected evolution from 2007 of constituents of Pimlott family wealth

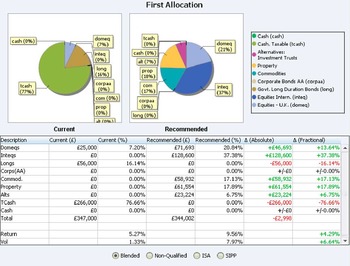
Initial total asset allocation recommended in 2007

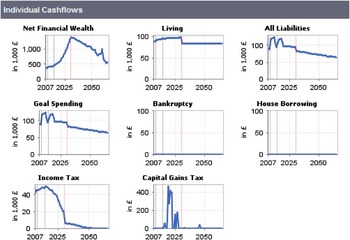
Expected optimal lifetime cashflows recommended in 2007

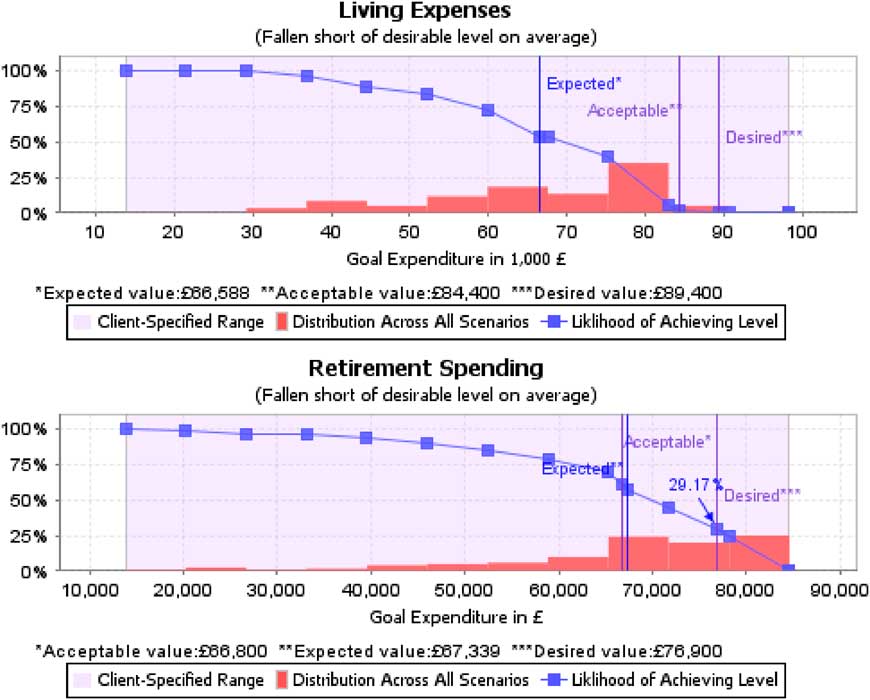
Pre- and post-retirement spending goal achievement in 2007

Financial Times House Price Index

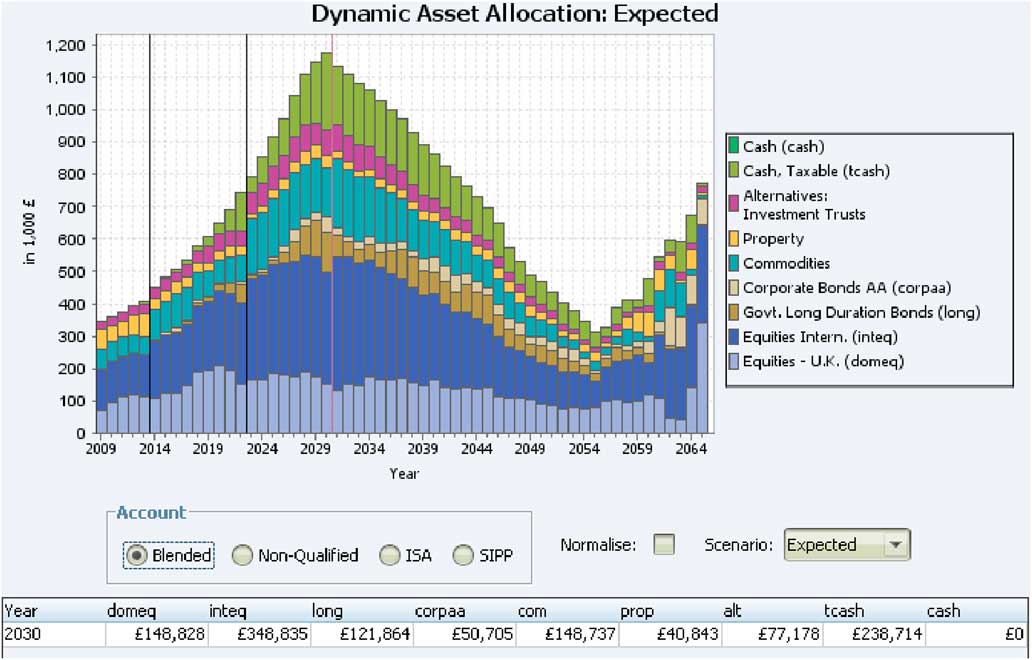
Dynamic asset allocation recommended in 2007 over the household life cycle

Pre- and post-retirement spending goal achievement in 2009
Evolution from 2009 of Pimlott family net financial wealth

Expected evolution from 2009 of constituents of Pimlott family wealth

Initial total asset allocation recommended in 2009

Dynamic asset allocation recommended in 2009
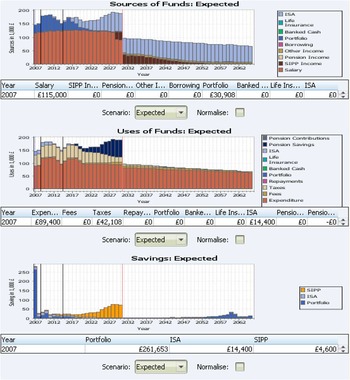
Expected sources and uses of funds and total savings projected in 2007

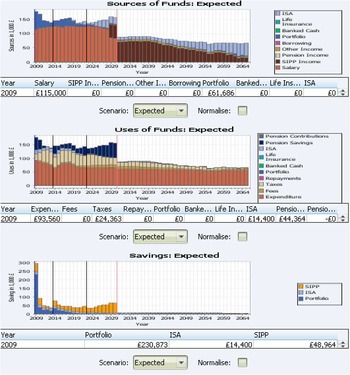
Expected sources and uses of funds and total savings projected in 2009

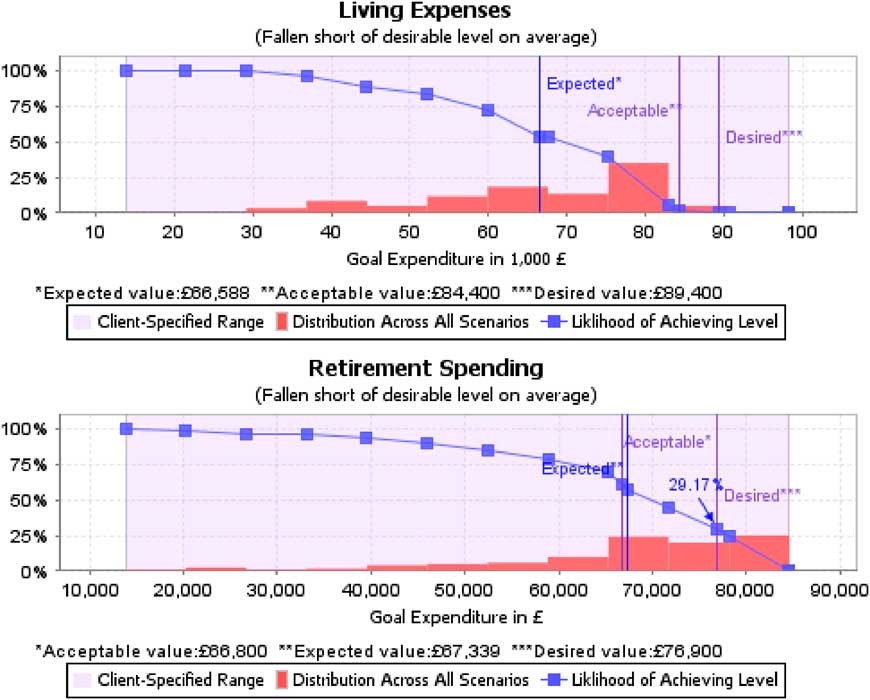
4.6 The expected (across scenarios) evolutions of the monetary value of the various constituents of household wealth are shown in figure 11. Figure 12 shows the iALM recommended initial total portfolio allocation which leads through annual rebalancing to the various prospective cash flows and goal spending over the household's lifetime shown in figures 13 and 14 (only pre- and post-retirement living goals are shown as illustrations). In spite of the significant variations in predicted net financial wealth at the end of household lifetime shown in figure 10, in 2007 the histograms of living and retirement spending on individual scenarios (shown in figure 14) are almost all projected to be above the desired value with a probability of goal achievement close to one.
4.7 The recommendations of iALM are in agreement with the general advice of the FT's experts to the Pimlotts such as suggestions of “a portfolio of low-cost index-tracking funds for global equity exposure, fixed interest securities and commercial property funds”, “to make their affairs more tax-efficient” and “to review their pension funding to see if they could make use of spare capital” by managing wealth between three accounts as recommended by iALM and by investing in ISA and SIPP accounts up to allowance limits (figure 11).
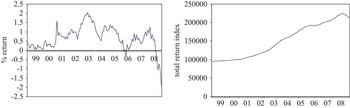
4.8 With current knowledge of the 2007–09 crisis, the high proportion of the 2007 allocation into property seems a perverse recommendation which we explain with the following argument. The initial portfolio allocation on 1.1.2007 is based on simulation of return processes calibrated over the period of the previous ten years. For the residential property investment asset class we use the Financial Times House Price Index (Table 1) data up to 31.12.2006. The fall in house price index returns corresponds to mid-to-late 2007 (see figure 15) which was not in the historical data at the time of the recommendation for 2007Footnote 21.
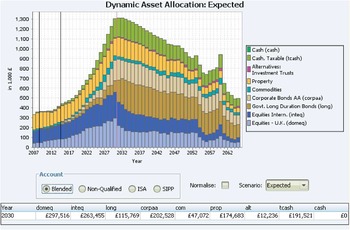
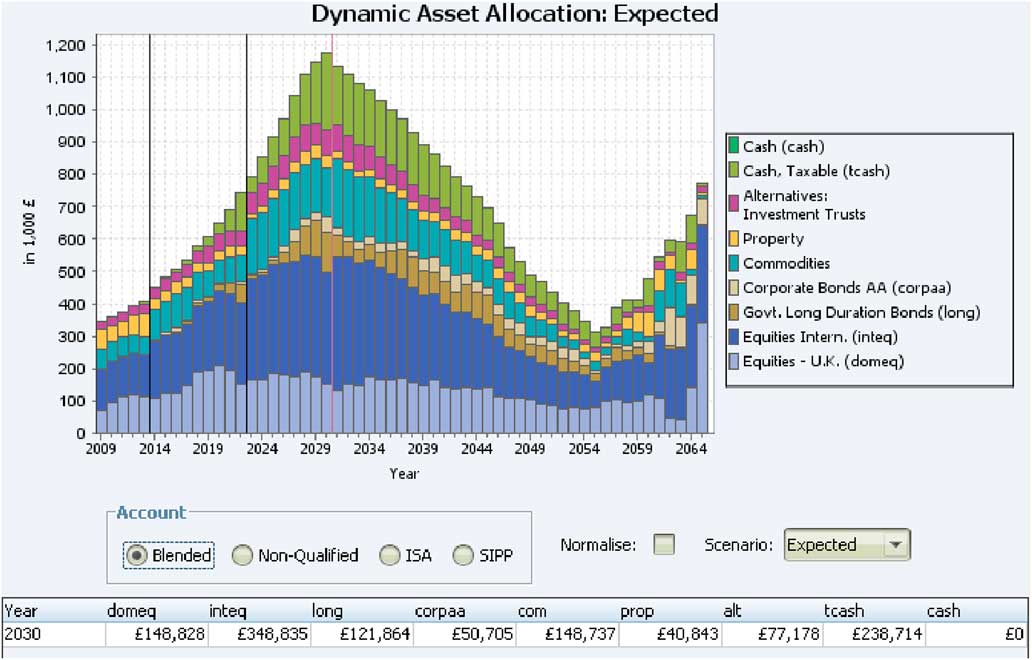
4.9 However the expected dynamic asset allocation as of 1st January 2007 shown in figure 16 takes into account the high volatility of the house price index return process and recommends prospectively a move to risk-free investments (cash) later in life. Note that at the time of retirement in 2030 the portfolio proportion of investment in the prospective property index is just over 13% of total portfolio value (in comparison with 46.5% in 2007).
Performance through the Crisis
4.10 For many UK and US households analysed the target annual average portfolio return of the reality check is in the range of 9–12%, which would be near impossible with the market returns projected in 2008–09. For our example family in 2009, we consider that the required 8.3% portfolio return is achievable (but difficult) and re-run iALM with the simulator parameters recalibrated to more current returns by adding two years (using monthly data) for the parameter estimates and simulating from values in January 2009Footnote 22.
4.11 The histograms for goal achievement of the 2009 recommended financial plan in figure 17 show how the economic downturn changes household expectations and results in significant dispersion in goal expenditures (compare figure 14). By presenting expenditure in the form of a distribution of values across scenarios, the iALM financial plan enlightens the household using visual information regarding the level of uncertainty inherent in real life.
4.12 Figures 17 to 20 illustrate the changes in various variables of the plan caused by the Crisis. Comparing figures 12 and 20, we see that the major recommendation of iALM for 2007, in the middle of the property boom, was in residential property (REITs or buy-to-let). While properties continue to produce rental returns, in 2009 (and also in 2008) iALM recommends reduced residential property investment and significantly increased investment in overseas equities and commodities – again reflecting current investment practice. The dynamic asset allocation of figure 21 now puts only 3.47% of portfolio value into the property index at the retirement date.
4.13 Due to the lower predicted returns from their financial assets in 2009, to achieve their goals the Pimlott family must invest much more aggressively than in 2007. Since portfolio risk management in this model is implemented by controlling drawdown of the portfolio in all scenarios with chosen loss tolerance (in this example of 15%) some returns are simply unattainable. Both the 2007 and 2009 portfolio examples are solved using the version of the portfolio allocation submodel with limits on the investment in any particular asset class representing the subjective view of the professional financial adviser, which can be modified if requiredFootnote 23.
4.14 The important lesson learned from running iALM with updated projected asset returns however, concerns the Pimlott's saving accounts. In spite of the financial crisis the recommendation of putting money into their SIPP and ISA accounts, up to the regulatory limits, remains unchanged from 2007. However, as a result of the Crisis, the SIPP and ISA accounts are now projected to become the main source of income in retirement for the household, since the taxable portfolio account is seriously depleted due to prospective lower market returns by the time of retirement, compare figures 22 and 23.
4.15 Notice from figure 21 that the familiar life-cycle pattern of wealth decumulation after retirement has now become the prospective reality for the Pimlotts (compare figure 16). Recall that iALM recommendations are designed to support at least an annual household financial planning exercise, possibly assisted by a financial or wealth management advisor, in light of realistic forward projections of current market conditions. Although it is possible that in the future Pimlott family fortunes would exceed the iALM projections made in 2009, it is only prudent to consider the future implications of the current market which emphasise the key role of tax-shielded saving for retirement.
5. Conclusion
5.1 In this paper we have described a meta-model for individual household life-cycle financial planning at cashflow level and its instantiation. It is difficult to present an adequate description of the nature and role of individual asset liability management because of the complexity and novelty of many of the concepts involved. We have presented the fundamentals of the dynamic iALM meta-model in terms of its structure, simulation and optimisation models and its interactive use. The iALM recommendations for a representative UK household are illustrated by a financial plan generated in 2007 and then compared with those of a modified 2009 plan reflecting the credit crisis of 2007–08. Due to active management of investments the modified 2009 prospective financial plan generates sufficient wealth to sustain the pre- and post-retirement consumption goals as closely to as possible to the acceptable or desirable levels, but recommends conservative retirement savings and ‘trims down’ household expectations.
5.2 For rapidly aging populations there are very few practical tools to help individuals make sensible financial decisions. Much cross-sectional study of individual household consumption and savings behaviour has been sponsored by governments around the world. While the results certainly inform fiscal and other government policy, they are of little value to individuals faced with specific decisions as to whether or not to retire, buy a new home and so on. The market on the other hand has become more complex, requiring highly specialised information and providing sources of individual financial advice of questionable value, based on subjective assessment of a client's attitude to risk. This remains a bewildering topic for both households and advisors which is made worse by extensive questionnaires. Moreover, professional advice is given to individuals using mainly short-term investment models and is too often only revised infrequently.
5.3 The class of models represented in this paper allows financial planning to shift the focus from the short-term to the long-term, from the cross section to actual decisions and from static to dynamic actively managed investments. Most importantly, they shift the focus from a universal age-dependent risk attitude to risk management specific to the household in terms of its current situation and future goals and to easily understandable net cashflow analysis which takes into account taxes and bequests. The model implementation supports informed financial planning decisions and, by interactive use, allows the exploration of an endless variety of ‘what-if’ evaluations of alternative decisions to anticipate their impact on the household. By applying dynamic stochastic programming technology a paradigm shift from static advice to interactive consultation has become a reality today.
Appendix: Technical Overview of iALM
A.1. Principles of Dynamic Stochastic Programming
The iALM tool is implemented using dynamic stochastic programming (DSP) methodology and solution techniques. There are many applications of DSP in industrial planning and management (Prekopa, Reference Prekopa1995; Dempster et al., Reference Dempster, Hicks Pedrón, Medova, Scott and Sembos2000; Wallace & Ziemba, Reference Wallace and Ziemba2005). Institutional funds, and particularly pension funds, use stochastic programming techniques for portfolio construction and for the formulation of optimal trading strategies (see, for example, Zenios & Ziemba, Reference Zenios and Ziemba2007; Dempster et al., Reference Dempster, Germano, Medova, Murphy and Sandrini2009). In what follows we briefly describe the major steps in the construction of a dynamic stochastic programme, with the aim of introducing this methodology to the novice reader.
Dynamic stochastic programming incorporates many alternative futures in the form of simulated scenarios from a discrete time, continuous state, multi-dimensional stochastic data process

The stages correspond to the expected times of major changes for decisions in the future. In general this discretization of time is at a frequency different from that of the data process’ simulation time steps.
The evolution of the discrete state simulated data process across time is given by a scenario tree. For example, in figure A1 the 3-3-2 scenario tree shown branches three times at stage 1, then each scenario branches into 3 further scenarios at stage 2, and again at stage 3 each scenario branches into 2 scenarios. This branching structure schematically represents in 18 scenarios the uncertainty regarding the state of the underlying simulated data process.
An example scenario tree schema

All decisions, at intermediate nodes of the tree, take into account the possible evolution of the stochastic data process from that point forward. The decision at the root node encompasses all uncertainty and, in this sense, it is a ‘robust’ solution of the DSP problem with respect to all generated states of the stochastic data process.
A generic dynamic stochastic programming problem (Dempster, Reference Dempster1988, Reference Dempster2006) is given by

where the constraints hold almost surely (a.s.), i.e. with probability one. Stages are shown here of equal length for notational simplicity but in the iALM model they are of variable length (see A.2).
The idea of this multi-stage, forward-planning model is that at each stage in the model an observation of the data process is made, which is then followed immediately by a decision, i.e. an observation is taken just before a decision is made. Decisions are non-anticipative, which means that decisions made at any stage are only dependent on the information available up to that time. This is achieved at branch points of the scenario tree by fixing portfolio decisions there to be the same across all scenarios originating from the same branch point. Subsequent decisions in periods between stages (branch points) on scenarios in the tree take into account all possible scenarios in that stage (Dempster & Thompson, Reference Dempster and Thompson2002).
The objective of the DSP problem is in the form of nested optimisation problems given by the conditional expectation of the data and decision process 
The constraints run across time and correspond to stages of the decision process with its first period deterministic decision  .
This conceptual dynamic stochastic representation is used to generate a deterministic equivalent of the DSP with the specific probabilistic structure given by scenario tree for solution (Dantzig & Madansky, Reference Dantzig and Madansky1961) as

All simulated data realizations are used here in a non-redundant manner. Note that all previous values of both the data and decision processes are allowed here to influence the current decisions. This non-Markovian structure is required for iALM when considering, for example, mortgaged house purchases.
In the deterministic equivalent problem all random coefficients specified in the constraints of the DSP are realizations of the underlying stochastic process represented by the scenarios. In the case of linear constraints and objectives this is a very large linear programming (LP) problem which becomes very sparse when the problem is Markovian. We can therefore use standard solution techniques to solve this linear programme numerically. Stochastics™ is CSA's generic modular software for solution of DSP models and incorporates preprocessing and both nested Benders decomposition and interior point solvers.
A.2. Structure of the iALM Model
As discussed in Section 3, the iALM large scale LP model is actually a collection of sub-models, each of which is represented by (often a very large number of) appropriate constraints, together with supporting algorithms for price and value calculations to supply constraint parameters at run time. Many of these sub-models can be switched on or off at run time according to household requirements and preferences supplied through the GUI. Since the detailed US and UK model documents are each of the order of 200 pages, we can only give an overview of this complexity here. Table A1 lists the constraint sub-models in the UK iALM model.
Sub-models within the iALM LP model

To give a glimpse of the nature of these sub-models we treat the simplest but most important: the cash balance constraint in each annual period t = 2,…,T. The cash balance constraint ties all the disparate elements of iALM together, it is used to reconcile all the entities in figure 6 in Section 3.2, to which it corresponds. It is the fundamental constraint on the evolution of the cash holding given by

The omission of interest on banked cash is because the z variable is used as a balancing variable in the cash balance equation which can be flexibly reallocated each year. This is consistent with the idea of a current account which offers little or no interest. The t-cash asset (3 month Treasure bill index) can be used to represent a savings account which is an investment instrument.
Solution of the linear DSP model in its deterministic equivalent LP form provides optimal values for many decisions of interest – spending, amount of savings, tax-efficient allocation between multiple portfolios, etc. – across time simultaneously for multiple scenarios of random process representing market returns, foreseen liabilities, life events and goals. The current UK iALM model involves 22 random processes that vary over a household's lifetime and around 200 constraints per node of the scenario tree. The LP formulation typically involves a constraint matrix of over 3 million non-zero entries.
A.3. Technical Advances Incorporated in iALM
It is worth noting that versions of iALM incorporate five scientific breakthroughs which to the best of our knowledge have not so far been treated in the open literature on stochastic optimisation applied to asset-liability management problems – institutional or individualFootnote 24. These are reliable solutions of large scale problems with:
– up to 90 annual decision periods using novel information constraints on most decisions
– random scenario lengths due to deaths of household members
– occurrence of non-terminal random events such as entry and exit from long-term care
– automatic placement of major (tree branching) rebalancing points based on problem data
– no solver parameter tuning required for first-time solution of arbitrary instances determined by input household profiles and their variants.
 after the mortgage has been repaid.