1. Introduction
The financial repression Working Party was commissioned by the Finance & Investment Board of the Institute and Faculty of Actuaries in 2012.
The work was commissioned, in response to the persistent negative real yields post the 2008 financial crisis and subsequent sovereign debt crisis, to consider whether the topic of financial repression, which was becoming prominent in the economic literature, was relevant to the situation of UK insurers and pension funds.
2. Financial Repression in Action: Long End of the Curve
In June 2013. Mr Andrew Haldane, Executive Director for Financial Stability at the Bank of England, told MPs that “Let’s be clear, we’ve intentionally blown the biggest government bond bubble in history” (UK Parliament, 2013a).
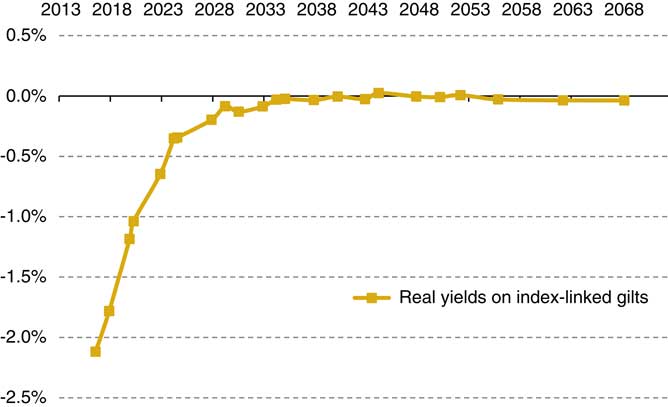
Figure 1 shows the real yield curve on UK index-linked gilts at the end of October 2013. Real yields were negative across the curve – in other words, despite a historically high budget deficit and the loss of the AAA rating, borrowers had to pay the British government for the privilege of lending money to them – and still index-linked gilt auctions proved very popular.
Real Yields on Index-Linked Gilts Source: Bloomberg.

In September 2013, the UK government issued a 55-year index-linked gilt, with a coupon of just 0.125% and hence a duration of 53 years. £5 billion of the gilts were sold at a real yield of 0.137%, from an order book of £10.8 billion (Debt Management Office, 2013), in large part to UK insurers and pension funds advised by actuaries. Within 1 month of issue, the bond was trading at a negative real yield.
Had index-linked gilts become one of those mythical economic creatures – a “Giffen good” where demand increases as the price rises? The classic economics textbook example is potatoes in the Irish famine – as the price rose people could not afford to buy other food, so they bought more potatoes. Substitute gilts for potatoes, pension funds for people and return-seeking assets for other food – do we have the UK Linker Famine (Kaminska, Reference Kaminska2011)?
3. Financial Repression in Action: Short-Term Savings Rates
As actuaries we naturally concern ourselves with the long end of the interest rate curve, but it is the shorter end that most directly impacts retail borrowers and savers.
Financial repression, and the plight of savers, began to generate a lot of headlines from mid-2013. Sample headlines included:
“Savers ‘condemned to £33bn loss’ by Bank of England” (Daily Telegraph, August 2013).
“The £170bn secret raid on your savings: How keeping rates at a record low is a government ploy to pay off its debts” (thisismoney.co.uk, August 2013).
“The elderly must suffer low rates so the young can pay down their debts” (Daily Telegraph, July 2013).
Choose your own figure – £33 billion per the Telegraph, £170 billion per the Mail – and the villain: the Bank of England’s monetary policy, the government’s plan to pay off its debt or overly indebted youngsters – but the clear implication of the financial press was that savers were being repressed. The last headline is actually a précis of remarks from the retiring Bank of England governor, as we will discuss later.
4. What is Financial Repression?
Financial repression was originally coined in two separate books written in 1973 (McKinnon, Reference McKinnon1973; Shaw, Reference Shaw1973) and refers to measures by governments that distort domestic financial markets – particularly ones that have the effect of channelling funds to their own debt.
The key reference for our work was written in 2011 by Reinhart & Sbrancia. They looked at the “stealth” measures that governments used to successfully liquidate their debts in the post-World War 2 era of 1945–1980, which included (Reinhart & Sbrancia, Reference Reinhart and Sbrancia2011):
1. explicit or indirect caps or ceilings on interest rates;
2. direct lending to government from a captive domestic audience;
3. regulation of cross-border capital; and
4. tighter connections between governments and banks.
5. Current Relevance of Financial Repression
The Reinhart & Sbrancia paper was particularly timely because, post the financial crisis with elevated debt levels, financial repression is re-emerging as a policy tool.
We will focus on the first two of these measures, which are low rates, and a captive domestic audience but tighter connections between governments and banks is clearly also a key current theme, and regulation of cross-border capital, which is creeping back on to the policy agenda, for example, in Cyprus and Iceland.
These measures are implemented under the umbrella of “macro-prudential regulation”, which is an evolving current theme given the new Financial Policy Committee. Indeed, there is strong evidence that easing regulation leads to a higher probability of financial crises, which can then lead to repressive measures being re-imposed. A key 1984 paper by Carlos Diaz-Alejandro, looking at emerging markets, was entitled “Goodbye Financial Repression, Hello Financial Crash” (Diaz-Alejandro, Reference Diaz-Alejandro1984) with Chile as the poster child.
Financial repression is also typically associated with negative real yields on government debt, which as we have seen persist across the curve in the United Kingdom. These negative real yields have the effect of a hidden tax on savers, which is paid to debtors, including governments.
6. How Can Debt to GDP be Reduced?
Perhaps, the biggest political and economic question today is how governments can reduce their high debt burdens. There are historically five options (Reinhart & Sbrancia, Reference Reinhart and Sbrancia2011):
1. Economic growth. This sounds the most attractive option but in reality an uncommon solution as high debt tends to be associated with low growth (Rogoff & Reinhart, Reference Rogoff and Reinhart2013). Indeed, the aftermath of major wars tend to be the rare exception.
2. Austerity. Political debate focuses on austerity but this has yet to succeed in the EU in particular.However, in the past the most common options have actually been:
3. Default. Particularly pre-World War 2. For example, European countries were essentially forgiven their World War 1 debt by the United States in 1934: for the United Kingdom this equated to a debt reduction of 22% of GDP. The United States in turn itself abrogated on the gold standard estimated to have reduced its debt GDP by 16% (Rogoff & Reinhart, Reference Rogoff and Reinhart2013).
4. Hyperinflation
5. Financial repression with a steady dose of inflation, particularly post-World War 2 in the tightly regulated Bretton Woods era.
7. Gross Government Debt as a Per Cent of GDP
1945–1980 was the key era where financial repression was used as a policy tool and interestingly, current debt levels are almost identical to the 1945 levels with debt to GDP in the developed world at just above 90% in 2010 compared with a post-war high of also 90% and a post-war low of around 30% in the mid-1970s (Reinhart et al., Reference Reinhart, Reinhart and Rogoff2012).
8. Financial Repression Tool 1: Maintaining Low Interest Rates
In the 1945–1980 era, interest rates were often kept low by explicit regulation. For example, Regulation Q in the United States prohibited banks from paying interest on demand deposits and capped interest on saving deposits (Reinhart & Sbrancia, Reference Reinhart and Sbrancia2011).
Nowadays, unconventional monetary policies are the tool of choice, including quantitative easing (QE).
9. Real Interest Rates in the United Kingdom
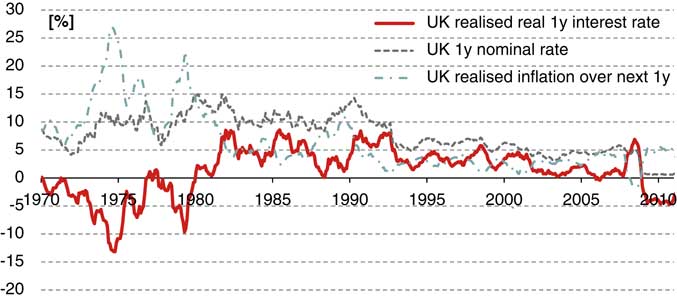
The history of real interest rates in the United Kingdom and the United States since 1945 shows that the period of sustained positive real yields, 1981–2007, is arguably the exception, not the rule.
In the United Kingdom, from 1945 to 1980, real yields were negative almost 50% of the time. In the 1970s, negative real yields were mostly the result of high inflation but in the 1950s to 1960s, it was, as now, owing to low nominal rates (see Figure 2).
UK Realised 1-Year Real Rate Source: Bloomberg, Bank of England.

The resulting stealth “tax” on holders of UK government debt has been material. One can quantify this by accumulating the impact of negative real yields, implicitly assuming that investors would naturally want at least a zero real yield to finance the government.
This “tax” amounts to 3.6% of GDP per annum throughout the 1945–1980 period, similar for the United States and over 5% in Italy and Australia (Reinhart, Reference Reinhart2012).
To put that in context, personal income tax in the United Kingdom is currently 10% of GDP, so that’s a stealth tax equal to 40% of total income taxes.
10. Impact of QE on Gilt Yields
Opinions on the impact of QE are mixed. The Bank of England’s own studies suggest QE has reduced nominal gilt yields by 100 bps (Bank of England, 2012). Other studies range from 50 to 150 bps. However, others point out that government bond yields fell almost as fast in countries that did not perform QE (Towers Watson, 2012) and question the expansionary nature of QE (Fisher, Reference Fisher2013).
Our view as a working party is more nuanced. While the Bank of England has been the largest individual buyer of gilts, there has been little evidence of crowding out and others have been bigger buyers in aggregate. UK insurance and pension holdings over the period end 2008 Q3 to 2012 Q3 have risen by £100 billion, and domestic banks also purchased over £100 billion of gilts, having previously held almost zero.
Indeed, one could argue that regulation – mark-to-market for insurers and pension funds and new liquidity rules for banks – has been an equal if not bigger driver of demand, together with sterling benefitting from the flight to quality in the EU sovereign debt crisis.
We also observed that the Bank of England performed an “event” study, focusing on the first few days after the announcement of QE programmes. Yields actually often rose during the periods of actual buying, which is a case of the classic trading rule “buy the rumour, sell the fact”.
How then do we explain that yields in the United Kingdom and the United States were on a strongly downward trend between 2009 and 2012 and only increased once tapering of QE became a possibility? We believe that the falling yields were not just a symptom of the Fed and Bank of England buying bonds, but more of the fact that policy was not generating sufficient growth and inflation.
We see similar evidence internationally, most notably in Japan where the announcement in April 2013 of the massive “Abenomics” monetary experiment caused the Yen to plummet, inflation expectations to rise and equities to rally; 6 months later these markets were back where they started.
11. Impact of Low Rates on Insurers and Pension Funds
Whatever the reasons, it is undeniable that gilt yields have declined dramatically, for example, from mid-2011 to December 2012 the 15-year gilt yield fell from c. 4.25% to 2.50% pa.
For UK pension funds, this has had a major impact on deficits: the increase in the value of assets has not kept pace with the sharp rise in liabilities. For example, the Pension Protection Fund estimated for their data set of pension funds with c. £1 trillion of assets that their collective s179 deficits increased from just £1.2 billion at 31 March 2011 to £204.2 billion by 31 March 2012, a fall in funding ratio from 100% to 85% (Pension Protection Fund, 2012).
Gilt yields have since partially recovered: the 15-year gilt yield reached as high as 3.4% at the end of 2013, although very long end rates have continued to fall (forward 20y20y swap rates actually fell 50 bps over 2013).
For sponsors of pension funds, the main effect of falling yields has been to increase pressure for deficit contributions. Interestingly, a large part of these additional contributions are invested in gilts, which is further fuelling the fall in yields and helping the government finance its debt.
For life insurers, it is mostly the customers, particularly retiring annuitants, that have suffered.
12. Balance-Sheet Recessions: What is That?
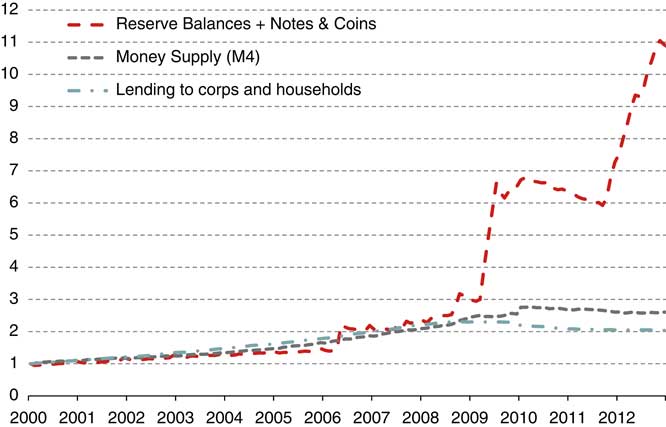
The other issue with QE is that it does not seem to have achieved the desired positive effects of boosting the real economy, as the cash has largely piled up on bank’s balance sheets and failed to increase the wider money supply (M4) or private-sector credit (see Figure 3).
Money Aggregates Indexed to 2,000=1 Source: Bank of England.

We believe this is because the economy is in a “balance sheet recession”, which is much like the experience of Japan for the last 20 years and the United States in the Great Depression (Koo, Reference Koo2011).
These special examples of recessions follow the bursting of a leveraged asset bubble, and lead to a situation where the private sector – corporate and households – enters an extended period of de-leveraging.
Note that the crucial feature is that the asset bubble is based on leverage versus say the internet bubble of 2001–2003, which, while it leads to significant wealth destruction, did not have such an impact on the wider economy and the wealth lost was mainly that gained from the bubble in the first place.
In the case of a balance sheet recession, there is an excess of savers, and a dearth of productive investment, and the government needs to act as a “borrower of last resort” to fill the gap.
This is what we saw in the United States in the 1930s: it was only increased lending from banks to the US government, resulting from the New deal, that expanded the money supply and it finally it took the ultimate fiscal stimulus – a world war – to raise rates to normal levels. Japan has yet to break free, although Abenomics may finally achieve this.
13. Balance Sheet Recessions: Yin and Yang
In the balance sheet recession theory, the economy can be in two states (Koo, Reference Koo2009).
We have become used to the normal textbook state, where the private sector is driven by profit maximisation. Monetary policy is effective, but Keynesian fiscal stimulus less so as it crowds out private investment. Price stability, financial stability and fiscal government debt sustainability are regarded as three distinct things, to be managed by monetary, regulatory and fiscal authorities, respectively.
However, during the exceptional balance sheet recession case, everything is reversed. The key private-sector focus is debt minimisation. Monetary policy becomes ineffective, “pushing on a string” as Keynes said. We see that price stability, financial stability and fiscal debt sustainability were not independent after all (Sannikov & Brunnermeier, Reference Sannikov and Brunnermeier2012).
Crucially, saving becomes a vice not a virtue, which means, as we will see, that policymakers may wish to penalise savers.
14. Unconventional Squared
As QE has failed to have the desired economic effect, central banks have increasingly turned to even more unconventional measures such as the Funding for Lending scheme, launched in July 2012, and the more recent Help to Buy scheme in the United Kingdom.
The Funding for Lending scheme, in particular, seems to have had little impact on bank lending – which has continued to contract – in our view in part because of the lack of demand in a balance sheet recession. These measures are further cases of financial repression as they distort markets – and potentially crowd out private savings.
15. Interest Rates on UK Retail Savings
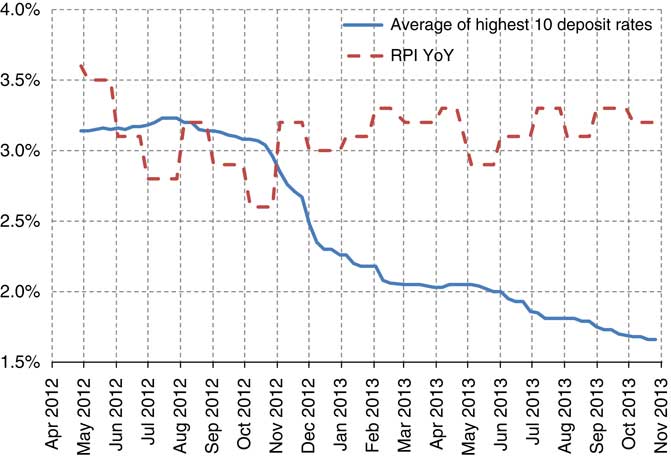
The main impact of these unconventional squared measures has mainly been to penalise savers, as banks no longer need to pay up for deposits to fund themselves, and savings rates in the UK have plummeted since they were introduced.
Figure 4 shows the rates available on the average of the highest ten available deposit rates, as calculated by Moneyfacts, and compares this to the annual increase in the Retail Prices Index for each month. Note that savings rates have continued to fall even as the markets are starting to price in the likelihood of base-rate increases (Investec, 2013).
Interest Rates on Deposit Accounts Versus RPI Source: Investec, Bloomberg.

As with government debt, we could estimate a financial repression levy based on the assumption that savers might expect to earn at least zero real returns, post tax, in normal conditions.
Estimates of this financial repression levy on savers as per the newspaper headlines earlier, give levels of c. 6% losses, which is not far short of the original proposed levy in Cyprus (The Economist, 2013). Note again the “stealth” nature of the UK levy.
16. What Does the Bank of England Say?
At an economic level, rising house prices have led to a transfer of wealth to the asset-rich baby boomers. In order for them to release equity from their houses to fund their retirement, they need to sell them to the younger generation. This generation can only afford the mortgages required at low interest rates. This impacts on the rates banks can pay to savers, who are the elderly people wanting to sell their homes.
In his final appearance before the House of Commons Treasury Select Committee, the retiring governor of the Bank of England, Mervyn King, addressed this issue directly (UK Parliament, 2013b), suggesting that low interest rates on savings were needed to allow a redistribution of wealth across generations:
“House prices went up. As the older generation retired or passed away, the housing stock was sold and had to be purchased by the new younger generation. That led to a transfer of wealth to the older generation, which took the form of the younger generation taking out a lot of debt and the older generation having a lot of liquid assets that they got from the proceeds of selling houses… If those long-term interest rates persist at very low levels and we do not get back to normal levels for some while, then households will be able to absorb those levels of debt”.
The new Bank of England governor, Mark Carney, also addressed the plight of savers in his first keynote speech in August 2013, when he introduced the concept of forward guidance (Bank of England, 2013).
“The prospect that interest rates might stay at their low level for longer will not be welcome for savers. We have tremendous sympathy for them… but raising interest rates now is not the answer… instead what savers need is a stronger economy. A stronger economy will mean higher asset prices… [and] is in all of our interests, as it will deliver… better job prospects for our friends, neighbours, children and grandchildren”.
His view of the need for low rates appears more nuanced and focused on the need for economic growth, but we note still the reference to asset prices and a hint at intergenerational issues.
17. Financial Repression Tool 2: Creating a Captive Domestic Audience
The second key financial repression tool is to create a captive domestic audience for government debt.
In the 1945–1980 period, we saw five main tools (Reinhart & Sbrancia, Reference Reinhart and Sbrancia2011), all of which are starting to appear again:
∙ Exchange controls: these were only abolished in the United Kingdom in 1979. They are also common now in the new era in emerging markets to prevent flows, and also in the EAA in Cyprus and Iceland.
∙ High reserve or liquidity requirements: as previously stated banks have bought over £100 billion of gilts since mid-2008, having previously held close to zero, the reason being primarily because of liquidity requirements.
∙ Transaction taxes: as in the proposed EU Financial Transactions Tax.
∙ Prohibition of gold transactions: for example, in the United States during period 1933–1974. The modern analogy here could be cyber-currencies such as Bitcoin, which have been used to circumvent exchange controls in countries such as China, and have correspondingly come under regulatory pressure.
∙ Regulation: it is perhaps no coincidence given what we have said, that the only two capital risk-free assets in Solvency II Standard Model, as per the draft Level II specifications (2014), are EU sovereign bonds and certain retail mortgages. In the latest November 2013 compromise on the Omnibus II Directive, proposed wording from the European parliament that “a zero risk treatment for government bonds no longer corresponds with economic reality” was conspicuously deleted from the final text agreed with the Commission and Council of Ministers, and the introduction of a Volatility Adjustment in the final long-term guarantees package actually strengthens the favourable treatment of sovereign debt (Council of the European Union, 2013).
18. The Rise and Fall of the Cult of the Equity
In 1954, the late George Ross Goobey (F.I.A.) at the Imperial Tobacco Pension Fund, recommended a switch to 100% equities. Interestingly, his justification included the lack of market-based regulatory and accounting standards for pension funds, the very strong sponsor covenant as well as the low yields on government bonds versus equity dividend yields (Avrahampour, n.d.).
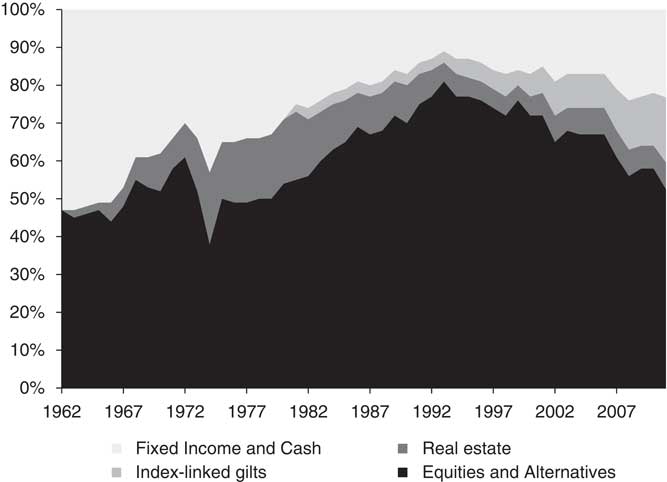
The resulting “cult of the equity” for UK pension funds that began in the 1960s started to reverse in the early 1990s and now equity holdings of UK pension funds are back below 50% and at early 1960s levels (UBS, 2012; Figure 5).
UK Pension Fund Asset Allocation Source: UBS Asset Management.

19. What Happened?
A very good overview of the rise and fall of the cult-of-the-equity was given in the First Ross Goobey Lecture by George Ross Goobey’s son, Alistair (Goobey, Reference Goobey2005).
It all started with the demise of Robert Maxwell in 1991, followed quickly by the insolvency of the Daily Mirror Pension Fund.
This was followed by a series of legislative/accounting changes to the nature of pension benefits from an aspiration to provide inflation-linked benefits, assuming strong sponsor support, largely unregulated other than via professional actuarial discretion to a contractual promise, which ultimately should be self-sufficient from the sponsor, policed by an external regulator.
Key events and legislative changes over the following 20 years include:
1991: the Daily Mirror pension scandal
1993: Goode Report
1995: Pensions Act 1995 and the Minimum Funding Requirement
1997: Introduction of compulsory LPI indexation and removal of tax credits on share dividends in the Budget
2000–2003: stock market collapse
2001: FRS17
2003: introduction of debt on employer
2005: Pension Protection Fund and Pension Regulator
2008: global financial crisis
2009–2012: QE and increased pressure from Pension Regulator to fund deficits
And the implications of these changes for asset allocation are clear. A lot of sound and fury has been generated on this topic in the profession over the past 20 years, much of it unnecessary, as these two statements are not necessarily contradictory:
∙ equities are a good long-term match for real liabilities; and
∙ equities are very poor short-term mark-to-market match for explicitly inflation-linked liabilities.
We should, of course, acknowledge that these events and legislative changes are mostly before the 2008 financial crisis and the subsequent pressure on government finances. However, they have certainly had the effect of reinforcing the government bond bubble since 2008 and have aided the government to finance its budget deficit at historically low rates.
Recent moves such as the proposal, rejected by industry, to introduce smoothing for pension valuations, and the changed remit of the Pensions Regulator appear actually designed to reduce pressure on pension schemes (UK Department for Work & Pensions, 2013a). The recent consultation on Reshaping Workplace Pensions could unwind many of the changes of the last 20 years (UK Department for Work & Pensions, 2013b), at least for future accrual.
We have seen a clearer example of explicit financial repression in the pension sector in Ireland, where we have seen:
∙ The National Pension Fund used to bail out the banking sector (Brown, Reference Brown2010).
∙ Taxes imposed on private pensions (The Pension Board, 2010).
∙ Sovereign annuities – where the risk on Irish government debt is explicitly passed to annuitants (The Pension Board, 2011).
20. Secular Stagnation
Tying this all together, there is potentially a key link between two subjects dear to our Profession’s hearts, which are demographics and economic returns.
Larry Summers, US Treasury Secretary for 10 years and originally Obama’s preferred candidate for Fed chair, and Paul Krugman, a Nobel-prize winning economist, have both recently raised this topic.
Summers points out that before the crisis, everyone now agrees, monetary policy was too loose and there was too much imprudent lending. Yet, despite that the pre-crisis period was marked by low inflation, no pressure on capacity and less than full employment (Summers, Reference Summers2013).
He speculates that we may be experiencing “secular stagnation”, which is a notion en vogue in economics pre-World War 2. This is similar to the balance sheet recession theory mentioned earlier. Secular stagnation theory suggests this new state of affairs may be permanent and become the new normal. In the absence of bubbles, the neutral natural rate of interest may be negative.
In part, this results from demographic factors: in certain macro-economic models, the natural rate of interest equals the rate of population growth. As Krugman observes in the period 1960–1985, when the US economy seemed able to achieve full employment without bubbles, the labour force grew on average at the rate of 2.1% pa. Looking forward, the Census projects that the population aged 18–64 will grow at only 0.2% p.a. between 2015 and 2025 (Krugman, Reference Krugman2013).
Even before the financial crisis in a 2005 speech, Fed Governor Ben Bernanke identified a “global savings glut” leading to a “relatively low level of long-term real interest rates” and highlighted demographic factors, in particular, “the prospect of dramatic increases in the ratio of retirees to workers in a number of major industrial economies” as a key factor (Bernanke, Reference Bernanke2005).
Krugman also links this to Keynes’ conclusions in his General Theory (Keynes, Reference Keynes1936) where Keynes opined that a high rate of interest was not needed to provide an incentive to save, stating that “interest to-day rewards no genuine sacrifice: there are no intrinsic reasons for the scarcity of capital” and forecast the “euthanasia of the rentier”.
The policy implications are profound and counter to conventional wisdom:
∙ the economy may need bubbles to achieve close to full employment;
∙ saving may be a personal virtue but a public vice;
∙ inflation and negative real returns on unproductive savings may be a good thing;
∙ governments may need to run permanent deficits and will have little difficulty in financing them; and
∙ financial regulation aimed at preventing the next crisis could actually make the situation worse by depressing borrowing activity and asset prices.
All the above have rather interesting implications for insurers and pension funds.
21. Final Thoughts
With reference to its original goals, the working party certainly feels that the topic of financial repression is highly relevant to the situation not only of UK insurers and pension funds, but also of retail savers.
Key questions we posed at the outset are why would anyone buy assets with negative real yields, whether pension funds and insurers are overly influenced by regulation, and whether their current situation is a deliberate example of financial repression with governments creating a captive domestic audience for their own debt.
We feel that regulation inevitably plays a key part in investment decisions, as illustrated by the story of the rise and fall of the cult of equity in pension funds: the rise was created by a realisation of their competitive advantage as a relatively unregulated long-term investor, and the fall by the 20 years of legislative and accounting changes from the Goode Report onwards.
Whether they have been “overly” influenced we will leave others to debate: legislation drawn up post the Maxwell scandal was deliberately intended to improve the security of pension scheme members. The result was to change the nature of the pension contractual promise, and the changes to investment strategy are an inevitable result of this. We would also note that long-dated index-linked government bonds have typically outperformed equities over the period, albeit this is to an extent self-fulfilling given the asset allocation changes.
As to whether governments wished to deliberately provide themselves with cheap finance, we would echo the words of Bernard Ingham, press secretary to Margaret Thatcher, who said, in 1985, “Many journalists have fallen for the conspiracy theory of government. I do assure you that they would produce more accurate work if they adhered to the cock-up theory”. government policy in recent years, post the financial crisis, actually seems designed to ease the pressure on pension schemes and sponsors, although we note that many of the proposed changes impact only on future accrual and not the £1 trillion+ of existing assets and liabilities.
We see a clearer indication of financial repression tactics within the EU and the continued favourable treatment of EU sovereign debt in the Solvency II framework.
For retail savers, unconventional monetary policies post the financial crisis have clearly lead to an erosion of their savings in real terms. However, we believe this is largely a necessary policy reaction to the economy entering into a “balance-sheet recession” where there is potentially a dearth of productive investment and a savings glut.
Whether these financial conditions prove short-lived, or a lasting shift to the so-called “secular stagnation” remains an open question, and this may well depend on demographic developments.
We believe that the link between economic assumptions and demographics – two subjects of key importance to actuaries and their clients – is an important area for future research.