



No CrossRef data available.
Article contents
On Characterizing the Multivariate Linear Exponential Distribution1
Published online by Cambridge University Press: 20 November 2018
Extract
Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.
If x and y are independent p component column vectors, and the conditional distribution of x, given x+y = z, is known, what can be said about the distributions of x and y? This problem has been solved by Seshadri (1966) in the particular case when the conditional distribution of x, given x+y = z, is multivariate normal. In fact Seshadri′s paper implicitly contains a characterization of the multivariate linear exponential distribution
(1)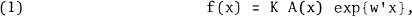
where A(x) is a function of x not involving the p component column vector w of constant terms.
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Canadian Mathematical Society 1969
Footnotes
1
This research work was done while the author held a summer (1967) research fellowship of the Canadian Mathematical Congress.
References
1.
Aczel, J., Lectures on functional equations and their applications. (Academic Press, New York, 1965).Google Scholar
2.
Mathai, A.M., On the structural properties of the conditional distributions. Canad. Math. Bull.
10 (1967) 239–245.Google Scholar
3.
Seshadri, V., A characteristic property of the multi-variate normal distribution. Ann. Math. Statist.
37 (1966) 1829–1831.Google Scholar
 You have Access