



No CrossRef data available.
Article contents
Some Admissible Estimators in Extreme Value Densities
Published online by Cambridge University Press: 20 November 2018
Extract
Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.
Let X be a random variable having the extreme value density of the form
(1)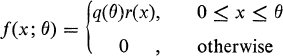
where r is assumed to be a positive Lebesgue measurable function of x and the function q is defined by
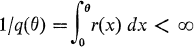
for all θ in Ω = (0, ∞). It is further assumed that q(θ) approaches zero as θ → ∞.
In this note we are concerned with estimating parametric functions g(θ) of the form [1/q(θ)]α, α any real number. The loss function is assumed to be squared error and the estimators are assumed to be functions of a single observation X.
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Canadian Mathematical Society 1975
References
1.
Blyth, C. R., On minimax statistical decision procedures and their admissibility, Ann. Math. Statist.
22 (1951) pp. 22-42.Google Scholar
2.
Blyth, C. R. and Roberts, D. M., On inequalities of Cramer-Rao type and admissibility proofs, Proceedings of the Sixth Berkeley Symposium on Mathematical Statistics and Probability, 1 (1972) pp. 17-30.Google Scholar
3.
Girshick, M. A. and Savage, L. J., Bayes and minimax estimates for quadratic loss functions, Proceedings of the Second Berkeley Symposium on Mathematical Statistics and Probability, 1 (1958) pp. 53-73.Google Scholar
4.
Hodges, J. L. and Lehmann, E.L., Some applications of the Cramer-Rao inequality, Proceedings of the Second Berkeley Symposium on Mathematical Statistics and Probability, 1 (1951) pp. 13-22.Google Scholar
5.
Karlin, S., Admissibility for estimation with quadratic loss, Ann. Math. Statist.
29 (1958) pp. 406-436.Google Scholar
6.
Singh, R., Admissible estimators of θr in some extreme value densities, Can. Math. Bull.
14 (1971) pp. 411-414.Google Scholar
 You have Access