



No CrossRef data available.
Article contents
Random Matrices and Brownian Motion†
Published online by Cambridge University Press: 12 September 2008
Abstract
For T ∈ GLn (Fq), let Ωn (t, T) be the number of irreducible factors of degree less than or equal to nt in the characteristic polynomial of T. Let
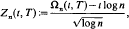
and suppose T is chosen from G Ln(Fq) at random uniformly. We prove that the stochastic process ≺Zn(t)≻t∈[0, 1] converges to the standard Brownian motion process W(t), as n → ∞.
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Cambridge University Press 1993
References
[2]De Laurentis, J. and Pittel, B. (1985) Random permutations and Brownian motion. Pacific Journal of Mathematics 119 287–301.Google Scholar
[3]Gihman, I. I. and Skorohod, A. V. (1974) The theory of stochastic processes, Springer-Verlag.Google Scholar
[4]Goh, W. and Schmutz, E. (1991) A central Limit theorem on G Ln(Fq). Random Structures and Algorithms 2 47–53.CrossRefGoogle Scholar
[5]Graham, R. and Diaconis, P. (1992) Affine walk on the hypercube. Journal of Computational and Applied Mathematics 41 215–235.Google Scholar
[8]Kung, J. (1981) The cycle structure of a linear transformation over a finite field. Linear Algebra Appl. 36 141–155.CrossRefGoogle Scholar
[9]Lidl, R. and Niederreiter, H. (1983) Finite fields. Encyclopedia of Mathematics and its Applications 20, Addison-Wesley Pub.Google Scholar
[10]MacWilliams, F. and Sloane, N. (1981) The theory of error correcting codes, North-Holland, 115.Google Scholar
[11]Stong, R. (1988) Some asymptotic results on finite vector spaces. Advances in Applied Mathematics 9 167–199.CrossRefGoogle Scholar
[12]Whitaker, E. T. and Watson, G. N. (1961) A course of modern analysis, Cambridge University Press, p. 242.Google Scholar
- 4
- Cited by