



No CrossRef data available.
Article contents
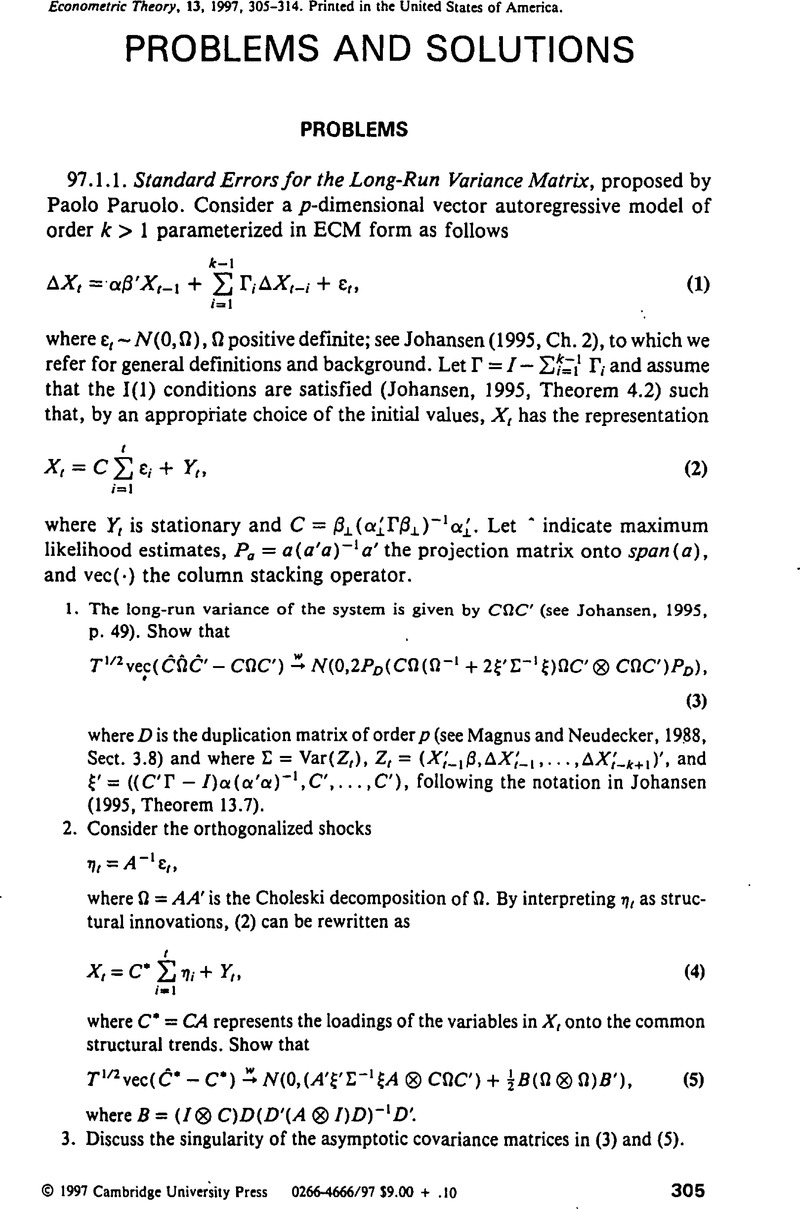
Standard Errors for the Long-Run Variance Matrix
Published online by Cambridge University Press: 11 February 2009
Abstract
An abstract is not available for this content so a preview has been provided. Please use the Get access link above for information on how to access this content.
Information
- Type
- Problems
- Information
- Copyright
- Copyright © Cambridge University Press 1997
References
REFERENCE
Johansen, S. (1995) Likelihood-Based Inference in Cointegrated Vector Autoregressive Models. Oxford: Oxford University Press.CrossRefGoogle Scholar
Magnus, J.R. & Neudecker, H. (1988) Matrix Differential Calculus with Applications in Statistics and Econometrics. Chichester, UK: John Wiley & Sons.Google Scholar
Paruolo, P. (1997) Asymptotic inference on the moving average impact matrix in cointegrated 1(1) VAR systems. Econometric Theory 13, 79–118.CrossRefGoogle Scholar
- 4
- Cited by