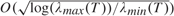Hostname: page-component-7b7567c8c-fvjsw Total loading time: 0 Render date: 2026-11-12T18:32:37.853Z Has data issue: false hasContentIssue false

ALMOST SURE BOUNDS ON THE ESTIMATION ERROR FOR OLS ESTIMATORS WHEN THE REGRESSORS INCLUDE CERTAIN MFI(1) PROCESSES

Published online by Cambridge University Press:  01 April 2009

Dietmar Bauer*
Affiliation:
arsenal research
*
*Address correspondence to Dietmar Bauer, arsenal research, Business Field HCMT, Giefingg. 2, A-1210 Wein; e-mail: Dietmar.Bauer@arsenal.ac.at.
Rights & Permissions [Opens in a new window]

Abstract

Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.

Lai and Wei (1983, Annals of Statistics 10, 154–166) state in their Theorem 1 that the estimators of the regression coefficients in the regression $y_t  = x_t^, t ∈ ℕ are almost surely (a.s.) consistent under the assumption that the minimum eigenvalue λmin(T) of $\sum\nolimits_{t = 1}^T {x_t } x'_t $ tends to infinity (a.s.) and log(λmax(T))/λmin(T) → 0 (a.s.) where λmax(T) denotes the maximal eigenvalue. Moreover the rate of convergence in this case equals $O(\root  \of {\log (\lambda _{max} (T))/\lambda _{min} (T)})$. In this note xt is taken to be a particular multivariate multifrequency I(1) processes, and almost sure rates of convergence for least squares estimators are established.

Information

Type
Notes and Problems
Copyright
Copyright © Cambridge University Press 2009