


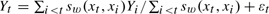 , t = 2, …, n, where s


Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Gilboa, Itzhak
Lieberman, Offer
and
Schmeidler, David
2011.
A similarity-based approach to prediction.
Journal of Econometrics,
Vol. 162,
Issue. 1,
p.
124.
Teitelbaum, Joshua C.
2012.
Lieberman, Offer
2012.
A similarity‐based approach to time‐varying coefficient non‐stationary autoregression.
Journal of Time Series Analysis,
Vol. 33,
Issue. 3,
p.
484.
Lieberman, Offer
and
Phillips, Peter C. B.
2013.
Teitelbaum, Joshua C.
2013.
Teitelbaum, Joshua C.
2013.
Asymmetric empirical similarity.
Mathematical Social Sciences,
Vol. 66,
Issue. 3,
p.
346.
Golosnoy, Vasyl
Hamid, Alain
and
Okhrin, Yarema
2014.
The empirical similarity approach for volatility prediction.
Journal of Banking & Finance,
Vol. 40,
Issue. ,
p.
321.
Lieberman, Offer
and
Phillips, Peter C. B.
2014.
A Multivariate Stochastic Unit Root Model with an Application to Derivative Pricing.
SSRN Electronic Journal,
Bordley, Robert F.
2014.
Reference Class Forecasting: Resolving Its Challenge to Statistical Modeling.
The American Statistician,
Vol. 68,
Issue. 4,
p.
221.
Lieberman, Offer
and
Phillips, Peter C. B.
2014.
NORMING RATES AND LIMIT THEORY FOR SOME TIME‐VARYING COEFFICIENT AUTOREGRESSIONS.
Journal of Time Series Analysis,
Vol. 35,
Issue. 6,
p.
592.
Kapetanios, George
Mitchell, James
and
Shin, Yongcheol
2014.
A nonlinear panel data model of cross-sectional dependence.
Journal of Econometrics,
Vol. 179,
Issue. 2,
p.
134.
Kinjo, Keita
and
Sugawara, Shinya
2015.
Hamid, Alain
and
Heiden, Moritz
2015.
Forecasting volatility with empirical similarity and Google Trends.
Journal of Economic Behavior & Organization,
Vol. 117,
Issue. ,
p.
62.
Teitelbaum, J. C.
2015.
Analogical Legal Reasoning: Theory and Evidence.
American Law and Economics Review,
Vol. 17,
Issue. 1,
p.
160.
Melo, Oscar O.
Melo, Carlos E.
and
Mateu, Jorge
2015.
Distance-based beta regression for prediction of mutual funds.
AStA Advances in Statistical Analysis,
Vol. 99,
Issue. 1,
p.
83.
Hamid, Alain
2015.
Prediction power of high-frequency based volatility measures: a model based approach.
Review of Managerial Science,
Vol. 9,
Issue. 3,
p.
549.
Golosnoy, Vasyl
and
Pape, Markus
2016.
How Much Would Banks Pay?.
SSRN Electronic Journal ,
Kinjo, Keita
and
Sugawara, Shinya
2016.
Predicting Empirical Patterns in Viewing Japanese TV Dramas Using Case-Based Decision Theory.
The B.E. Journal of Theoretical Economics,
Vol. 16,
Issue. 2,
Lieberman, Offer
and
Phillips, Peter C.B.
2017.
A multivariate stochastic unit root model with an application to derivative pricing.
Journal of Econometrics,
Vol. 196,
Issue. 1,
p.
99.
Argenziano, Rossella
and
Gilboa, Itzhak
2018.
Second-Order Induction: Uniqueness and Complexity.
SSRN Electronic Journal ,