
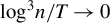

Hostname: page-component-7b7567c8c-wxvwp Total loading time: 0 Render date: 2026-11-17T01:58:51.209Z Has data issue: false hasContentIssue false

ESTIMATION OF THE KRONECKER COVARIANCE MODEL BY QUADRATIC FORM

Published online by Cambridge University Press:  17 December 2020

Oliver B. Linton
Affiliation:
University of Cambridge
Haihan Tang*
Affiliation:
Fudan University
*
Address correspondence to Haihan Tang, Fanhai International School of Finance, Fudan University, 220 Handan Road, Yangpu District, Shanghai, 200433, China; e-mail: hhtang@fudan.edu.cn.
Rights & Permissions [Opens in a new window]

Abstract

Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.

We propose a new estimator, the quadratic form estimator, of the Kronecker product model for covariance matrices. We show that this estimator has good properties in the large dimensional case (i.e., the cross-sectional dimension n is large relative to the sample size T). In particular, the quadratic form estimator is consistent in a relative Frobenius norm sense provided ${\log }^3n/T\to 0$. We obtain the limiting distributions of the Lagrange multiplier and Wald tests under both the null and local alternatives concerning the mean vector $\mu $. Testing linear restrictions of $\mu $ is also investigated. Finally, our methodology is shown to perform well in finite sample situations both when the Kronecker product model is true and when it is not true.

Information

Type
ARTICLES
Copyright
© The Author(s), 2020. Published by Cambridge University Press