


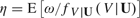 , where the conditional density of a scalar continuous random variable V, given a random vector
 , is replaced by its kernel estimator. That is, the parameter η is the expectation of ω inversely weighted by
 , and it is the building block of various semiparametric estimators already proposed in the literature such as Lewbel (1998), Lewbel (2000b), Honoré and Lewbel (2002), Khan and Lewbel (2007), and Lewbel (2007). The optimal bandwidth is derived by minimizing the leading terms of a second-order mean squared error expansion of an in-probability approximation of the resulting estimator with respect to h. The expansion also demonstrates that the bandwidth can be chosen on the basis of bias alone, and that a simple “plug-in” estimator for the optimal bandwidth can be constructed. Finally, the small sample performance of our proposed estimator of the optimal bandwidth is assessed by a Monte Carlo experiment.


Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Hamilton, James D.
and
Monteagudo Pujalte, Josefa
1998.
Bravo, Francesco
and
Jacho-Chávez, David T.
2010.
Empirical Likelihood for Efficient Semiparametric Average Treatment Effects.
Econometric Reviews,
Vol. 30,
Issue. 1,
p.
1.
Chu, Ba
and
Jacho-Chávez, David T.
2012.
k-NEAREST NEIGHBOR ESTIMATION OF INVERSE-DENSITY-WEIGHTED EXPECTATIONS WITH DEPENDENT DATA.
Econometric Theory,
Vol. 28,
Issue. 4,
p.
769.
Carrasco, Marine
and
Kotchoni, Rachidi
2013.
Efficient Estimation Using the Characteristic Function.
SSRN Electronic Journal,
Carrasco, Marine
and
Kotchoni, Rachidi
2017.
EFFICIENT ESTIMATION USING THE CHARACTERISTIC FUNCTION.
Econometric Theory,
Vol. 33,
Issue. 2,
p.
479.