


No CrossRef data available.
Article contents
Fast deterministic pricing of optionson Lévy driven assets
Published online by Cambridge University Press: 15 February 2004
Abstract
Arbitrage-free prices u of European contracts on risky assets whoselog-returns are modelled by Lévy processes satisfya parabolic partial integro-differential equation (PIDE) $\partial_t u + {\mathcal{A}}[u] = 0$ 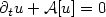 .This PIDE is localized tobounded domains and the error due to this localization isestimated. The localized PIDE is discretized by theθ-scheme in time and a wavelet Galerkin method with N degrees of freedom in log-price space. The dense matrix for ${\mathcal{A}}$
 can be replaced by a sparse matrix in the wavelet basis, and the linear systemsin each implicit time step are solved approximativelywith GMRES in linear complexity. The total work of the algorithm for M time steps is bounded byO(MN(log(N))2) operations and O(Nlog(N)) memory.The deterministic algorithm gives optimal convergence rates (up to logarithmic terms) for the computed solutionin the same complexity as finite difference approximationsof the standard Black–Scholes equation.Computational examples for various Lévy price processes are presented.
Keywords
Information
- Type
- Research Article
- Information
- ESAIM: Mathematical Modelling and Numerical Analysis , Volume 38 , Issue 1 , January 2004 , pp. 37 - 71
- Copyright
- © EDP Sciences, SMAI, 2004
References
R.A. Adams, Sobolev Spaces. Academic Press, New York (1978).
H. Amann, Linear and Quasilinear Parabolic Problems, Vol. I: Abstract Linear Theory, Monographs Math. Birkhäuser, Basel 89 (1995).
Barndorff-Nielsen, O.E., Exponentially decreasing distributions for the logarithm of particle size.
Proc. Roy. Soc. London A
353 (1977) 401–419.
CrossRef
Barndorff-Nielsen, O.E., Normal inverse Gaussian distributions and stochastic volatility modelling.
Scand. J. Statis.
24 (1997) 1–14.
CrossRef
Barndorff-Nielsen, O.E. and Shepard, N., Non-Gaussian Ornstein-Uhlenbeck based models and some of their uses in financial economics.
J. Roy. Stat. Soc. B
63 (2001) 167–241.
CrossRef
A. Bensoussan and J.-L. Lions, Impulse control and quasi-variational inequalities. Gauthier-Villars, Paris (1984).
J. Bertoin, Lévy processes. Cambridge University Press (1996).
Black, F. and Scholes, M., The Pricing of Options and Corporate Liabilities.
J. Political Economy
81 (1973) 637–654.
CrossRef
Boyarchenko, S. and Levendorski, S., Barrier options and touch-and-out options under regular Lévy processes of exponential type.
Ann. Appl. Probab.
12 (2002) 1261–1298.
Boyarchenko, S. and Levendorski, S., Option pricing for truncated Lévy processes.
Int. J. Theor. Appl. Finance
3 (2000) 549-552.
CrossRef
Carr, P., Geman, H., Madan, D.B. and Yor, M., The fine structure of asset returns: an empirical investigation.
J. Business
75 (2002) 305–332.
CrossRef
Chan, T., Pricing contingent claims on stocks driven by Lévy processes.
Ann. Appl. Probab.
9 (1999) 504–528.
A. Cohen, Wavelet methods for operator equations, P.G. Ciarlet and J.L. Lions Eds., Elsevier, Amsterdam, Handb. Numer. Anal.
VII (2000).
R. Cont and P. Tankov, Financial modelling with jump processes. Chapman and Hall/CRC Press (2003).
Delbaen, F. and Schachermayer, W., The variance-optimal martingale measure for continuous processes.
Bernoulli
2 (1996) 81–105.
CrossRef
Delbaen, F., Grandits, P., Rheinländer, T., Samperi, D., Schweizer, M. and Stricker, C., Exponential hedging and entropic penalties.
Math. Finance
12 (2002) 99–123.
CrossRef
E. Eberlein, Application of generalized hyperbolic Lévy motions to finance, in Lévy Processes: Theory and Applications, O.E. Barndorff-Nielsen, T. Mikosch and S. Resnick Eds., Birkhäuser (2001) 319–337.
H. Föllmer and M. Schweizer, Hedging of contingent claims under incomplete information, in Applied Stochastic Analysis, M.H.A. Davis and R.J. Elliot Eds., Gordon and Breach New York (1991) 389–414.
J. Jacod and A.N. Shiryaev, Limit Theorems for Stochastic Processes. Springer-Verlag, Berlin (1987).
Jaillet, P., Lamberton, D. and Lapeyre, B., Variational inequalities and the pricing of American options.
Acta Appl. Math.
21 (1990) 263–289.
CrossRef
Kangro, R. and Nicolaides, R., Far field boundary conditions for Black–Scholes equations.
SIAM J. Numer. Anal.
38 (2000) 1357–1368.
CrossRef
I. Karatzas and S.E. Shreve, Methods of Mathematical Finance. Springer-Verlag (1999).
D. Lamberton and B. Lapeyre, Introduction to Stochastic Calculus Applied to Finance. Chapman & Hall (1997).
J.L. Lions and E. Magenes, Non-homogeneous boundary value problems and applications. Springer-Verlag, Berlin (1972).
Madan, D.B. and Seneta, E., The variance gamma (V.G.) model for share market returns.
J. Business
63 (1990) 511–524.
CrossRef
Madan, D.B., Carr, P. and Chang, E., The variance gamma process and option pricing.
Eur. Finance Rev.
2 (1998) 79–105.
CrossRef
A.M. Matache, T. von Petersdorff and C. Schwab, Fast deterministic pricing of options on Lévy driven assets. Report 2002-11, Seminar for Applied Mathematics, ETH Zürich. http://www.sam.math.ethz.ch/reports/details/include.shtml?2002/2002-11.html
A.M. Matache, P.A. Nitsche and C. Schwab, Wavelet Galerkin pricing of American options on Lévy driven assets. Research Report 2003-06, Seminar for Applied Mathematics, ETH Zürich, http://www.sam.math.ethz.ch/reports/details/include.shtml?2003/2003-06.html
Merton, R.C., Option pricing when the underlying stocks are discontinuous.
J. Financ. Econ.
5 (1976) 125–144.
CrossRef
Nualart, D. and Schoutens, W., Backward stochastic differential equations and Feynman-Kac formula for Lévy processes, with applications in finance.
Bernoulli
7 (2001) 761–776.
CrossRef
A. Pazy, Semigroups of linear operators and applications to partial differential equations. Appl. Math. Sci. Springer-Verlag, New York 44 (1983).
T. von Petersdorff and C. Schwab, Fully discrete multiscale Galerkin BEM, in Multiresolution Analysis and Partial Differential Equations, W. Dahmen, P. Kurdila and P. Oswald Eds., Academic Press, New York, Wavelet Anal. Appl.
6 (1997) 287–346.
K. Prause, The Generalized Hyperbolic Model: Estimation, Financial Derivatives, and Risk Measures. Ph.D. thesis Albert-Ludwigs-Universität Freiburg i.Br. (1999).
P. Protter, Stochastic Integration and Differential Equations. Springer-Verlag (1990).
S. Raible, Lévy processes in Finance: Theory, Numerics, and Empirical Facts. Ph.D. thesis Albert-Ludwigs-Universität Freiburg i.Br. (2000).
K.-I. Sato, Lévy Processes and Infinitely Divisible Distributions. Cambridge University Press (1999).
Schötzau, D. and Schwab, C., hp-discontinuous Galerkin time-stepping for parabolic problems.
C.R. Acad. Sci. Paris
333 (2001) 1121–1126.
CrossRef
W. Schoutens, Lévy Processes in Finance. Wiley Ser. Probab. Stat., Wiley Publ. (2003).
von Petersdorff, T. and Schwab, C., Wavelet-discretizations of parabolic integro-differential equations.
SIAM J. Numer. Anal.
41 (2003) 159–180.
CrossRef
T. von Petersdorff and C. Schwab, Numerical solution of parabolic equations in high dimensions. Report NI03013-CPD, Isaac Newton Institute for the Mathematical Sciences, Cambridge, UK (2003), http://www.newton.cam.ac.uk/preprints2003.html, ESAIM: M2AN
38 (2004) 93–127.
X. Zhang, Analyse Numerique des Options Américaines dans un Modèle de Diffusion avec Sauts. Ph.D. thesis, École Normale des Ponts et Chaussées (1994).
- 94
- Cited by