



No CrossRef data available.
Article contents
Estimation of the hazard function in a semiparametric model with covariate measurement error
Published online by Cambridge University Press: 26 March 2009
Abstract
We consider a failure hazard function,conditional on a time-independent covariate Z,given by $\eta_{\gamma^0}(t)f_{\beta^0}(Z)$  . The baseline hazardfunction $\eta_{\gamma^0}$
 and the relative risk $f_{\beta^0}$
 both belong to parametricfamilies with $\theta^0=(\beta^0,\gamma^0)^\top\in \mathbb{R}^{m+p}$
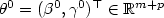 . The covariate Z has an unknown density and is measured with an error through anadditive error model U = Z + ε where ε is a random variable, independent from Z, withknown density $f_\varepsilon$
 .We observe a n-sample (Xi, Di, Ui), i = 1, ..., n, where X i isthe minimum between the failure time and the censoring time,and D i is the censoring indicator.Using least square criterion and deconvolution methods, we propose a consistent estimator of θ 0 using the observationsn-sample (Xi, Di, Ui), i = 1, ..., n.
We give an upper bound for its riskwhich depends on the smoothness properties of $f_\varepsilon$ and $f_\beta(z)$
 as afunction of z, and we derive sufficient conditionsfor the $\sqrt{n}$
 -consistency.We give detailed examples consideringvarious type of relative risks $f_{\beta}$
 and various types of errordensity $f_\varepsilon$ . In particular, in the Cox model and inthe excess risk model, the estimator of θ 0 is $\sqrt{n}$ -consistent and asymptotically Gaussianregardless of the form of $f_\varepsilon$ .
Keywords
Information
- Type
- Research Article
- Information
- Copyright
- © EDP Sciences, SMAI, 2009
References
M. Aitkin and D. Clayton, The fitting of exponential, Weibull and extreme value distributions to complex censored survival data using GLIM. J. R. Stat. Soc., Ser. C
29 (1980) 156–163.
P.K. Andersen, O. Borgan, R.D. Gill and N. Keiding, Statistical models based on counting processes. Springer Series in Statistics (1993).
Augustin, T., An exact corrected log-likelihood function for Cox's proportional hazards model under measurement error and some extensions.
Scand. J. Stat.
31 (2004) 43–50.
CrossRef
Borgan, Ø., Correction to: Maximum likelihood estimation in parametric counting process models, with applications to censored failure time data.
Scand. J. Statist.
11 (1984) 275.
Ø. Borgan, Maximum likelihood estimation in parametric counting process models, with applications to censored failure time data. Scand. J. Stat., Theory Appl.
11 (1984) 1–16.
C. Butucea and M.-L. Taupin, New M-estimators in semiparametric regression with errors in variables. Ann. Inst. Henri Poincaré: Probab. Stat. (to appear).
J.S. Buzas, Unbiased scores in proportional hazards regression with covariate measurement error. J. Statist. Plann. Inference, 67 (1998) 247–257.
R.J. Carroll, D. Ruppert, and L.A. Stefanski, Measurement error in nonlinear models. Chapman and Hall (1995).
Comte, F. and Taupin, M.-L., Nonparametric estimation of the regression function in an errors-in-variables model.
Statistica Sinica
17 (2007) 1065–1090.
D.R. Cox and D. Oakes, Analysis of survival data. Monographs on Statistics and Applied Probability. Chapman and Hall (1984).
Fan, J. and Truong, Y.K., Nonparametric regression with errors in variables.
Ann. Statist.
21 (1993) 1900–1925.
CrossRef
M.V. Fedoryuk, Asimptotika: integraly i ryady. Asymptotics: Integrals and Series (1987).
W.A. Fuller, Measurement error models. Wiley Series in Probability and Mathematical Statistics (1987).
Gill, R.D. and Andersen, P.K., Cox's regression model for counting processes: a large sample study.
Ann. Statist.
10 (1982) 1100–1120.
Gong, G., Whittemore, A.S. and Grosser, S., Censored survival data with misclassified covariates: A case study of breast-cancer mortality.
J. Amer. Statist. Assoc.
85 (1990) 20–28.
CrossRef
Hjort, N.L., On inference in parametric survival data models.
Int. Stat. Rev.
60 (1992) 355–387.
CrossRef
D.W.J. Hosmer and S. Lemeshow, Applied survival analysis. Regression modeling of time to event data. Wiley Series in Probability and Mathematical Statistics (1999).
Hu, C. and Lin, D.Y., Semiparametric failure time regression with replicates of mismeasured covariates.
J. Am. Stat. Assoc.
99 (2004) 105–118.
CrossRef
Hu, C. and Lin, D.Y., Cox regression with covariate measurement error.
Scand. J. Stat.
29 (2002) 637–655.
CrossRef
Huang, Y. and Wang, C.Y., Cox regression with accurate covariates unascertainable: A nonparametric-correction approach.
J. Am. Stat. Assoc.
95 (2000) 1209–1219.
CrossRef
Kiefer, J. and Wolfowitz, J., Consistency of the maximum likelihood estimator in the presence of infinitely many nuisance parameters.
Ann. Math. Statist.
27 (1956) 887–906.
CrossRef
Kong, F.H., Adjusting regression attenuation in the Cox proportional hazards model.
J. Statist. Plann. Inference
79 (1999) 31–44.
CrossRef
Kong, F.H. and Consistent, M. Gu estimation in Cox proportional hazards model with covariate measurement errors.
Statistica Sinica
9 (1999) 953–969.
Lepski, O.V. and Levit, B.Y., Adaptive minimax estimation of infinitely differentiable functions.
Math. Methods Statist.
7 (1998) 123–156.
Li, Y. and Ryan, L., Survival analysis with heterogeneous covariate measurement error.
J. Amer. Statist. Assoc.
99 (2004) 724-735.
CrossRef
Li, Y. and Ryan, L., Inference on survival data with covariate measurement error – An imputation-based approach.
Scand. J. Stat.
33 (2006) 169–190.
CrossRef
Martin-Magniette, M.-L., Nonparametric estimation of the hazard function by using a model selection method: estimation of cancer deaths in Hiroshima atomic bomb survivors.
J. Roy. Statist. Soc. Ser. C
54 (2005) 317–331.
CrossRef
Nakamura, T., Corrected score function for errors-in-variables models: methodology and application to generalized linear models.
Biometrika
77 (1990) 127–137.
CrossRef
Nakamura, T., Proportional hazards model with covariates subject to measurement error.
Biometrics
48 (1992) 829-838.
CrossRef
Prentice, R.L., Covariate measurement errors and parameter estimation in a failure time regression model.
Biometrika
69 (1982) 331–342.
CrossRef
Prentice, R.L. and Self, S.G., Asymptotic distribution theory for Cox-type regression models with general relative risk form.
Ann. Statist.
11 (1983) 804–813.
CrossRef
Reiersøl, O., Identifiability of a linear relation between variables which are subject to error.
Econometrica
18 (1950) 375-389.
CrossRef
Reynaud-Bouret, P., Adaptive estimation of the intensity of inhomogeneous Poisson processes via concentration inequalities.
Prob. Theory Relat. Fields
126 (2003) 103–153.
CrossRef
Stefanski, L.A., Unbiaised estimation of a nonlinear function of a normal mean with application to measurement error models.
Commun. Stat. -Theory Meth.
18 (1989) 4335–4358.
CrossRef
Taupin, M.-L., Semi-parametric estimation in the nonlinear structural errors-in-variables model.
Ann. Statist.
29 (2001) 66–93.
CrossRef
T.T. Tsiatis, V. DeGruttola and M.S. Wulfsohn, Modeling the relationship of survival to longitudinal data measured with error. Application to survival and cd4 counts in patients with aids. J. Amer. Statist. Assoc.
90 (1995) 27–37.
Tyurin, Y.N., Yakovlev, A., Shi, J. and Bass, L., Testing a model of aging in animal experiments.
Biometrics
51 (1995) 363–372.
CrossRef
A.W. van der Vaart and J.A. Wellner, Weak convergences and empirical processes. With applications to statistics. Springer Series in Statistics (1996).
S.X. Xie, C.Y. Wang and R.L. Prentice, A risk set calibration method for failure time regression by using a covariate reliability sample. J.R. Stat. Soc., Ser. B, Stat. Methodol.
63 (2001) 855–870.