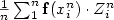
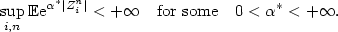

Hostname: page-component-7b7567c8c-fvjsw Total loading time: 0 Render date: 2026-11-17T04:21:33.387Z Has data issue: false hasContentIssue false

Large deviations for independent random variables – Application to Erdös-Renyi's functional law of large numbers

Published online by Cambridge University Press:  15 November 2005

Jamal Najim*
Affiliation:
CNRS, École Nationale Supérieure des Télécommunications, 46 rue Barrault 75634 Paris Cedex 13, France; najim@tsi.enst.fr
Get access

Abstract

A Large Deviation Principle (LDP) is proved for the family $\frac{1}{n}\sum_1^n\mathbf{f}(x_i^n) \cdot Z^n_i$ where the deterministic probability measure $\frac{1}{n}\sum_1^n \delta_{x_i^n}$ converges weakly to a probability measure R and $(Z^n_i)_{i\in \mathbb{N}}$ are $\mathbb{R}^d$ -valued independent random variables whose distribution depends on $x_i^n$ and satisfies the following exponential moments condition: $$ \sup_{i,n} {\mathbb E}{\rm e}^{\alpha^* |Z_i^n|}< +\infty \quad\textrm{for some}\quad 0<\alpha^*<+\infty.$$

In this context, the identification of the rate function is non-trivial due to the absence of equidistribution. We rely on fine convex analysis to address this issue. Among the applications of this result, we extend Erdös and Rényi's functional law of large numbers.

Information

Type
Research Article
Copyright
© EDP Sciences, SMAI, 2005

Access options

Get access to the full version of this content by using one of the access options below. (Log in options will check for institutional or personal access. Content may require purchase if you do not have access.)

Article purchase

Temporarily unavailable