




No CrossRef data available.
Article contents
Optional splitting formula in a progressively enlargedfiltration
Published online by Cambridge University Press: 29 October 2014
Abstract
Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.
Let \hbox{$\mathbb{F}^{}_{}$} be a filtration and τ be a random time. Let \hbox{$\mathbb{G}^{}_{}$}
 be the progressive enlargement of \hbox{$\mathbb{F}^{}_{}$} with τ. We study the following formula, called the optional splitting formula: For any \hbox{$\mathbb{G}^{}_{}$}-optional process Y, there exists an \hbox{$\mathbb{F}^{}_{}$}-optional process Y′ and a function Y′′ defined on [0,∞] × (ℝ+ × Ω) being \hbox{$\mathcal{B}[0,\infty]\otimes\mathcal{O}(\mathbb{F}^{}_{})$}
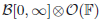 measurable, such that \hbox{$Y=Y'\mathds{1}^{}_{[0,\tau)}+Y''(\tau)\mathbb{1}^{}_{[\tau,\infty)}.$}
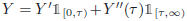 (This formula can also be formulated for multiple random times τ1,...,τk). We are interested in this formula because of its fundamental role in many recent papers on credit risk modeling, and also because of the fact that its validity is limited in scope and this limitation is not sufficiently underlined. In this paper we will determine the circumstances in which the optional splitting formula is valid. We will then develop practical sufficient conditions for that validity. Incidentally, our results reveal a close relationship between the optional splitting formula and several measurability questions encountered in credit risk modeling. That relationship allows us to provide simple answers to these questions.
Keywords
Information
- Type
- Research Article
- Information
- Copyright
- © EDP Sciences, SMAI 2014
References
Barlow, M., Study of a filtration expanded to include an honest time. Probab. Theory Relat. Fields 44 (1978) 307–323. Google Scholar
M. Barlow, M. Emery, F. Knight, S. Song and M. Yor, Autour d’un théorème de Tsirelson sur des filtrations browniennes et non browniennes. Séminaire de Probabilité, XXXII. Springer-Verlag Berlin (1998).
M. Barlow and J. Pitman and M. Yor, On Walsh’s Brownian motion. Séminaire de Probabilité, XXIII. Springer-Verlag Berlin (1989)
A. Bélanger and S. Shreve and D. Wong, A unified model for credit derivatives. Working paper (2002).
Biagini, F. and Cretarola, A., Local risk-minimization for defaultable claims with recovery process. Appl. Math. Optim. 65 (2012) 293–314. Google Scholar
T. Bielecki and M. Jeanblanc and M. Rutkowski, Credit Risk Modelling. Osaka University Press (2009).
P. Billingsley, Convergence of probability measures. John Wiley & Sons (1968).
Brémaud, P. and Yor, M., Changes of filtrations and of probability measures. Prob. Theory Relat. Fields 4 (1978) 269–295. Google Scholar
Callegaro, G. and Jeanblanc, M. and Zargari, B., Carthaginian enlargement of filtrations. ESAIM: PS 17 (2013) 550–566. Google Scholar
L. Chaumont and M. Yor, Exercises in probability: a guide tour from measure theory to random processes, via conditioning. Cambridge University Press (2009).
C. Dellacherie and M. Emery, Filtrations indexed by ordinals; application to a conjecture of S. Laurent. Working paper (2012).
C. Dellacherie and P. Meyer, Probabilités et potentiel Chapitres I à IV. Hermann Paris (1975).
C. Dellacherie and P. Meyer, Probabilités et potentiel Chapitres XVII à XXIV. Hermann Paris (1992).
Karoui, N. El. and Jeanblanc, M. and Jiao, Y., What happens after a default: the conditional density approach. Stoch. Process. Appl. 120 (2010) 1011–1032. Google Scholar
M. Emery and W. Schachermayer, A remark on Tsirelson’s stochastic differential equation. Séminaire de Probabilités XXXIII, Springer-Verlag Berlin (1999) 291–303.
M. Emery and W. Schachermayer, On Vershik’s standardness criterion and Tsirelson’s notion of cosiness. Séminaire de Probabilités XXXV. Springer (2001) 265–305.
Fontana, C. and Jeanblanc, M. and Song, S., On arbitrages arising with honest times. Finance Stoch. 18 (2014) 515–543. Google Scholar
R. Handel On the exchange of intersection and supremum of σ-fields in filtering theory. Israel J. Math. 192 (2012) 763.
S.W. He and J.G. Wang and J.A. Yan, Semimartingale Theory And Stochastic Calculus. Science Press CRC Press Inc (1992).
M. Jeanblanc and M. Rutkowski, Modeling default risk: an overview Math. Finance: Theory and Practice. Fudan University High Education Press (1999).
Jeanblanc, M. and Song, S., An explicit model of default time with given survival probability. Stoch. Process. Appl. 121 (2010) 1678–1704. Google Scholar
Jeanblanc, M. and Song, S., Random times with given survival probability and their F-martingale decomposition formula. Stoch. Process. Appl. 121 (2010) 1389–1410. Google Scholar
M. Jeanblanc and S. Song, Martingale representation theorem in progressively enlarged filtrations (2012). Preprint arXiv:1203.1447.
M. Jeanblanc and Y. LeCam, Reduced form modelling for credit risk (2008). Available on: defaultrisk.com
T. Jeulin Semi-martingales et grossissement d’une filtration, vol. 833 of Lect. Notes Math. Springer (1980).
T. Jeulin and M. Yor, Grossissement d’une filtration and semi-martingales: formules explicites. Séminaire de Probabilités XII (1978) 78–97.
Y. Jiao, Multiple defaults and contagion risks with global and default-free information. Working paper (2010).
I. Kharroubi and T. Lim, Progressive enlargement of filtrations and backward SDEs with jumps. Working paper (2011).
A. Nikeghbali and E. Platen, On honest times in financial modeling (2008). Preprint arXiv:0808.2892.
Pham, H., Stochastic control under progressive enlargement of filtrations and applications to multiple defaults risk management. Stoch. Process. Appl. 120 (2010) 1795–1820. Google Scholar
Ph. Protter, Stochastic integration and differential equations, 2nd edition. Springer (2004).
L. Rogers and D. Williams, Diffusions, Markov Processes, and Martingales, vol. 1, Foundations. John Wiley and Sons (1994).
S. Song, Grossissement d’une filtration et problèmes connexes. Thesis Université Paris IV (1987).
S. Song, Drift operator in a market affected by the expansion of information flow: a case study (2012). Preprint arXiv:1207.1662v1.
S. Song, Local solution method for the problem of enlargement of filtration (2013). Preprint arXiv:1302.2862.
Stricker, C. and Yor, M., Calcul stochastique dépendant d’un paramètre. Probab. Theory Relat. Fields 45 (1978) 109–133. Google Scholar
von Weizsäcker, H., Exchanging the order of taking suprema and countable intersections of σ-algebras. Ann. Inst. Henri Poincaré Section B, Tome 19 1 (1983) 91–100. Google Scholar
D. Wu, Dynamized copulas and applications to counterparty credit risk. Ph.D. Thesis, University of Evry (2012).
K. Yano and M. Yor, Around Tsirelson’s equation, or: The evolution process may not explain everything (2010). Preprint arXiv:0906.3442.
 You have
Access
- 18
- Cited by