


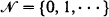 . For k < i < j, let H = {k + 1, ···, j − 1} and let
 . These conditional passage times are studied through first-passage times of a modified chain
 of states absorbing. It will be shown that the densities of
 and
 is also discussed, where
 , and
 are conditional passage times of the reversed process of X(t).

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Kijima, Masaaki
1990.
ON THE UNIMODALITY OF TRANSITION PROBABILITIES IN MARKOV CHAINS.
Australian Journal of Statistics,
Vol. 32,
Issue. 1,
p.
1.
Di Crescenzo, Antonio
1998.
First-passage-time densities and avoiding probabilities for birth-and-death processes with symmetric sample paths.
Journal of Applied Probability,
Vol. 35,
Issue. 2,
p.
383.
Keller, Peter
Rœlly, Sylvie
and
Valleriani, Angelo
2015.
On Time Duality for Markov Chains.
Stochastic Models,
Vol. 31,
Issue. 1,
p.
98.