


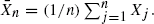 Under some mild regularity conditions on r(n) and the condition that r(n)lnn = o(1) or (r(n)lnn)
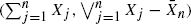 is obtained. Continuous-time results are also presented as well as a tube formula tail area approximation to the joint distribution of the sum and maximum.

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
McCormick, W. P.
and
Qi, Y.
2000.
Asymptotic distribution for the sum and maximum of Gaussian processes.
Journal of Applied Probability,
Vol. 37,
Issue. 4,
p.
958.
McCormick, W. P.
and
Qi, Y.
2000.
Asymptotic distribution for the sum and maximum of Gaussian processes.
Journal of Applied Probability,
Vol. 37,
Issue. 04,
p.
958.
James, Barry
James, Kang
and
Qi, Yongcheng
2007.
Limit distribution of the sum and maximum from multivariate Gaussian sequences.
Journal of Multivariate Analysis,
Vol. 98,
Issue. 3,
p.
517.
Hu, Aiping
Peng, Zuoxiang
and
Qi, Yongcheng
2009.
Joint behavior of point process of exceedances and partial sum from a Gaussian sequence.
Metrika,
Vol. 70,
Issue. 3,
p.
279.
Nowack, K. C.
Shafiei, M.
Laforest, M.
Prawiroatmodjo, G. E. D. K.
Schreiber, L. R.
Reichl, C.
Wegscheider, W.
and
Vandersypen, L. M. K.
2011.
Single-Shot Correlations and Two-Qubit Gate of Solid-State Spins.
Science,
Vol. 333,
Issue. 6047,
p.
1269.
Tan, Zhongquan
and
Wang, Yuebao
2011.
Almost sure central limit theorem for the maxima and sums of stationary Gaussian sequences.
Journal of the Korean Statistical Society,
Vol. 40,
Issue. 3,
p.
347.
Tan, Zhong-quan
and
Peng, Zuo-xiang
2011.
Joint asymptotic distribution of exceedances point process and partial sum of stationary Gaussian sequence.
Applied Mathematics-A Journal of Chinese Universities,
Vol. 26,
Issue. 3,
p.
319.
Peng, Zuo Xiang
Tong, Jin Jun
and
Weng, Zhi Chao
2012.
Joint limit distributions of exceedances point processes and partial sums of gaussian vector sequence.
Acta Mathematica Sinica, English Series,
Vol. 28,
Issue. 8,
p.
1647.
Tan, Zhongquan
Hashorva, Enkelejd
and
Peng, Zuoxiang
2012.
Asymptotics of Maxima of Strongly Dependent Gaussian Processes.
Journal of Applied Probability,
Vol. 49,
Issue. 04,
p.
1106.
PENG, ZUOXIANG
TONG, BIN
and
NADARAJAH, SARALEES
2012.
ALMOST SURE CENTRAL LIMIT THEOREMS OF THE PARTIAL SUMS AND MAXIMA FROM COMPLETE AND INCOMPLETE SAMPLES OF STATIONARY SEQUENCES.
Stochastics and Dynamics,
Vol. 12,
Issue. 03,
p.
1150026.
Tan, Zhongquan
and
Hashorva, Enkelejd
2013.
Exact tail asymptotics of the supremum of strongly dependent Gaussian processes over a random interval.
Lithuanian Mathematical Journal,
Vol. 53,
Issue. 1,
p.
91.
Tan, Zhongquan
and
Wang, Yuebao
2013.
Extremes Values of Discrete and Continuous Time Strongly Dependent Gaussian Processes.
Communications in Statistics - Theory and Methods,
Vol. 42,
Issue. 13,
p.
2451.
Tan, Zhongquan
and
Tang, Linjun
2014.
The dependence of extreme values of discrete and continuous time strongly dependent Gaussian processes.
Stochastics,
Vol. 86,
Issue. 1,
p.
60.
Hwang, Eunju
2014.
The stationary bootstrap for the joint distribution of sum and maximum of stationary sequences.
Journal of the Korean Statistical Society,
Vol. 43,
Issue. 2,
p.
225.
Tan, Zhongquan
and
Hashorva, Enkelejd
2014.
On Piterbarg Max-Discretisation Theorem for Standardised Maximum of Stationary Gaussian Processes.
Methodology and Computing in Applied Probability,
Vol. 16,
Issue. 1,
p.
169.
Chen, Yang
and
Tan, Zhongquan
2016.
Maxima and sum for discrete and continuous time Gaussian processes.
Frontiers of Mathematics in China,
Vol. 11,
Issue. 1,
p.
27.
Tan, Zhongquan
and
Tang, Linjun
2017.
On the maxima and sums of homogeneous Gaussian random fields.
Statistics & Probability Letters,
Vol. 125,
Issue. ,
p.
44.
Tan, Zhongquan
2018.
Asymptotics of maxima and sums for a type of strongly dependent isotropic Gaussian random fields.
Communications in Statistics - Theory and Methods,
Vol. 47,
Issue. 20,
p.
5013.
He, Yinqiu
Xu, Gongjun
Wu, Chong
and
Pan, Wei
2021.
Asymptotically independent U-statistics in high-dimensional testing.
The Annals of Statistics,
Vol. 49,
Issue. 1,
Guo, Jinhui
and
Lu, Yingyin
2023.
Joint behavior of point processes of clusters and partial sums for stationary bivariate Gaussian triangular arrays.
Annals of the Institute of Statistical Mathematics,
Vol. 75,
Issue. 1,
p.
17.