


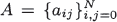 which have a given system of vectors orthogonal with respect to a given probability distribution as its right eigenvectors. Results of Hoare and Rahman are unified in this context, then all matrices with a given orthogonal polynomial system as right eigenvectors under the constraint a

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
ROSS, NATHAN
2009.
Step Size in Stein's Method of Exchangeable Pairs.
Combinatorics, Probability and Computing,
Vol. 18,
Issue. 6,
p.
979.
Osagiede, A.A.
and
Ekhosuehi, V.U.
2015.
Finding a continuous-time Markov chain via sparse stochastic matrices in manpower systems.
Journal of the Nigerian Mathematical Society,
Vol. 34,
Issue. 1,
p.
94.
Seneta, Eugene
2016.
Markov Chains as Models in Statistical Mechanics.
Statistical Science,
Vol. 31,
Issue. 3,
p.
399.