


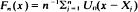 where U
 , is obtained if U
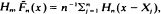 , where
 is a sequence of d.f.'s converging weakly to U
 . It is shown that if F satisfies some smoothness conditions and the perturbation is not too drastic then
 ‘has the Chung–Smirnov property'; i.e., with probability one,
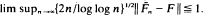 1. But if the perturbation is too vigorous then this property is lost: e.g., if F is the uniform distribution and H
 or


Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Winter, B.B.
1981.
Fourier series methods in nonparametric estimation.
Series Statistics,
Vol. 12,
Issue. 3,
p.
339.
Cheng, K. F.
1982.
Contributions to nonparametric generalized failure rate function estimation.
Metrika,
Vol. 29,
Issue. 1,
p.
215.
1983.
Nonparametric Functional Estimation.
p.
483.
Falk, M.
1983.
Relative efficiency and deficiency of kernel type estimators of smooth distribution functions.
Statistica Neerlandica,
Vol. 37,
Issue. 2,
p.
73.
Singh, R.S.
Gasser, T.
and
Prasad, B.
1983.
Nonparametric estimates of distribution functions.
Communications in Statistics - Theory and Methods,
Vol. 12,
Issue. 18,
p.
2095.
Nixdorf, R.
1985.
CENTRAL LIMIT THEORMS IN C[0,1] FOR A CLASS OF ESTIMATORS OF A DISTRIBUTION FUNCTION.
Statistica Neerlandica,
Vol. 39,
Issue. 3,
p.
251.
Peter D., Hill
1985.
Kernel estimation of a distribution function.
Communications in Statistics - Theory and Methods,
Vol. 14,
Issue. 3,
p.
605.
Puri, Madan L
and
Ralescu, Stefan S
1986.
Central limit theorem for perturbed empirical distribution functions evaluated at a random point.
Journal of Multivariate Analysis,
Vol. 19,
Issue. 2,
p.
273.
Boos, D. D.
1986.
Rates of convergence for the distance between distribution function estimators.
Metrika,
Vol. 33,
Issue. 1,
p.
197.
Gajek, Les⌈aw
1987.
On improving distribution function estimators which are not monotonic functions.
Statistics & Probability Letters,
Vol. 5,
Issue. 3,
p.
213.
Swanepoel, Jan W.H.
1988.
Mean intergrated squared error properties and optimal kernels when estimating a diatribution function.
Communications in Statistics - Theory and Methods,
Vol. 17,
Issue. 11,
p.
3785.
Lea, Cheun-Der
and
Puri, Madan L.
1988.
Asymptotic properties of perturbed empirical distribution functions evaluated at a random point.
Journal of Statistical Planning and Inference,
Vol. 19,
Issue. 2,
p.
201.
Yukich, J.E.
1989.
A note on limit theorems for perturbed empirical processes.
Stochastic Processes and their Applications,
Vol. 33,
Issue. 1,
p.
163.
Ghorai, J. K.
and
Susarla, V.
1990.
Kernel estimation of a smooth distribution function based on censored data.
Metrika,
Vol. 37,
Issue. 1,
p.
71.
Mack, Y.P.
and
Matloff, Norman S.
1990.
Estimating a mixing distribution in a multiple observation setting.
Statistics & Probability Letters,
Vol. 10,
Issue. 5,
p.
369.
Sarda, P.
1991.
Nonparametric Functional Estimation and Related Topics.
p.
261.
Gröwe, N.
and
Römisch, W.
1992.
Proceedings of the Sixth European Conference on Mathematics in Industry August 27–31, 1991 Limerick.
p.
169.
Ralescu, Stefan S.
1992.
Asymptotic deviations between perturbed empirical and quantile processes.
Journal of Statistical Planning and Inference,
Vol. 32,
Issue. 2,
p.
243.
Gröwe, Nicole
and
Römisch, Werner
1992.
Stochastic Optimization.
Vol. 379,
Issue. ,
p.
111.
Ralescu, Stefan S.
and
Sun, Shan
1993.
Necessary and sufficient conditions for the asymptotic normality of perturbed sample quantiles.
Journal of Statistical Planning and Inference,
Vol. 35,
Issue. 1,
p.
55.