




No CrossRef data available.
Article contents
A Diffusion Limit for Generalized Correlated Random Walks
Published online by Cambridge University Press: 14 July 2016
Abstract
Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.
A generalized correlated random walk is a process of partial sums 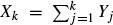 such that (X, Y) forms a Markov chain. For a sequence (X n ) of such processes in which each
 takes only two values, we prove weak convergence to a diffusion process whose generator is explicitly described in terms of the limiting behaviour of the transition probabilities for the Y n . Applications include asymptotics of option replication under transaction costs and approximation of a given diffusion by regular recombining binomial trees.
Keywords
MSC classification
Information
- Type
- Research Papers
- Information
- Copyright
- © Applied Probability Trust 2006
References
Boyle, P. P. and Vorst, T. (1992). Option replication in discrete time with transaction costs. J. Finance
47, 271–293.Google Scholar
Chen, A. and Renshaw, E. (1994). The general correlated random walk. J. Appl. Prob.
31, 869–884.Google Scholar
Ethier, S. and Kurtz, T. (1986). Markov Processes. Characterization and Convergence. John Wiley, New York.CrossRefGoogle Scholar
Gruber, U. (2004). Convergence of binomial large investor models and general correlated random walks. Doctoral Thesis, Technical University of Berlin. Available at http://edocs.tu-berlin.de/diss/2004/gruber_urs.htm.Google Scholar
Horváth, L. and Shao, Q.-M. (1998). Limit distributions of directionally reinforced random walks. Adv. Math.
134, 367–383.Google Scholar
Kusuoka, S. (1995). Limit theorem on option replication cost with transaction costs. Ann. Appl. Prob.
5, 198–221.Google Scholar
Mauldin, R. D., Monticino, M. and von Weizsäcker, H. (1996). Directionally reinforced random walks. Adv. Math.
117, 239–252.CrossRefGoogle Scholar
Nelson, D. B. (1990). ARCH models as diffusion approximations. J. Econometrics
45, 7–38.Google Scholar
Nelson, D. B. and Ramaswamy, K. (1990). Simple binomial processes as diffusion approximations in financial models. Rev. Financial Studies
3, 393–430.CrossRefGoogle Scholar
Opitz, A. (1999). Zur Asymptotik der Bewertung von Optionen unter Transaktionskosten im Binomialmodell. Diploma Thesis, Technical University of Berlin.Google Scholar
Renshaw, E. and Henderson, R. (1981). The correlated random walk. J. Appl. Prob.
18, 403–414.Google Scholar
Stroock, D. W. and Varadhan, S. R. S. (1979). Multidimensional Diffusion Processes. Springer, New York.Google Scholar
Szász, D. and Tóth, B. (1984). Persistent random walks in a one-dimensional random environment. J. Statist. Phys.
37, 27–38.Google Scholar
 You have
Access
- 11
- Cited by