


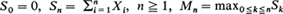 and for x ≧ 0 define
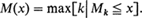

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Heyde, C.C.
1969.
On the maximum of sums of random variables and the supremum functional for stable processes.
Journal of Applied Probability,
Vol. 6,
Issue. 2,
p.
419.
Prabhu, N. U.
1970.
Limit theorems for the single server queue with traffic intensity one.
Journal of Applied Probability,
Vol. 7,
Issue. 1,
p.
227.
Bingham, N. H.
1973.
Maxima of sums of random variables and suprema of stable processes.
Zeitschrift f�r Wahrscheinlichkeitstheorie und Verwandte Gebiete,
Vol. 26,
Issue. 4,
p.
273.
Iosifescu, M.
and
Tăutu, P.
1973.
Stochastic processes and applications in biology and medicine I.
Vol. 3,
Issue. ,
p.
11.
Whitt, Ward
1974.
Mathematical Methods in Queueing Theory.
Vol. 98,
Issue. ,
p.
307.
Prabhu, N. U.
1980.
Stochastic Storage Processes.
p.
48.
Nevzorov, V. B.
1982.
Maximum of cumulative sums for the Cauchy distribution.
Journal of Soviet Mathematics,
Vol. 20,
Issue. 3,
p.
2221.
Iksanov, Alex
and
Möhle, Martin
2008.
On the number of jumps of random walks with a barrier.
Advances in Applied Probability,
Vol. 40,
Issue. 1,
p.
206.
Gnedin, Alexander V.
Iksanov, Alexander M.
Negadajlov, Pavlo
and
Rösler, Uwe
2009.
The Bernoulli sieve revisited.
The Annals of Applied Probability,
Vol. 19,
Issue. 4,
p.
1634.
Gut, Allan
2009.
Stopped Random Walks.
p.
79.
Sreehari, M.
2010.
On the equivalence of limit distributions of a sum and of a maximum sum of independent random variables.
Statistics & Probability Letters,
Vol. 80,
Issue. 9-10,
p.
860.
Heyde, C. C.
2010.
Selected Works of C.C. Heyde.
p.
92.
Padash, Amin
Capała, Karol
Kantz, Holger
Dybiec, Bartłomiej
Shokri, Babak
Metzler, Ralf
and
V Chechkin, Aleksei
2025.
First-passage statistics for Lévy flights with a drift.
Journal of Physics A: Mathematical and Theoretical,
Vol. 58,
Issue. 18,
p.
185002.