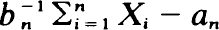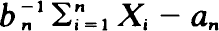
Hostname: page-component-7b7567c8c-wxvwp Total loading time: 0 Render date: 2026-11-17T02:45:39.826Z Has data issue: false hasContentIssue false

Limit theorems for sums of a sequence of random variables defined on a Markov chain

Published online by Cambridge University Press:  14 July 2016

David B. Wolfson*
Affiliation:
McGill University, Montreal

Abstract

Let {(Jn, Xn ), n ≧ 0} be the standard J–X process of Markov renewal theory. Suppose {J n, n ≧ 0} is irreducible, aperiodic and positive recurrent. It is shown using the strong mixing condition, that if converges in distribution, where an, bn > 0 (bn → ∞) are real constants, then the limit law F must be stable. Suppose Q(x) = {PijHi (x)} is the semi-Markov matrix of {(J n X n ), n ≧ 0}. Then the n-fold convolution, Q ∗n (bnx + anbn ), converges in distribution to F(x)Π if and only if converges in distribution to F. Π is the matrix of stationary transition probabilities of {J n , n ≧ 0}. Sufficient conditions on the Hi 's are given for the convergence of the sequence of semi-Markov matrices to F(x)Π, where F is stable.

Information

Type
Short Communications
Copyright
Copyright © Applied Probability Trust 1977 

Access options

Get access to the full version of this content by using one of the access options below. (Log in options will check for institutional or personal access. Content may require purchase if you do not have access.)

Article purchase

Temporarily unavailable