


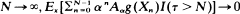 as N → ∞, then
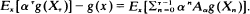 Applications of the results are considered.

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Abdel-Hameed, M.
and
Shimi, I. N.
1978.
Optimal replacement of damaged devices.
Journal of Applied Probability,
Vol. 15,
Issue. 1,
p.
153.
Rosenfield, Donald B
and
Shapiro, Roy D
1981.
Optimal adaptive price search.
Journal of Economic Theory,
Vol. 25,
Issue. 1,
p.
1.
Karunamuni, Rohana J.
and
Zhang, Shunpu
1996.
Empirical Bayes detection of a change in distribution.
Annals of the Institute of Statistical Mathematics,
Vol. 48,
Issue. 2,
p.
229.
Abdel-Hameed, Mohamed
1999.
Semi-Markov Models and Applications.
p.
337.
Skarupski, Marek
2020.
Secretary Problem with Possible Errors in Observation.
Mathematics,
Vol. 8,
Issue. 10,
p.
1639.
Cacciapuoti, Angela Sara
Illiano, Jessica
Viscardi, Michele
and
Caleffi, Marcello
2024.
Multipartite Entanglement Distribution in the Quantum Internet: Knowing When to Stop!.
IEEE Transactions on Network and Service Management,
Vol. 21,
Issue. 6,
p.
6041.