


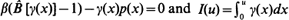 . It is shown that
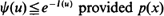 is non-decreasing and that log ψ(u) ≈ –I(u) in a slow Markov walk limit. Though the results and conditions are of large deviations type, the proofs are elementary and utilize piecewise comparisons with standard risk processes with a constant p. Also simulation via importance sampling using local exponential change of measure defined in terms of the γ(x) is discussed and some numerical results are presented.

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Asmussen, Søren
and
Klüppelberg, Claudia
1996.
Large deviations results for subexponential tails, with applications to insurance risk.
Stochastic Processes and their Applications,
Vol. 64,
Issue. 1,
p.
103.
Kagan, Yan Y.
1997.
Earthquake size distribution and earthquake insurance.
Communications in Statistics. Stochastic Models,
Vol. 13,
Issue. 4,
p.
775.
Paulsen, Jostein
1998.
Ruin theory with compounding assets — a survey.
Insurance: Mathematics and Economics,
Vol. 22,
Issue. 1,
p.
3.
Asmussen, Søren
1998.
Extreme Value Theory for Queues Via Cycle Maxima.
Extremes,
Vol. 1,
Issue. 2,
p.
137.
Asmussen, Søren
1998.
Subexponential asymptotics for stochastic processes: extremal behavior, stationary distributions and first passage probabilities.
The Annals of Applied Probability,
Vol. 8,
Issue. 2,
p.
354.
Asmussen, Søren
and
Rubinstein, Reuven Y.
1999.
Sensitivity Analysis of Insurance Risk Models via Simulation.
Management Science,
Vol. 45,
Issue. 8,
p.
1125.
J. Vázquez-Abad, Felisa
2000.
RPA pathwise derivative estimation of ruin probabilities.
Insurance: Mathematics and Economics,
Vol. 26,
Issue. 2-3,
p.
269.
Vázquez-abad, Felisa J.
Andrew, Lachlan L. H.
and
Everitt, David
2002.
Estimation of blocking probabilities in cellular networks with dynamic channel assignment.
ACM Transactions on Modeling and Computer Simulation,
Vol. 12,
Issue. 1,
p.
54.
Paulsen, Jostein
Kasozi, Juma
and
Steigen, Andreas
2005.
A numerical method to find the probability of ultimate ruin in the classical risk model with stochastic return on investments.
Insurance: Mathematics and Economics,
Vol. 36,
Issue. 3,
p.
399.
Ganesh, A.
Macci, C.
and
Torrisi, G. L.
2007.
A class of risk processes with reserve-dependent premium rate: sample path large deviations and importance sampling.
Queueing Systems,
Vol. 55,
Issue. 2,
p.
83.
Albrecher, Hansjörg
and
Hartinger, Jürgen
2007.
A Risk Model with Multilayer Dividend Strategy.
North American Actuarial Journal,
Vol. 11,
Issue. 2,
p.
43.
He, Jing-min
Wu, Rong
and
Zhang, Hua-yue
2008.
Ruin probabilities of a surplus process described by PDMPs.
Acta Mathematicae Applicatae Sinica, English Series,
Vol. 24,
Issue. 1,
p.
117.
Paulsen, Jostein
2008.
Ruin models with investment income.
Probability Surveys,
Vol. 5,
Issue. none,
p.
416.
2008.
Stochastic Processes for Insurance & Finance.
p.
617.
Blanchet, Jose
and
Glynn, Peter
2009.
Efficient rare event simulation of continuous time Markovian perpetuities.
p.
444.
Liu, Yuping
and
Ma, Jin
2009.
Optimal reinsurance/investment problems for general insurance models.
The Annals of Applied Probability,
Vol. 19,
Issue. 4,
p.
1495.
Paulsen, Jostein
2010.
Encyclopedia of Quantitative Finance.
Macci, Claudio
and
Torrisi, Giovanni Luca
2011.
Risk processes with shot noise Cox claim number process and reserve dependent premium rate.
Insurance: Mathematics and Economics,
Vol. 48,
Issue. 1,
p.
134.
Macci, Claudio
2011.
Large deviations for estimators of unknown probabilities, with applications in risk theory.
Statistics & Probability Letters,
Vol. 81,
Issue. 1,
p.
16.
Chen, Bohan
Rhee, Chang-Han
and
Zwart, Bert
2018.
Importance sampling of heavy-tailed iterated random functions.
Advances in Applied Probability,
Vol. 50,
Issue. 3,
p.
805.