


 be a linear Brownian motion starting from 0. Following Dufresne (1989), (1990), De Schepper and Goovaerts (1992) and De Schepper et al. (1992), we are interested in the process
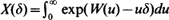 (for δ > 0), which stands for the discounted values of a continuous perpetuity payment. We characterize the upper class (in the sense of Paul Lévy) of X, as δ tends to zero, by an integral test. The law of the iterated logarithm is obtained as a straightforward consequence. The process
 exp(W(u))du is studied as well. The class of upper functions of Z is provided. An application to the lim inf behaviour of the winding clock of planar Brownian motion is presented.

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Keprta, Stanislav
1998.
Asymptotic Methods in Probability and Statistics.
p.
253.
Shi, Zhan
1998.
Windings of Brownian motion and random walks in the plane.
The Annals of Probability,
Vol. 26,
Issue. 1,
p.
112.
Csáki, Endre
Csörgő, Miklós
Földes, Antónia
and
Révész, Pál
2000.
Asymptotic properties of integral functionals of geometric stochastic processes.
Journal of Applied Probability,
Vol. 37,
Issue. 2,
p.
480.