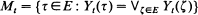Hostname: page-component-6898cfcb55-cbk24 Total loading time: 0 Render date: 2026-11-11T11:05:39.832Z Has data issue: false hasContentIssue false

Super-extremal processes and the argmax process

Published online by Cambridge University Press:  14 July 2016

Sidney I. Resnick*
Affiliation:
Cornell University
Rishin Roy*
Affiliation:
University of Toronto
*
∗ Postal address: School of Operations Research and Industrial Engineering, ETC Building, Cornell University, Ithaca, NY 14853, USA.
∗∗ Present address: Paribas Corporation, Equitable Tower, 787 7th Avenue, New York, NY 10019, USA.

Abstract

In this paper, we develop the probabilistic foundations of the dynamic continuous choice problem. The underlying choice set is a compact metric space E such as the unit interval or the unit square. At each time point t, utilities for alternatives are given by a random function . To achieve a model of dynamic continuous choice, the theory of classical vector-valued extremal processes is extended to super-extremal processesY= {Yt, t > 0}. At any t > 0, Y t is a random upper semicontinuous function on a locally compact, separable, metric space E. General path properties of Y are discussed and it is shown that Y is Markov with state-space US(E). For each t > 0, Y t is associated.

For a compact metric E, we consider the argmax process M = {Mt, t > 0}, where . In the dynamic continuous choice application, the argmax process M represents the evolution of the set of random utility maximizing alternatives. M is a closed set-valued random process, and its path properties are investigated.

Information

Type
Research Article
Copyright
Copyright © Applied Probability Trust 1994 

Access options

Get access to the full version of this content by using one of the access options below. (Log in options will check for institutional or personal access. Content may require purchase if you do not have access.)

Article purchase

Temporarily unavailable