
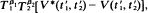
Hostname: page-component-7b7567c8c-48dgx Total loading time: 0 Render date: 2026-11-18T09:24:17.872Z Has data issue: false hasContentIssue false

The weak convergence of a class of estimators of the variance function of a two-dimensional Poisson process

Published online by Cambridge University Press:  14 July 2016

A. M. Liebetrau*
Affiliation:
The Johns Hopkins University

Abstract

Results of a previous paper (Liebetrau (1977a)) are extended to higher dimensions. An estimator V∗(t 1, t 2) of the variance function V(t 1, t 2) of a two-dimensional process is defined, and its first- and second-moment structure is given assuming the process to be Poisson. Members of a class of estimators of the form where and for 0 < α i < 1, are shown to converge weakly to a non-stationary Gaussian process. Similar results hold when the t′i are taken to be constants, when V is replaced by a suitable estimator and when the dimensionality of the underlying Poisson process is greater than two.

Information

Type
Short Communications
Copyright
Copyright © Applied Probability Trust 1978 

Access options

Get access to the full version of this content by using one of the access options below. (Log in options will check for institutional or personal access. Content may require purchase if you do not have access.)

Article purchase

Temporarily unavailable
