

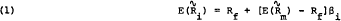
 = expected rate of return on security i,
 = expected rate of return on the market portfolio, and
 .

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Bey, Roger P.
1979.
MEAN‐VARIANCE, MEAN‐SEMIVARIANCE, AND DCF ESTIMATES OF A PUBLIC UTILITY'S COST OF EQUITY*.
Journal of Financial Research,
Vol. 2,
Issue. 1,
p.
13.
PRICE, KELLY
PRICE, BARBARA
and
NANTELL, TIMOTHY J.
1982.
Variance and Lower Partial Moment Measures of Systematic Risk: Some Analytical and Empirical Results.
The Journal of Finance,
Vol. 37,
Issue. 3,
p.
843.
Kittrell, William
Hirt, Geoffrey
and
Mohmood, Mo
1983.
THE CAPITAL ASSET PRICING MODEL IN TERMS OF LOWER PARTIAL MOMENTS: AN EMPIRICAL INVESTIGATION.
Financial Review,
Vol. 18,
Issue. 3,
p.
65.
Bamberg, Günter
1986.
Capital Market Equilibria.
p.
7.
Srivastava, Suresh C.
and
Essayyad, Musa
1994.
Investigating a new methodology for ranking international mutual funds.
Journal of Economics and Finance,
Vol. 18,
Issue. 3,
p.
241.
Low, Cheekiat
2000.
Ang, Andrew
Chen, Joseph S.
and
Xing, Yuhang
2004.
Post, Thierry
and
van Vliet, Pim
2004.
Galagedera, Don (Tissa) U. A.
and
Brooks, Robert Darren
2005.
Galagedera, Don (Tissa) U. A.
Maharaj, Elizabeth Ann
and
Brooks, Robert Darren
2006.
Ang, Andrew
Chen, Joseph
and
Xing, Yuhang
2006.
Downside Risk.
Review of Financial Studies,
Vol. 19,
Issue. 4,
p.
1191.
Galagedera, Don U.A.
and
Brooks, Robert D.
2007.
Is co-skewness a better measure of risk in the downside than downside beta?.
Journal of Multinational Financial Management,
Vol. 17,
Issue. 3,
p.
214.
Galagedera, Don U. A.
Maharaj, Elizabeth A.
and
Brooks, Robert
2008.
Relationship between downside risk and return: new evidence through a multiscaling approach.
Applied Financial Economics,
Vol. 18,
Issue. 20,
p.
1623.
Lin Lee, Chyi
Robinson, Jon
and
Reed, Richard
2008.
Listed property trusts and downside systematic risk sensitivity.
Journal of Property Investment & Finance,
Vol. 26,
Issue. 4,
p.
304.
Mamoghli, Chokri
and
Daboussi, Sami
2008.
Bali, Turan G.
Cakici, Nusret
and
Whitelaw, Robert F.
2011.
2012.
Liu, Wei
Kolari, James W.
and
Huang, Jianhua Z.
2012.
A New Asset Pricing Model Based on the Zero-Beta CAPM: Theory and Evidence.
SSRN Electronic Journal,
Bali, Turan G.
Cakici, Nusret
and
Whitelaw, Robert F.
2012.
Post, Thierry
van Vliet, Pim
and
Lansdorp, Simon
2012.