

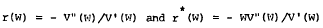
 while he exhibits increasing, constant, or decreasing relative risk aversion as
 .

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Hawawini, Gabriel A.
1983.
The Theory of Risk Aversion and Liquidity Preference: A Geometric Exposition.
The American Economist,
Vol. 27,
Issue. 2,
p.
42.
Hawawini, Gabriel
1986.
The geometry of risk aversion: A Pedagogic note.
Journal of Economics and Business,
Vol. 38,
Issue. 2,
p.
93.
Miao, Cheng
Xie, Jing
and
Li, Yingdong
2024.
Evaluating the risk and its acceptability of crop yield reduction in Northwest China under the impact of wind hail disasters.
Natural Hazards,
Vol. 120,
Issue. 15,
p.
14027.