



No CrossRef data available.
Article contents
A Note on the Uniqueness of Portfolio Choice
Published online by Cambridge University Press: 19 October 2009
Extract
In [1] the authors proved the following proposition.
Proposition 1: If the positive random variables  are exchangeable and linearly independent and if u(x) is strictly concave and satisfies
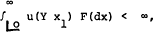
then the unique optimal choice is given by  .
Information
- Type
- Communications
- Information
- Journal of Financial and Quantitative Analysis , Volume 11 , Issue 3 , September 1976, pp. 481 - 484
- Copyright
- Copyright © School of Business Administration, University of Washington 1976
References
REFERENCES
[1]Davies, P. L., and Ronning, G.. “Existence, Uniqueness and Continuity of Portfolio Choice.” Zeitschrift fur Nationalokonomie, vol. 34 (1974), pp. 137–143.CrossRefGoogle Scholar
[2]Feller, W.An Introduction to Probability Theory and Its Applications, vol. 2. New York: Wiley, 1966.Google Scholar
[3]Ramachandran, B., and Rao, C. R.. “Solutions of Functional Equations Arising in Some Regression Problems and a Characterization of the Cauchy Law.” Sankhya, Ser. A., vol. 32 (1970), pp. 1–30.Google Scholar
[4]Samuelson, P. A. “General Proof that Diversification Pays.” Journal of Financial and Quantitative Analysis, vol. 2 (1967), pp. 1–13.CrossRefGoogle Scholar
[5]Samuelson, P. A. “Limited Liability, Short Selling, Bounded Utility, and Infinite-Variance Stable Distributions.” Journal of Financial and Quantitative Analysis, September 1976.Google Scholar
[6]Shimizu, R. “Characteristic Functions Satisfying a Certain Functional Equation (1).” Ann. Inst. Statist. Math., vol. 20 (1968), pp. 187–209.CrossRefGoogle Scholar